
VA loans in Washington State remain the most powerful home-buying tool for veterans, active-duty service members, and eligible surviving spouses in 2026. These mortgages offer 100% financing, require no private mortgage insurance (PMI), and feature competitive interest rates, making homeownership accessible even in high-cost regions like Seattle, Tacoma, and Bellevue.
The Washington State housing market in 2026 presents a unique landscape for military buyers. From the bustling corridors surrounding Joint Base Lewis-McChord (JBLM) to the naval hubs in Kitsap County and the growing tech sectors of the Puget Sound, the VA loan program serves as a critical bridge to equity. Understanding the nuances of this federal benefit—and how it interacts with Washington’s specific real estate laws and tax codes—is essential for any eligible borrower looking to maximize their investment.
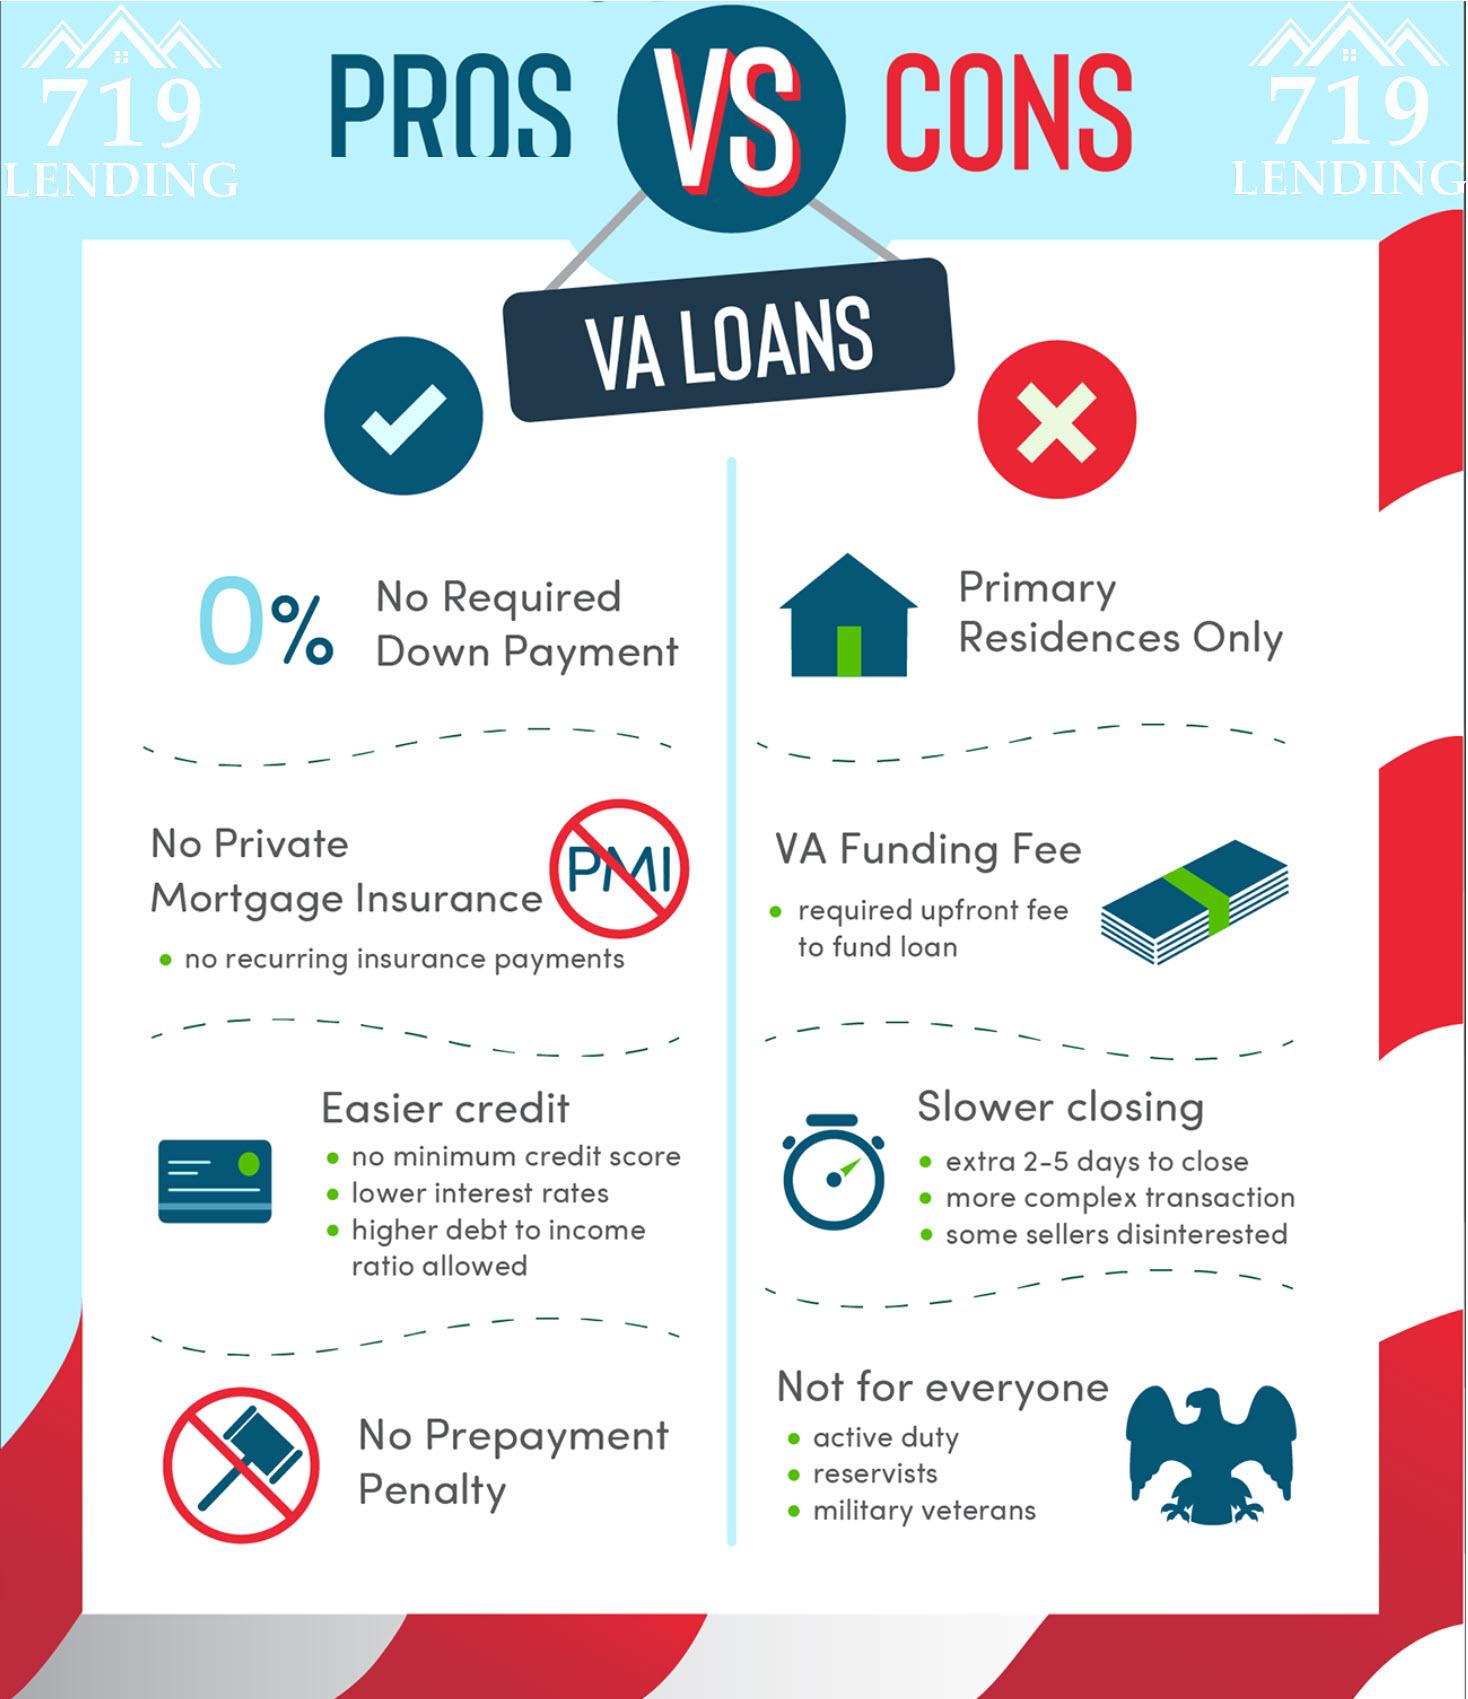
The Core Benefits of VA Loans in Washington State
The primary appeal of the VA home loan program is its departure from the restrictive requirements of conventional lending. In a state where median home prices often exceed national averages, the financial relief provided by the Department of Veterans Affairs is substantial.
Zero Down Payment Requirement
Most conventional loans require a minimum of 3% to 5% down, while FHA loans require 3.5%. In Washington's 2026 market, where a modest starter home might cost $500,000, a 5% down payment represents $25,000 in cash—a significant barrier for many families. The VA loan eliminates this hurdle, allowing buyers to finance 100% of the purchase price.
No Private Mortgage Insurance (PMI)
For non-VA borrowers, putting down less than 20% usually triggers the requirement for PMI, an monthly insurance premium that protects the lender but offers no benefit to the buyer. Because the federal government guarantees a portion of the VA loan, lenders do not require PMI. This can save Washington homeowners between $150 and $400 per month, depending on the loan amount and credit score.
Competitive Interest Rates
VA loans typically offer interest rates 0.25% to 0.50% lower than conventional mortgages. Over a 30-year term on a Pacific Northwest property, this interest differential can result in tens of thousands of dollars in savings.
Eligibility and the Certificate of Eligibility (COE)
Before entering the Washington real estate market, a borrower must establish their eligibility. The Department of Veterans Affairs determines who qualifies based on service duration and character of discharge.
Minimum Service Requirements
In 2026, the criteria for eligibility generally include:
- Active Duty: 90 continuous days of service.
- Peacetime Veterans: 181 days of continuous active duty.
- National Guard and Reserve: Typically six years of service, though 90 days of active-duty service (with at least 30 consecutive days) under certain mobilization orders also qualifies.
- Surviving Spouses: Spouses of service members who died in the line of duty or from a service-connected disability.
Obtaining the COE
The Certificate of Eligibility (COE) is the only document that proves to a lender that you have "entitlement" for a VA loan. Most Washington-based lenders can pull this document instantly through the VA’s online portal if they have your Social Security number and date of birth. Veterans can also apply manually through the VA.gov eBenefits portal. You will generally need your DD Form 214 (Member 4 Copy) to verify your service history.
Understanding VA Loan Limits in Washington for 2026
A common misconception is that there is a "maximum" amount a veteran can borrow. As of the Blue Water Navy Vietnam Veterans Act of 2019, which remains in full effect in 2026, the VA does not impose caps on the amount an eligible borrower with full entitlement can borrow with zero money down.
However, "loan limits" still matter in two specific scenarios:
- Partial Entitlement: If you already have an active VA loan or have defaulted on one in the past, your remaining entitlement is tied to the local county loan limits.
- Jumbo VA Loans: While the VA doesn't limit the loan, individual lenders in Washington may have their own internal ceilings for 100% financing, often ranging from $1 million to $1.5 million depending on the county (e.g., King, Pierce, or Snohomish).
In high-cost areas like Seattle, the 2026 conforming loan limits are significantly higher than in rural Eastern Washington. If you are using partial entitlement, your "maximum" zero-down loan will be dictated by the Federal Housing Finance Agency (FHFA) limits for that specific county.
The VA Funding Fee: 2026 Costs and Exemptions
While VA loans eliminate PMI and down payments, they do require a one-time "Funding Fee." This fee helps sustain the program for future generations of veterans. The fee is a percentage of the total loan amount and can be rolled into the mortgage.
2026 Funding Fee Rates
| Category | First-Time Use | Subsequent Use |
|---|---|---|
| Purchase (0% Down) | 2.15% | 3.30% |
| Purchase (5% - 9.9% Down) | 1.50% | 1.50% |
| Purchase (10% or More Down) | 1.25% | 1.25% |
| Cash-Out Refinance | 2.15% | 3.30% |
| IRRRL (Streamline Refinance) | 0.50% | 0.50% |
Who is Exempt?
Many Washington veterans do not have to pay this fee at all. You are exempt if:
- You receive disability compensation for a service-connected disability.
- You are eligible to receive disability compensation but are receiving retirement or active-duty pay instead.
- You are a surviving spouse of a veteran who died in service or from a service-connected disability.
- You have a memorandum rating from the VA stating you are eligible for compensation based on a pre-discharge exam.
The VA Appraisal and Minimum Property Requirements (MPRs)
One of the most misunderstood aspects of buying a home in Washington with a VA loan is the appraisal process. A VA appraisal is not a home inspection; rather, it is an assessment of the home’s value and its adherence to the VA’s Minimum Property Requirements (MPRs).
Washington-Specific MPR Challenges
Washington's diverse climate and aging housing stock in older neighborhoods (like North Tacoma or Everett) can present specific MPR issues:
- Dry Rot and Pest Infestation: In the damp Pacific Northwest, wood-destroying organisms are common. The VA requires a clear pest inspection in Washington State.
- Heating Systems: The home must have a permanent heating source capable of maintaining a temperature of 50 degrees Fahrenheit in areas with plumbing.
- Roof Life: The appraiser must estimate that the roof has at least two to three years of remaining life.
- Peeling Paint: For homes built before 1978, lead-based paint is a major concern. Any peeling or cracked paint must be scraped and repainted.
If a property fails to meet these standards, the "Notice of Value" (NOV) will be issued with conditions. These repairs must be completed before the loan can close.
Navigating the Washington Real Estate Market as a VA Buyer
In 2026, the Washington market remains competitive. Some sellers may be hesitant to accept VA offers due to myths regarding "strict" appraisals or "zero-down" buyers being less financially stable. To succeed, buyers should work with agents who specialize in military relocation.
Strategy: The "Tidewater" Initiative
If a VA appraiser believes the home's value is coming in lower than the purchase price, they must trigger the Tidewater Initiative. This gives the buyer and seller 48 hours to provide additional "comparables" (recent home sales) to justify the price. In Washington’s rapidly shifting markets, this is a vital protection for buyers.
Seller-Paid Closing Costs
The VA allows sellers to pay up to 4% of the purchase price toward a buyer's "concessions." This can include paying off a buyer's judgments, credit card debt, or—most commonly—covering all of the buyer's closing costs. In a balanced market, this allows a veteran to move into a home with literally zero dollars out of pocket.
Washington State Property Tax Benefits for Disabled Veterans
While the VA loan is a federal program, Washington State offers additional localized benefits that can make homeownership even more affordable.
The Washington State Property Tax Exemption for Senior Citizens and Disabled Veterans can significantly reduce or even eliminate property tax obligations for those who qualify. As of 2026, eligibility is based on:
- Disability Rating: Generally, a service-connected disability rating of 80% or higher (though some 100% requirements apply for specific tiers).
- Income Thresholds: Income limits vary by county. For instance, the income limit in King County is much higher than in Stevens County, reflecting the local cost of living.
Reducing property taxes also reduces the monthly mortgage payment, as taxes are typically escrowed into the loan. Information on these exemptions can be found through the Washington Department of Revenue.
Common VA Loan Pitfalls to Avoid
Even with the advantages, Washington buyers can run into trouble if they aren't prepared.
- Ignoring the Home Inspection: Because the VA appraisal only looks for "Safety, Soundness, and Sanitary" issues, it may miss major structural or mechanical problems. Always hire an independent home inspector in addition to the VA appraiser.
- Credit Score Minimums: The VA does not set a minimum credit score, but lenders (banks) do. In 2026, most Washington lenders require a score of at least 580 to 620.
- Occupancy Requirements: You must intend to occupy the home as your primary residence. You cannot use a standard VA purchase loan for a dedicated investment property or a vacation home in the San Juan Islands unless you plan to live there for at least a year.
- The "Joint Loan" Complication: If you are buying a home with a non-veteran who is not your spouse, the VA only guarantees the veteran's portion of the loan. This usually requires a down payment on the non-veteran's half.
FAQ
Can I use a VA loan to buy a condo in Seattle?
Yes, but the condominium complex must be on the VA Approved Condo List. If the complex is not approved, your lender can request a "HUD/VA condo approval," but this process can take several weeks and requires the cooperation of the HOA board.
What is the maximum loan amount for a zero-down VA loan in King County?
For borrowers with full entitlement, there is no maximum loan limit in 2026. You can borrow $1.5 million or more with zero down, provided you have the income and credit to qualify for the monthly payments.
Does Washington State offer a "First-Time Homebuyer" program for veterans?
Yes. The Washington State Housing Finance Commission (WSHFC) offers the "Veterans Down Payment Assistance Grant." This can provide up to $10,000 in a low-interest second mortgage for veterans who meet certain income requirements, which can be used to cover closing costs.
Can I have two VA loans at the same time in Washington?
Yes. This is common when a service member is PCSing (Permanent Change of Station) from one base to another, such as moving from Fairchild AFB to JBLM. You can use your "bonus entitlement" to purchase a second home without selling the first, though a down payment may be required if the second loan exceeds your remaining entitlement.
Is the VA appraisal "tougher" than a conventional appraisal?
The VA appraisal is not necessarily tougher, but it is more focused on safety. A conventional appraiser might ignore a missing handrail or a broken window, whereas a VA appraiser will require those items to be fixed before the loan is finalized.
Final Recommendation for Washington Veterans
If you are an eligible service member or veteran in Washington State, your first step should be to secure a pre-approval from a lender that specializes in VA loans—ideally one familiar with the specific nuances of the Washington market. Ensure you have your DD-214 ready and verify your disability status to determine if you are exempt from the funding fee. In the competitive 2026 real estate climate, having a robust understanding of your entitlement and a lender who can articulate the strengths of a VA offer to a seller will be your greatest advantage.
Image Gallery
Select an image to open it in a new tab.


Lars Thomsen
Global Labor Markets and Economic Strategy Editor
