Obtaining your free TransUnion FICO Score is possible through various consumer-facing platforms, including credit card issuers, banking mobile applications, and official credit monitoring services. While TransUnion provides the underlying credit report data, FICO scores are generated by the Fair Isaac Corporation using proprietary algorithms, and access is typically provided to consumers as an educational tool to monitor credit health.
Understanding the Difference Between Credit Reports and FICO Scores
To navigate the landscape of credit monitoring, you must first distinguish between a credit report and a credit score. A credit report is a detailed accounting of your credit history, including open accounts, payment patterns, balance history, and public records like bankruptcies. TransUnion is one of the three major national credit reporting agencies (CRAs) that compile this data.
A FICO Score, however, is a numerical representation of the information found in your credit report. It is a product of the Fair Isaac Corporation, not the credit reporting agency itself. When you see a "TransUnion FICO Score," it means that the FICO algorithm is pulling data from your TransUnion credit file to calculate your risk assessment.
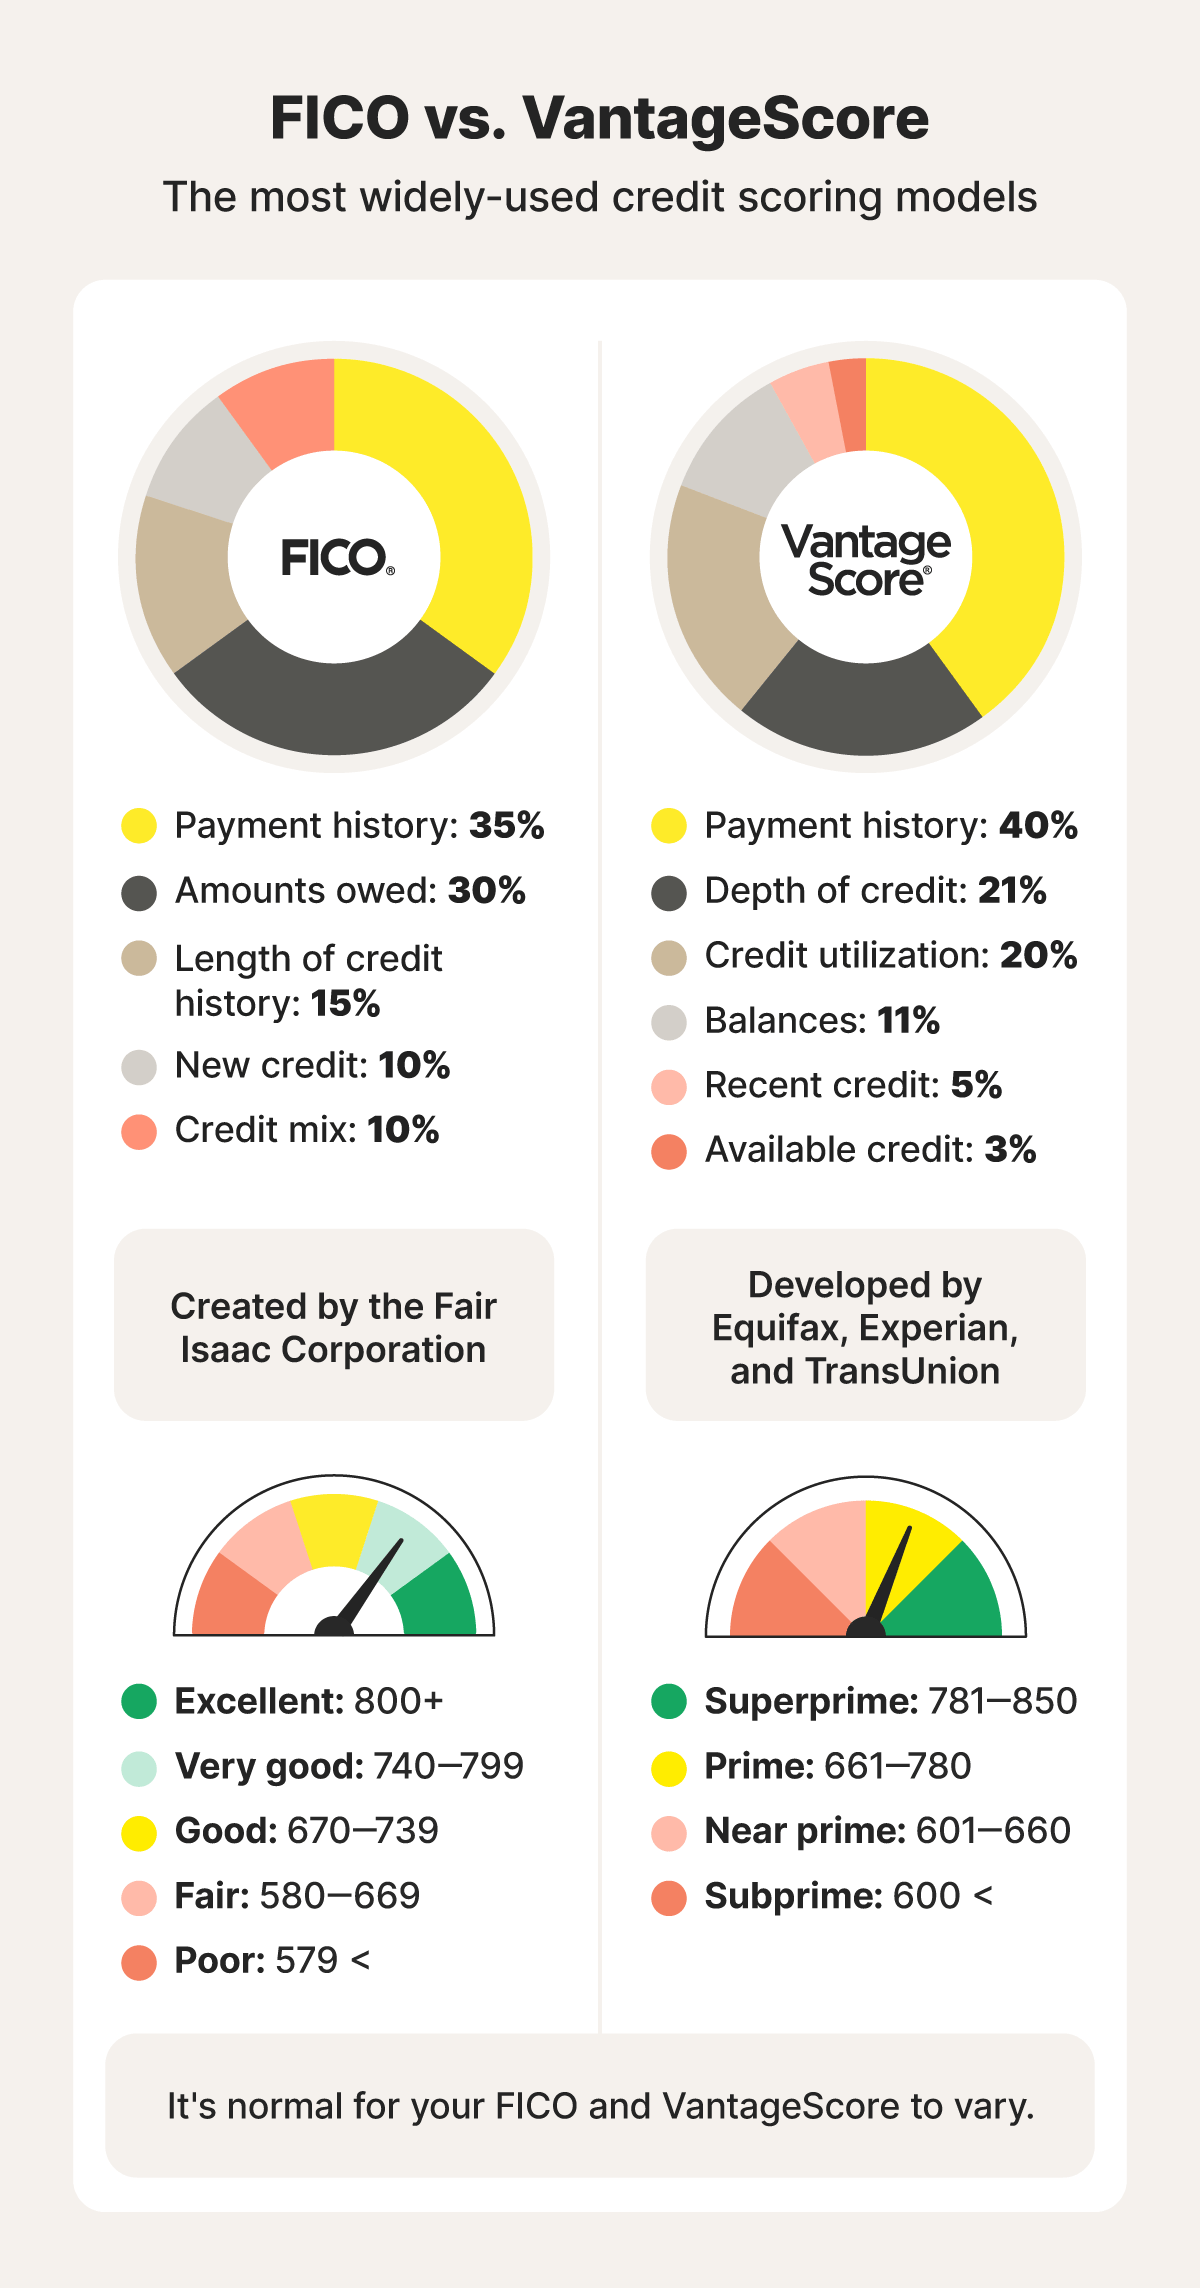
Many consumers confuse their FICO Score with "educational scores" provided by free websites. While educational scores—often based on the VantageScore model—are useful for tracking trends, lenders rarely use them for actual credit underwriting. If you are preparing to apply for a mortgage, auto loan, or credit card, verifying your actual FICO Score is essential because it is the industry standard for 90% of top lenders.
Why Accessing Your Score is Free
In 2026, the financial services industry prioritizes consumer transparency. Most major banking institutions and credit card companies provide free access to credit scores as a value-added service to encourage responsible financial habits and foster customer loyalty. By allowing you to check your score through their internal portals, these companies hope to provide you with insights that encourage better debt management while keeping you engaged with their mobile apps and websites.
Furthermore, the Fair Credit Reporting Act (FCRA) mandates that consumers have the right to access their credit reports. While the law specifically grants free annual access to your reports via AnnualCreditReport.com, the market has expanded this to include the frequent, automated provision of credit scores as a standard feature of modern personal finance management.
Methods for Checking Your FICO Score
You can retrieve your FICO Score using several reliable methods. It is important to note that you do not need to pay for a score unless you require constant monitoring or advanced identity theft protection services.
1. Credit Card Issuers and Banking Portals
The most common way to get a free FICO Score is through your primary financial institution. Many major credit card issuers (such as American Express, Discover, Bank of America, and Chase) provide a monthly "FICO Score Card" in their mobile apps or desktop banking dashboards. Check your statement or login portal for a tab labeled "Credit Score," "Credit Journey," or "Financial Health."
2. MyFICO Open-Access Programs
Fair Isaac Corporation partners with several financial institutions to provide the "Open Access" program. Through these partners, you can see your FICO Score for free, regardless of whether you have an active loan with that specific institution. These scores are updated regularly—usually once per month—and often include the primary factors (or "reason codes") that are negatively or positively impacting your score.
3. Credit Monitoring Apps
Several reputable financial technology applications offer credit score tracking. However, exercise caution: some applications use the VantageScore model rather than the FICO model. When signing up for an app, look for a disclosure that specifies the "scoring model" used. If the app does not explicitly state it provides a FICO Score, assume it is an educational score.
Eligibility and Prerequisites
To access your score for free, you must satisfy a few basic requirements. These are primarily centered on security and data validation:
- Identity Verification: You must be able to verify your identity. This typically involves answering "knowledge-based authentication" questions, such as identifying previous addresses, the amount of a past loan, or the month you opened a specific account.
- Active Credit History: You must have at least one account that has been reported to TransUnion within the last six months. If your credit file is too thin or inactive, a FICO score cannot be generated.
- Security Consent: You must provide consent for the service provider to pull your credit data. This is a "soft inquiry," which does not impact your credit score.
Comparison of Credit Scoring Models
When seeking your score, understanding what you are looking at is vital for accurate financial planning.
| Feature | FICO Score | VantageScore |
|---|---|---|
| Developer | Fair Isaac Corporation | Equifax, Experian, TransUnion |
| Industry Usage | Used by 90% of major lenders | Used by some lenders and fintechs |
| Data Source | Data from CRAs (e.g., TransUnion) | Data from CRAs |
| Accessibility | Available via banks/lenders | Available via free credit apps |
| Common Version | FICO 8 or FICO 9 | VantageScore 3.0 or 4.0 |
Troubleshooting Access Issues
If you are unable to view your score despite having an account with a participating institution, consider these common troubleshooting steps:
- Browser Cookies and Cache: Sometimes, clearing your browser’s cache or trying an "incognito" window resolves display issues within a banking dashboard.
- Mobile App Updates: If you are using a mobile app, ensure it is updated to the latest 2026 version. Outdated software often fails to retrieve real-time data from the backend servers.
- Account Status: If you have recently opened a new account or changed your address, your profile may be in a temporary "locked" state while the bank updates its internal verification records.
- Security Freezes: If you have placed a security freeze on your TransUnion credit report to prevent identity theft, you must temporarily lift the freeze to allow the FICO scoring service to access your data.
Important Considerations for Financial Health
While checking your score is important, the score itself is merely a diagnostic tool. Do not become "score obsessed." A FICO score fluctuates based on your credit utilization ratio, payment history, and the age of your credit accounts.
If you notice a sudden, unexpected drop in your TransUnion score, navigate to your full credit report. Look for "derogatory marks," such as a missed payment or an account you do not recognize. If you find errors, you have a legal right to dispute them directly with TransUnion. Disputing errors is a critical step in maintaining your financial reputation; it is far more effective than simply waiting for a score to recover on its own.
Frequently Asked Questions
Does checking my FICO score lower it? No. Checking your own credit score through a bank or a reputable credit monitoring service is considered a "soft inquiry." Soft inquiries are invisible to lenders and have absolutely no impact on your credit score.
How often does my TransUnion FICO score update? Most free services update the score once every 30 days. However, the underlying data in your TransUnion credit report updates whenever your creditors report new information, which typically happens once per billing cycle.
Why is my TransUnion score different from my Equifax or Experian score? Credit reporting agencies often have slightly different information regarding your accounts. A creditor might report to TransUnion but not the others, or there may be timing differences in when updates reach each bureau. Consequently, it is common to see slight variations across the three bureaus.
Can I get my FICO score for free without a credit card? Yes. Certain personal finance platforms and banking apps provide credit monitoring services that do not require you to hold a credit card with them. You generally only need to open a free account on their platform and complete the identity verification process.
Is my TransUnion FICO score the one lenders see? In most cases, yes. However, lenders may use different "versions" of the FICO score (e.g., FICO 8, FICO 9, or specialized versions like FICO Auto Score). While these versions are highly correlated, there may be slight differences in the final number a lender sees versus the number you see on your dashboard.
Next Actions for Consumers
To take control of your financial profile, perform these three actions:
- Check your dashboard: Log into your primary banking or credit card app today and locate your FICO score. Note the date of the last update and the specific factors the platform says are affecting your score.
- Verify your report: Use the official AnnualCreditReport.com service to pull your actual TransUnion credit report. Compare the account list against your own records to ensure all information is accurate.
- Monitor, don't obsess: Set a recurring calendar reminder to check your score once per quarter. This is frequent enough to spot identity theft or significant errors, but infrequent enough to avoid the stress of minor, non-consequential monthly fluctuations.
By focusing on responsible credit utilization—keeping your balances low and making payments on time—you will naturally maintain a healthy FICO score over time, regardless of which version the lender happens to use.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
