Why Auto Insurance in The Diamond, Richmond, VA Matters
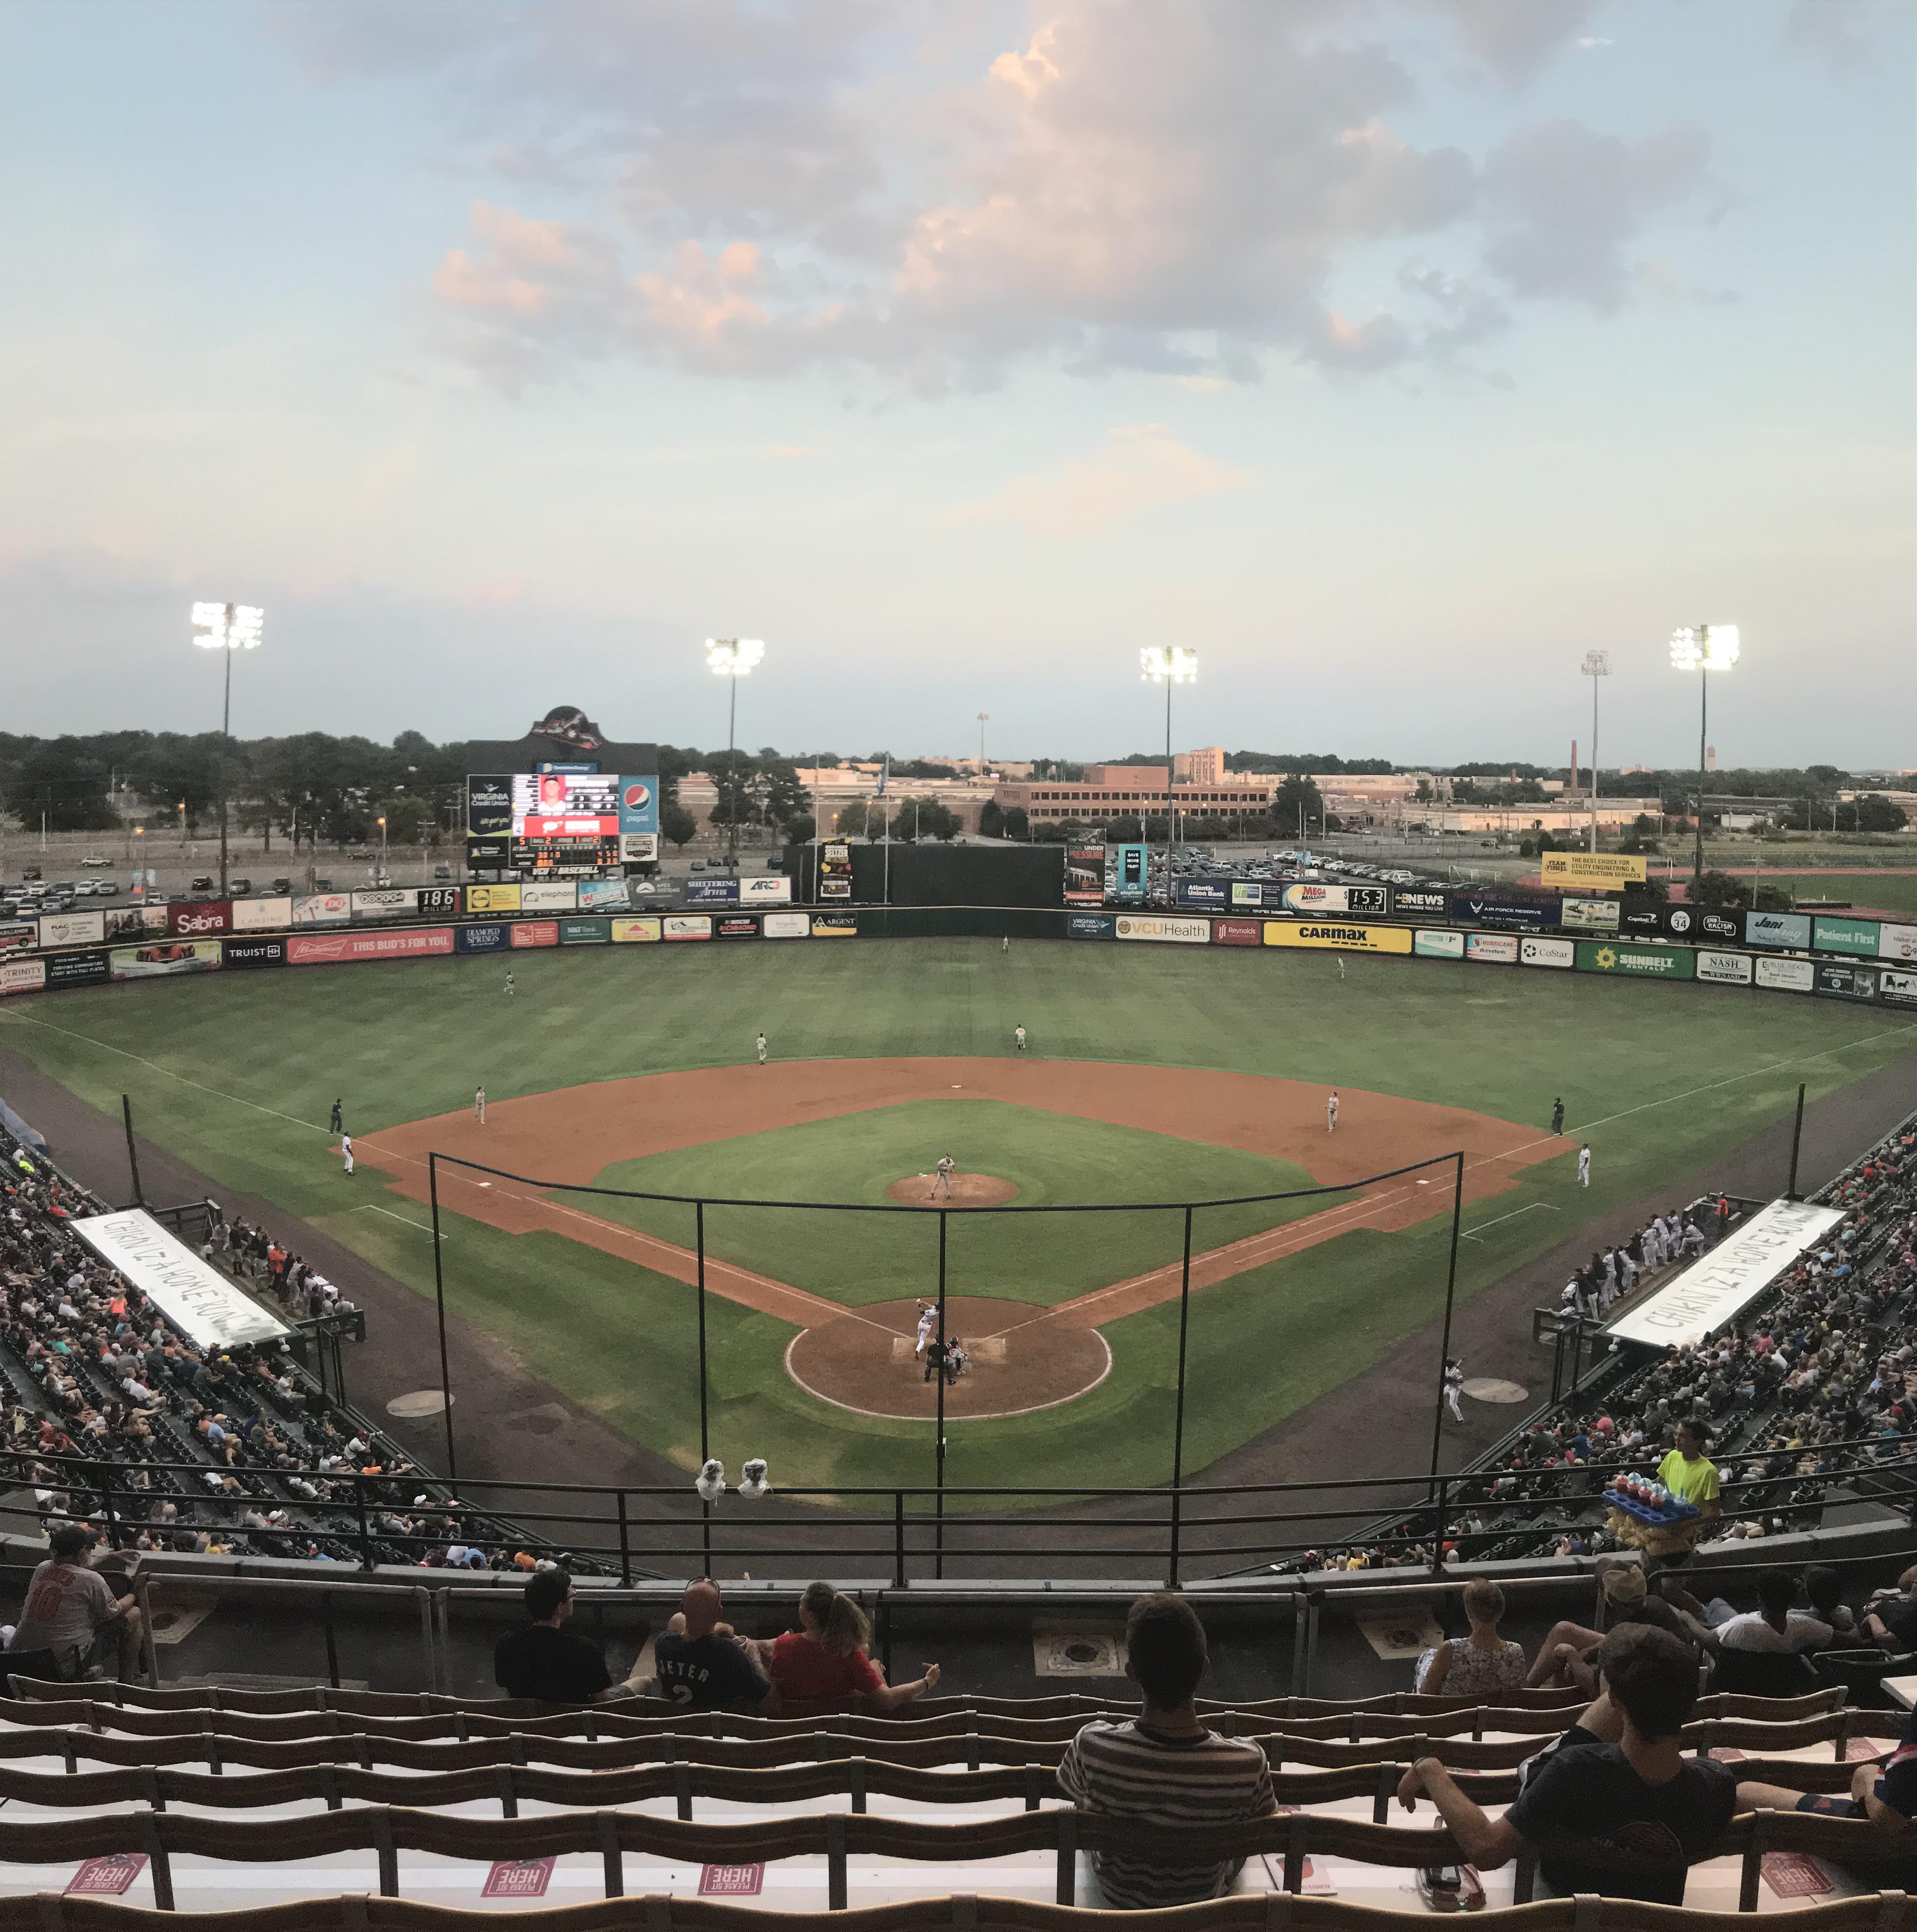
Securing robust auto insurance in the area surrounding The Diamond in Richmond, Virginia, is essential due to the convergence of high-density event traffic, complex urban highway interchanges, and the specific liability risks associated with navigating the Scott’s Addition and Boulevard corridors. Comprehensive coverage protects drivers from the significant financial liabilities inherent in navigating one of the city's most vibrant and congested districts.
Understanding the Landscape: Richmond’s Urban Transit Context
The Diamond, situated prominently along the Arthur Ashe Boulevard corridor in Richmond, serves as a hub for cultural and sporting events. For residents and commuters, this area represents more than just a landmark; it is a high-traffic zone where regional transit arteries like I-95 and I-64 intersect with dense urban surface streets.
When considering auto insurance in this specific geography, drivers must recognize that the risk profile of The Diamond is distinct. The area experiences periodic surges in traffic volume during games and major events, which increases the statistical probability of fender-benders, parking lot accidents, and pedestrian-involved incidents. Because Virginia is an "at-fault" state, the financial burden of these incidents falls squarely on the party responsible. Without adequate coverage, a single collision can lead to long-term financial strain, making local insurance policy selection a matter of critical personal finance management.
Legal Requirements vs. Real-World Protection
In Virginia, the Department of Motor Vehicles (DMV) mandates that all vehicle owners maintain minimum liability insurance coverage. As of 2026, the state-required minimums include $30,000 for bodily injury or death of one person, $60,000 for bodily injury or death of two or more persons, and $20,000 for property damage per accident.
However, relying solely on these state-mandated minimums in a high-density urban environment like Richmond is often insufficient. If you are found at fault in an accident near The Diamond, the costs of property damage to newer vehicles or medical bills for multiple passengers can quickly exceed these limits. Once your insurance policy hits its limit, you become personally liable for the remaining balance. This is why "Full Coverage"—a combination of comprehensive, collision, and liability—is strongly recommended for anyone who frequents the Richmond metropolitan area.
Risks Specific to The Diamond and Surrounding Districts
The area surrounding The Diamond, particularly as it borders the rapidly developing Scott’s Addition neighborhood, presents unique operational risks for motorists:
- High Density of Cyclists and Pedestrians: The area has seen an influx of mixed-use development, leading to increased foot traffic. Accidents involving pedestrians, even at low speeds, can result in high-value medical claims.
- Intersection Complexity: The convergence of Boulevard, Hermitage Road, and the nearby highway off-ramps creates "choke points." These intersections often suffer from visibility issues during evening peak hours, leading to frequent rear-end collisions.
- Theft and Vandalism: Like many high-traffic event venues, vehicles parked in the vicinity of The Diamond are sometimes targeted for opportunistic theft. Comprehensive insurance coverage is the primary mechanism that provides financial protection against non-collision events such as theft, vandalism, and falling objects.
- Uninsured Motorist Risk: Despite state laws, a percentage of drivers on Richmond roads remain uninsured or underinsured. Uninsured Motorist (UM) coverage is a vital component of a Richmond-based policy, ensuring that if you are hit by someone who lacks the financial capacity to pay, your own insurer steps in to cover the damages.
Evaluating Policy Components for Richmond Drivers
When building an insurance portfolio in Richmond, it is helpful to categorize coverage types based on their function. The following table illustrates the standard options available to drivers in 2026 and their relevance to urban driving.
| Coverage Type | Primary Function | Relevance to The Diamond Area |
|---|---|---|
| Bodily Injury Liability | Pays for injuries to others if you cause an accident. | High: Critical for protecting assets against high medical costs. |
| Property Damage Liability | Pays for damage to another person's car or property. | High: Essential for busy, multi-vehicle urban intersections. |
| Comprehensive | Covers theft, fire, vandalism, and weather damage. | Medium-High: Protects against events occurring while parked at venues. |
| Collision | Covers repairs to your car regardless of who is at fault. | High: Protects your vehicle value in heavy traffic incidents. |
| Uninsured Motorist (UM) | Pays for your damages if the other driver is uninsured. | Vital: Essential safety net against high-risk uninsured drivers. |
| Medical Payments (MedPay) | Covers your medical bills regardless of fault. | Important: Provides immediate relief for injury-related costs. |
Strategic Steps for Selecting the Right Policy
To ensure you are adequately protected while navigating the Richmond area, follow this structured approach to evaluating your insurance needs:
- Assess Your Asset Exposure: Consider the total value of your personal assets. If you have significant savings or own property, minimum liability limits may not be enough to shield you from lawsuits in the event of a severe accident.
- Evaluate Your Vehicle’s Current Value: If your vehicle is financed, your lender likely requires comprehensive and collision coverage. If your vehicle is older and fully paid off, you might consider the trade-off between the cost of comprehensive premiums versus the current market value of the vehicle.
- Review the Deductible Structure: A higher deductible—the amount you pay out-of-pocket before insurance kicks in—will lower your monthly premium. However, ensure that you have the liquid savings to cover the deductible if an accident occurs in the middle of a busy commute near The Diamond.
- Check for Local Discounts: Many insurers offer discounts for safety features like anti-theft devices, low annual mileage, or even bundles with renter’s or homeowner’s insurance for Richmond residents.
- Use Official Resources: Verify insurance company ratings through the Virginia State Corporation Commission (SCC) Bureau of Insurance. They provide consumer guides that help you understand the complaint ratios and financial stability of carriers licensed to operate in Virginia.
Common Mistakes to Avoid
Many drivers operating in the Richmond area fall into traps that compromise their long-term financial security. One common error is prioritizing the "cheapest monthly premium" over the "most reliable protection." While low premiums are attractive, they often mask high deductibles or lack of necessary coverage riders.
Another mistake is failing to update your policy after a lifestyle change. If you have moved closer to the city center or changed your daily commute to include more high-traffic routes around The Diamond, your risk profile has likely shifted. It is advisable to review your policy every 12 to 18 months, or whenever your primary driving route changes significantly, to ensure your coverage aligns with your current reality.
Frequently Asked Questions
Why is my insurance premium higher in Richmond than in rural areas? Insurance premiums are based on actuarial data, which includes population density, accident rates, and the cost of property repairs in a specific ZIP code. Richmond, as a major urban hub, has a higher frequency of claims compared to rural Virginia, which is reflected in regional pricing.
Does my insurance cover me if I hit a pedestrian near The Diamond? Yes, if you carry Bodily Injury Liability coverage, your insurance will assist with claims arising from injuries to pedestrians if you are determined to be at fault. This is why having liability limits that exceed the state minimum is highly recommended for urban driving.
What is the difference between Collision and Comprehensive coverage? Collision coverage pays to repair your car if you hit another vehicle or an object, like a light pole. Comprehensive coverage pays for "acts of god" or non-collision events, such as a tree limb falling on your car in a parking lot, vandalism, or theft.
Are there specific laws in Richmond regarding hit-and-runs? Virginia law strictly mandates stopping at the scene of an accident. If you are a victim of a hit-and-run, your Uninsured Motorist (UM) property damage coverage can be vital, provided you file a police report immediately. Always document the scene with photos if it is safe to do so.
How do I prove I have insurance in Virginia? Virginia law requires you to carry your insurance information in your vehicle. If you are stopped by law enforcement or involved in an accident, you must present proof of your policy. Digital insurance cards are generally accepted across the state.
Final Recommendation
To effectively manage your risk when driving in the vicinity of The Diamond, do not settle for the state-mandated minimum liability. Instead, conduct a thorough audit of your assets and daily traffic exposure. Contact a licensed insurance professional to discuss increasing your liability limits and adding Uninsured Motorist coverage. Ensure your chosen carrier has a strong track record of service within Virginia and maintains high financial strength ratings. Protecting yourself is not merely about compliance; it is about ensuring that your financial future remains secure, regardless of the unpredictable nature of urban traffic.

Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
