Comprehensive Overview of Auto Insurance in 37064: Rates, Requirements, and Local Factors
Auto insurance in the 37064 ZIP code—which primarily encompasses Franklin, Tennessee, along with surrounding Williamson County communities—reflects a unique blend of suburban driving patterns, regional traffic dynamics, and Tennessee’s state-mandated liability requirements. Securing the right policy in this area requires navigating mandatory coverage minimums, evaluating optional protections like comprehensive and collision, and understanding how local factors such as vehicle repair costs, weather events, and commuter congestion influence premium pricing across different carriers.
Understanding Tennessee State Auto Insurance Requirements
Every motorist operating a vehicle within the 37064 ZIP code and throughout Tennessee must comply with the state’s mandatory financial responsibility laws. Tennessee operates under a traditional fault-based insurance system, meaning the driver who causes an accident is financially responsible for the resulting injuries and property damage. To satisfy this legal obligation, drivers must carry minimum liability insurance limits set by the state.
As of current state guidelines, the mandatory minimum liability coverage limits in Tennessee are commonly referred to as 25/50/15 coverage:
- $25,000 for bodily injury liability per person injured in an accident you cause.
- $50,000 for total bodily injury liability per accident when multiple people are hurt.
- $15,000 for property damage liability to cover repairs for another person's vehicle or property.
While purchasing only these state minimums satisfies legal driving requirements, insurance professionals strongly recommend higher limits. Medical care and vehicle replacement costs often far exceed these thresholds. If an at-fault accident causes damages exceeding policy limits, the driver remains personally liable for the remaining balance, putting personal assets at risk.
Key Factors Influencing Auto Insurance Rates in 37064
Insurance carriers evaluate a wide array of rating factors when calculating premiums for policyholders in the 37064 ZIP code. While individual driver history remains paramount, geographic and demographic variables specific to Williamson County also play a significant role.
Geographic and Traffic Considerations
The 37064 area spans historic downtown Franklin, rapidly developing commercial corridors along Interstate 65, and winding rural roads stretching toward Leiper's Fork. Insurers analyze historical claims data for specific ZIP codes to determine local risk:
- Commuter Traffic: Proximity to Nashville via I-65 and State Route 96 means many 37064 residents commute daily, increasing exposure to high-speed highway collisions and bumper-to-bumper rush hour congestion.
- Weather Risks: Middle Tennessee experiences severe weather, including thunderstorms, high winds, hail, and occasional winter ice storms. Comprehensive coverage is essential for protecting vehicles against falling tree limbs, hail damage, and weather-related road hazards.
- Vehicle Theft and Vandalism: While Williamson County generally records lower crime rates compared to major metropolitan centers, vehicle break-ins in commercial parking areas or residential neighborhoods still occur, influencing comprehensive insurance pricing.
Personal Risk Profiles
Beyond location, insurers look at specific characteristics of the primary driver and household:
- Driving Record: Clean driving records without speeding tickets, at-fault accidents, or driving under the influence (DUI) citations yield the lowest rates. Violations typically remain on a motor vehicle report for three to five years.
- Credit History: In Tennessee, insurers are permitted to use credit-based insurance scores to help determine risk. Studies consistently show a statistical correlation between responsible credit management and lower insurance claims frequency.
- Vehicle Make and Model: The cost to repair or replace a vehicle directly affects premium pricing. Luxury vehicles, sports cars, and cars equipped with expensive advanced driver-assistance systems (ADAS) generally cost more to insure than standard sedans or economy crossovers.
- Annual Mileage: Drivers who commute long distances or log high annual mileage face a higher statistical exposure to accidents compared to those who work from home or drive short distances.
Types of Auto Insurance Coverage Available
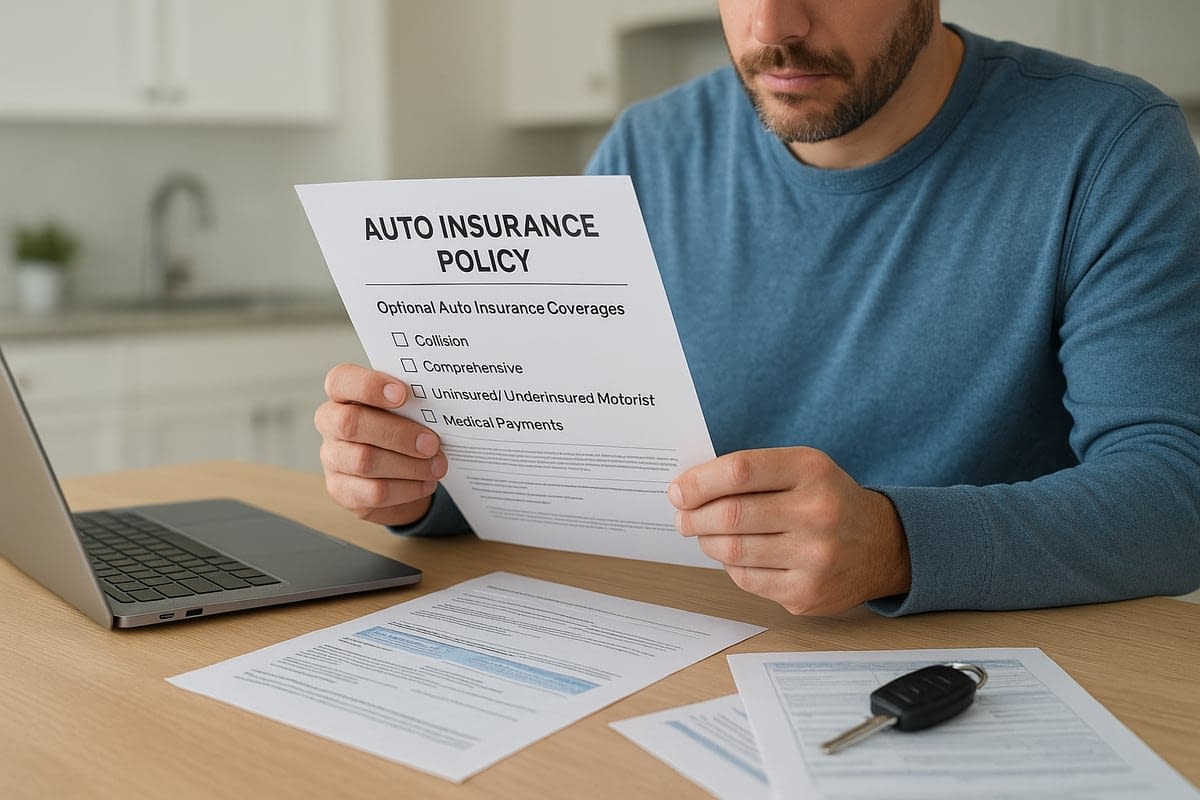
Navigating an insurance quote requires understanding the various coverage components available to 37064 policyholders. Policies are generally built by combining mandatory liability protection with optional physical damage and supplemental coverages.
| Coverage Type | Description | Primary Purpose |
|---|---|---|
| Bodily Injury Liability | Pays for injuries to other drivers, passengers, or pedestrians when you are at fault. | Covers medical bills, legal fees, and lost wages of injured third parties. |
| Property Damage Liability | Pays for damage you cause to another person’s vehicle, fence, building, or property. | Prevents out-of-pocket costs for repairing others' property after an accident. |
| Collision Coverage | Pays to repair or replace your vehicle if it collides with another car or object, like a tree or guardrail. | Essential for financed or leased cars; covers single-car and multi-car crashes. |
| Comprehensive Coverage | Protects your vehicle from non-collision events such as theft, fire, vandalism, animal strikes, and hail. | Safeguards against environmental hazards and property crimes common in Middle Tennessee. |
| Uninsured/Underinsured Motorist | Covers your medical expenses and vehicle repairs if you are hit by a driver with no insurance or insufficient limits. | Protects against the financial risk of uninsured motorists on public roadways. |
| Medical Payments (MedPay) | Pays medical and funeral expenses for you and your passengers, regardless of fault. | Covers immediate healthcare expenses without waiting for fault determination. |
Comparing Coverage Options and Deductibles
Choosing the right balance between monthly premium costs and out-of-pocket financial exposure requires careful consideration of personal savings and risk tolerance.
Deductibles Explained
For physical damage coverages like collision and comprehensive, the deductible is the amount the policyholder pays out of pocket before the insurance company begins paying for repairs. Selecting a higher deductible—such as $1,000 instead of $500—typically lowers the monthly premium. However, policyholders must ensure they have adequate emergency savings to cover that deductible if an unexpected claim arises.
Optional Endorsements for Enhanced Protection
Drivers in 37064 often add specialized endorsements to standard policies for complete peace of mind:
- Roadside Assistance: Provides towing, flat tire changes, jump-starts, and lockout services.
- Rental Car Reimbursement: Covers the cost of a rental vehicle while your car is in the repair shop following a covered claim.
- Gap Insurance: Bridges the gap between the actual cash value of a totaled vehicle and the remaining balance on an auto loan or lease.
- New Car Replacement: Pays to buy a brand-new car of the same make and model if a brand-new vehicle is totaled within its first model year or specified mileage limit.
Strategies for Lowering Auto Insurance Premiums in 37064
Auto insurance rates fluctuate based on broader economic trends, inflation in vehicle repair costs, and rising medical expenses. However, policyholders have several practical avenues to secure discounts and optimize their insurance spending:
- Bundle Policies: Many insurance carriers offer substantial multi-policy discounts (often 10% to 25%) when combining auto insurance with homeowners, renters, or umbrella insurance policies.
- Maintain Good Credit: Regularly monitoring credit reports and correcting errors can positively impact credit-based insurance scores over time.
- Utilize Telematics Programs: Many top insurers offer app-based or plug-in device programs that track driving habits—such as speed, braking smoothness, and phone usage. Safe drivers frequently earn immediate enrollment discounts and ongoing renewal savings.
- Raise Deductibles Wisely: Increasing physical damage deductibles from $250 to $500 or $1,000 can reduce premium expenses, provided the driver sets aside cash reserves to cover the higher out-of-pocket threshold.
- Ask for Special Discounts: Inquire about discounts for defensive driving course completion, paperless billing, automatic monthly payments, low annual mileage, and affiliation with specific professional organizations or alumni groups.
- Shop and Compare Annually: Insurance markets shift regularly. Comparing quotes from multiple licensed carriers every few years ensures that rates remain competitive relative to current market conditions.
Common Mistakes to Avoid When Buying Auto Insurance
Selecting inadequate coverage or falling for common misconceptions can leave motorists severely exposed financially. Avoiding these pitfalls ensures robust protection:
- Buying Only State Minimums: Relying solely on Tennessee's 25/50/15 limits leaves drivers vulnerable to catastrophic financial loss in serious multi-vehicle accidents.
- Failing to Update Policy Information: Forgetting to update your address, add a newly licensed teen driver, or report a change in vehicle use can result in denied claims or policy cancellation.
- Ignoring Uninsured Motorist Coverage: Operating a vehicle without uninsured/underinsured motorist protection leaves you financially unprotected if struck by a hit-and-run driver or an uninsured motorist.
- Over-Insuring Older Vehicles: Continuing to pay for comprehensive and collision coverage on an older car whose market value is lower than the annual premium plus deductible may not make financial sense.
Frequently Asked Questions About Auto Insurance in 37064
Is auto insurance mandatory in the 37064 ZIP code?
Yes. Because 37064 is located in Tennessee, all vehicle owners and operators must carry minimum liability insurance matching or exceeding state-mandated limits of 25/50/15 to legally drive on public roads.
Does my credit score affect my auto insurance rate in Franklin, Tennessee?
Yes. Tennessee law permits insurance companies to use credit-based insurance scores as a rating factor. Maintaining a strong credit history generally correlates with lower insurance premiums.
What should I do immediately after a car accident in Williamson County?
Ensure everyone is safe and move to a safe location if possible. Call 911 to report the accident and request police assistance. Exchange contact, insurance, and vehicle information with the other driver. Document the scene with photos if safe to do so, and notify your insurance carrier as soon as possible to file a claim.
Are rates higher in Franklin compared to rural parts of Tennessee?
Generally, suburban and urbanizing areas experience higher traffic density, greater accident frequencies, and higher vehicle repair costs than rural counties. Consequently, premiums in ZIP codes like 37064 may reflect moderately higher risk factors than remote rural areas in Tennessee.
How often should I review my auto insurance policy?
It is wise to review your auto insurance policy annually or whenever major life events occur, such as buying a new home, adding a teenage driver, changing jobs, or paying off a vehicle loan.
Next Steps for Securing Your Policy
To secure optimal auto insurance coverage in 37064, begin by auditing your current policy limits, deductibles, and endorsements against your personal financial situation. Gather your vehicle identification numbers (VINs), driver's license details, and driving history records. Request customized quotes from at least three reputable insurance carriers licensed in Tennessee. Compare not just the bottom-line premium price, but also coverage limits, customer service reputations, and claims handling processes. Selecting a well-balanced policy ensures confidence and financial security on every drive through Franklin and beyond.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
