Understanding Life Insurance Qualification Test Questions: A Comprehensive Guide to Passing the Licensing Exam

Understanding the life insurance qualification test questions requires a dual focus on mastering core insurance concepts and deciphering the specific linguistic patterns used by exam providers. These exams evaluate your ability to identify policy types, explain legal provisions, and apply ethical standards to complex consumer scenarios through rigorous multiple-choice testing.
To become a licensed life insurance producer in 2026, candidates must navigate a standardized examination process that serves as a regulatory gatekeeper. While the specific number of questions and passing scores vary slightly by jurisdiction, the underlying structure of the test questions remains remarkably consistent. This guide breaks down the technical composition of these questions, the subjects they prioritize, and the analytical skills required to select the correct answer under pressure.
The Structural Framework of Licensing Exam Questions
The life insurance qualification test is not merely a memory test; it is a psychometric evaluation designed to ensure a minimum level of competency. Most testing providers, such as Pearson VUE or Prometric, utilize a format that categorizes questions based on cognitive level. Understanding these levels is the first step in deconstructing the test.
Knowledge and Recall Questions
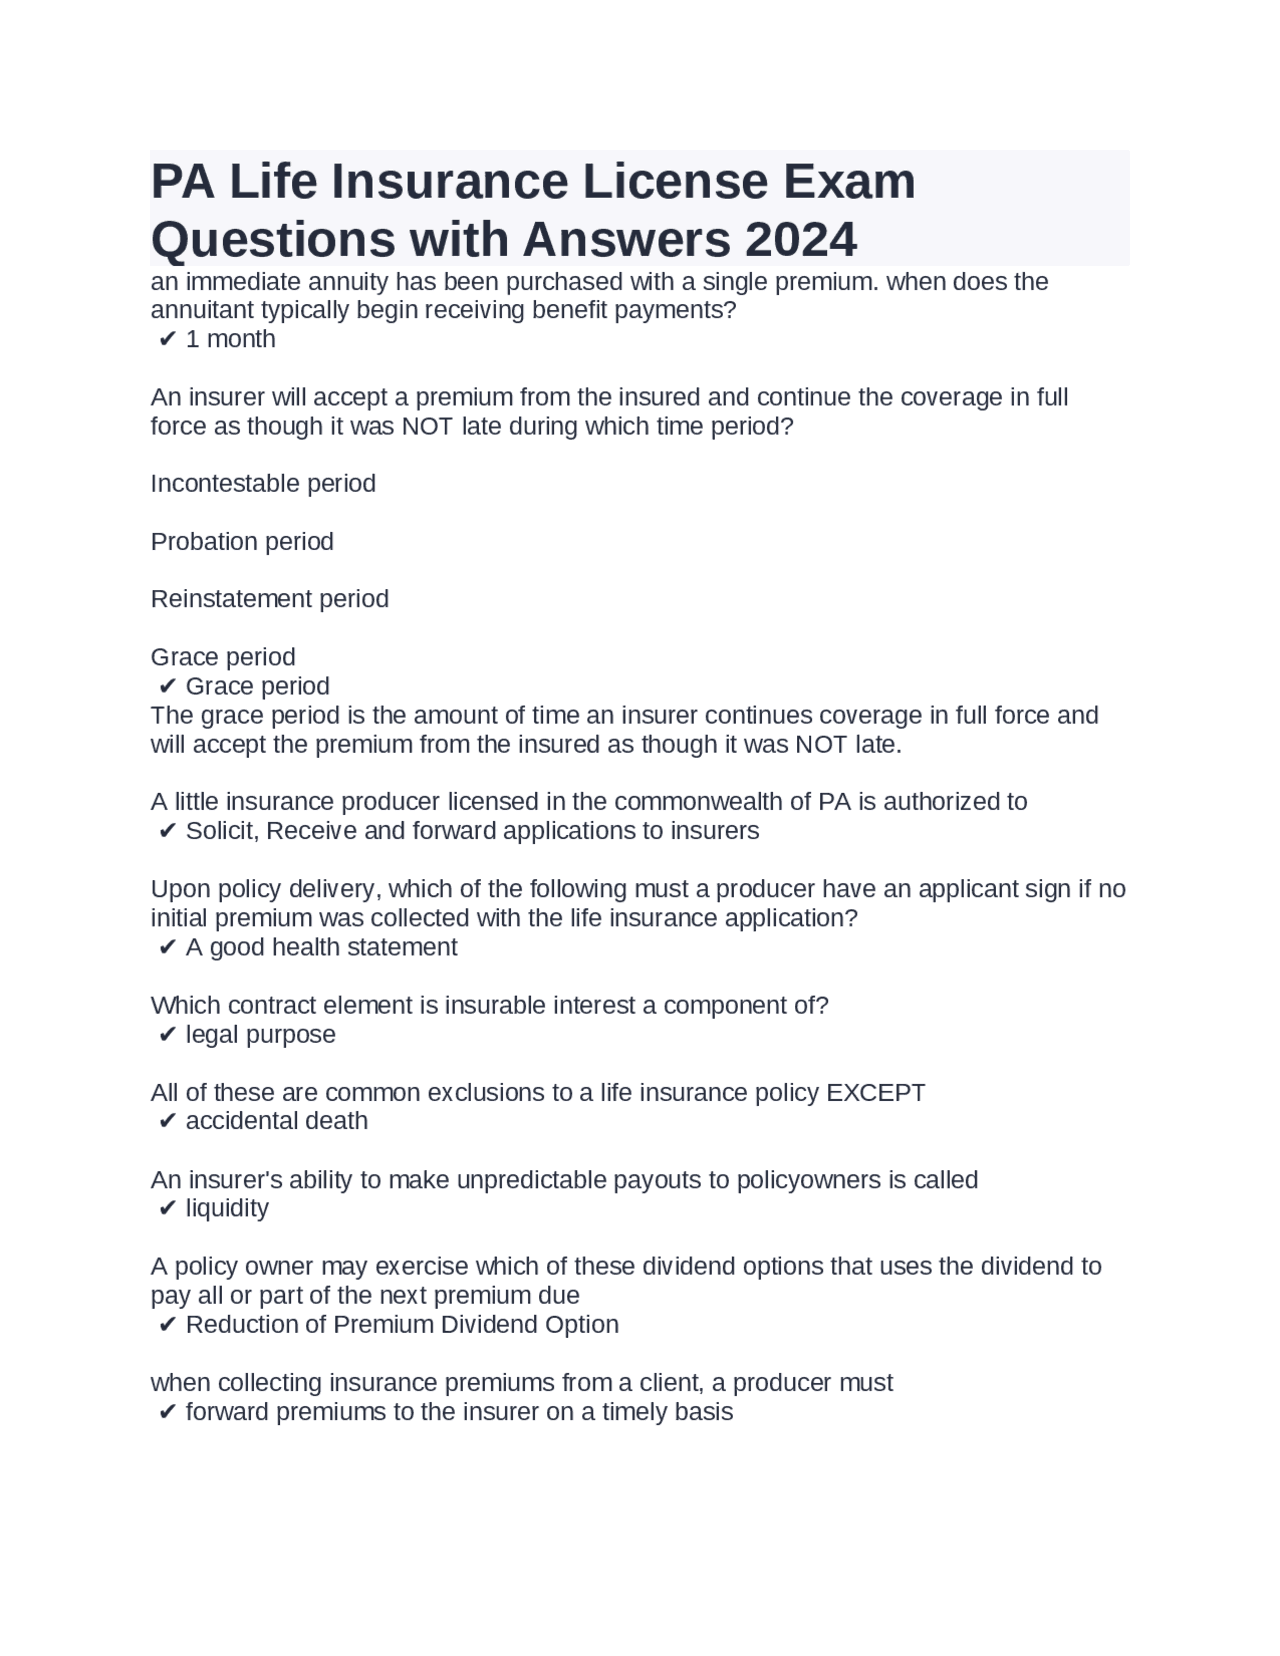
These are the most straightforward questions on the exam. They ask for definitions, specific timeframes, or factual data. For example, a question might ask for the length of the standard "Free Look" period in a specific state. There is no room for interpretation here; you either know the fact or you do not. In 2026, these questions remain the "low-hanging fruit" of the exam, but they often utilize industry jargon to confuse the unprepared.
Application and Analysis Questions
The majority of the exam consists of application-based questions. These present a "mini-scenario" involving a hypothetical client. You might be told that "John, aged 45, wants a policy that provides permanent protection but allows him to vary his premium payments." You must then identify that John is looking for a Universal Life policy. These questions test your ability to take a theoretical concept and apply it to a practical situation.
Evaluative Questions
These are often considered the most difficult. They require you to compare two or more concepts or identify the "most correct" or "best" action for an agent to take. These questions often focus on ethics, suitability, and the legal obligations of a fiduciary.
Core Subject Matter Breakdown
To understand the questions, you must understand the categories from which they are drawn. Most state exams are split into two sections: a national "General Knowledge" portion and a "State-Specific" portion.
Life Insurance Product Types
Questions in this category focus on the mechanics of different policies. You will face questions comparing Term Life Insurance (pure protection) against Permanent Life Insurance (protection plus cash value). You must understand the nuances of:
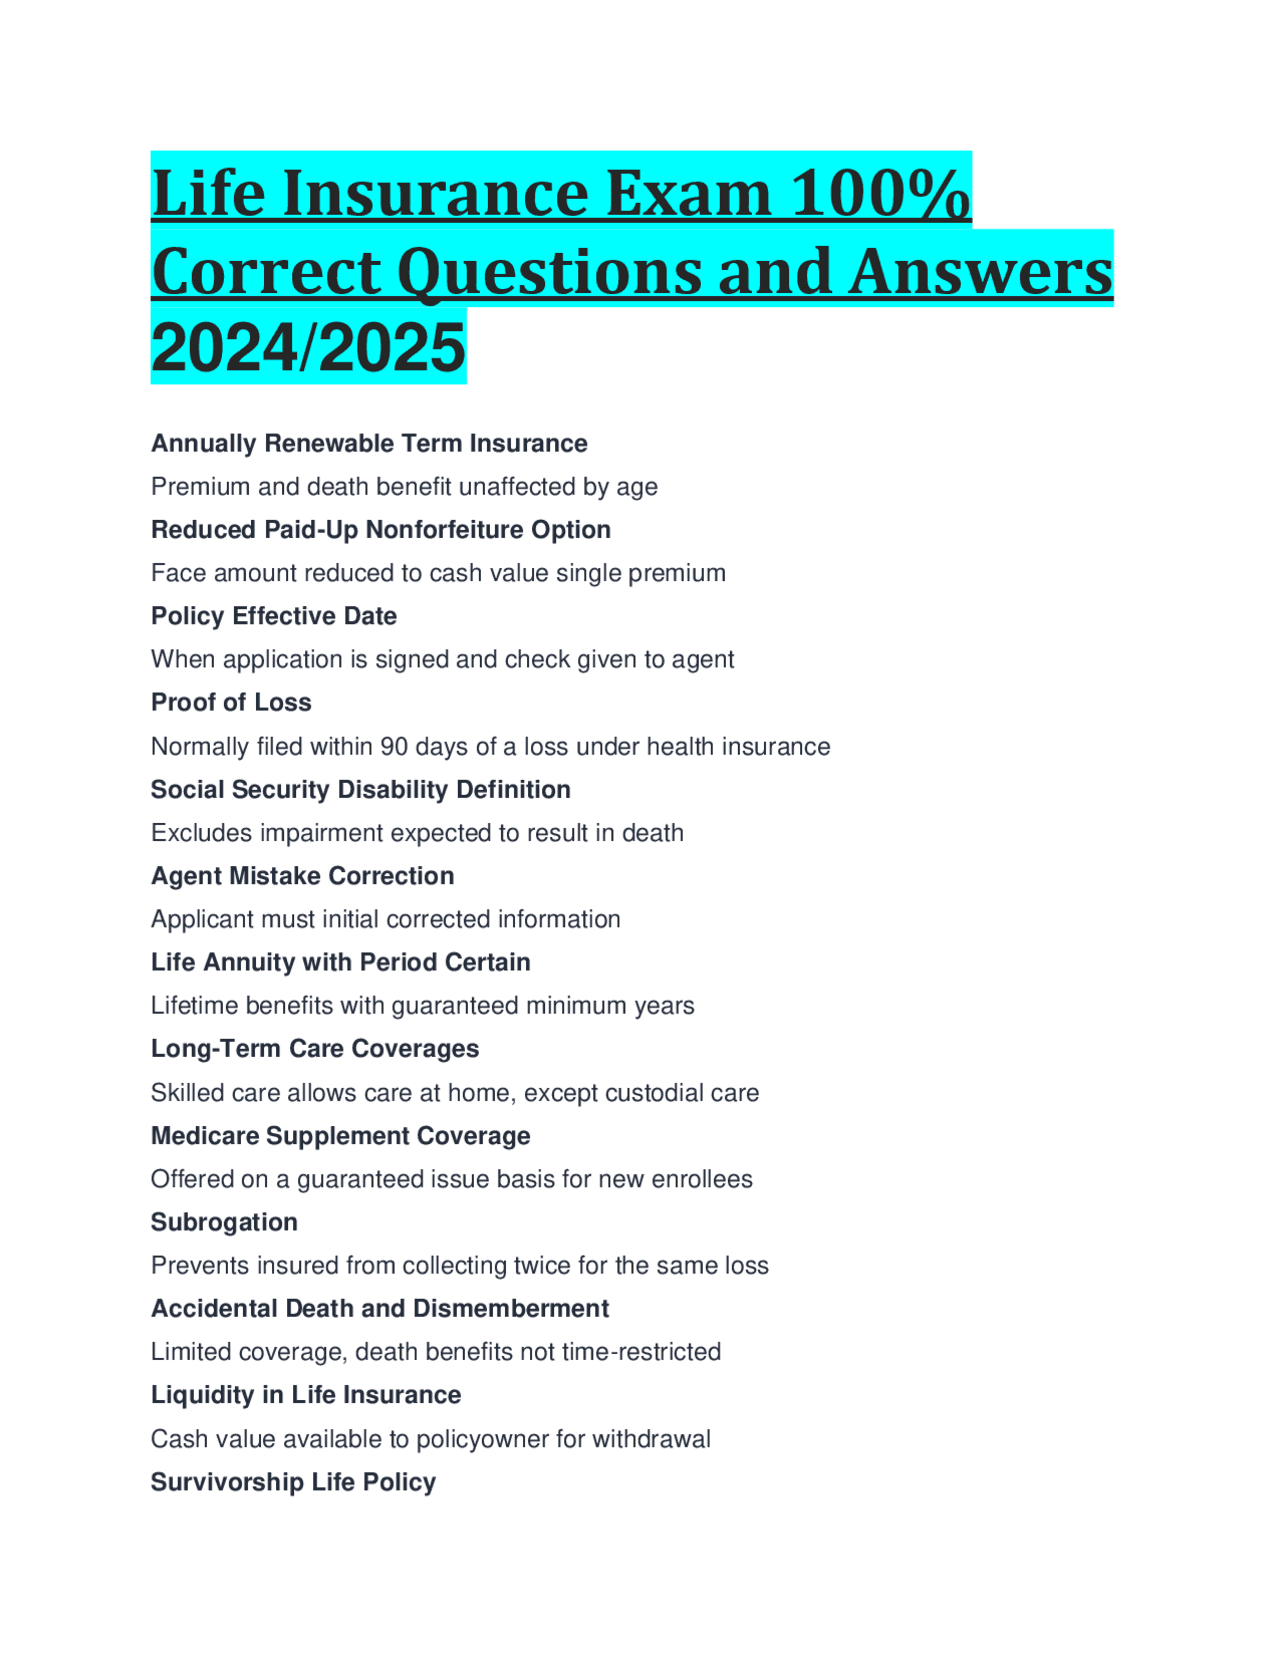
- Whole Life Insurance: Fixed premiums, guaranteed death benefits, and cash value accumulation.
- Universal Life Insurance: Flexibility in premiums and face amounts, with unbundled components.
- Variable Life Insurance: The inclusion of underlying investment sub-accounts, necessitating a securities license in many instances.
Policy Provisions, Options, and Riders
This is where many candidates struggle because the terminology is highly specific. Questions will test your knowledge of the "Incontestability Clause," "Grace Periods," and "Reinstatement" rules. You will also need to understand "Riders"—the add-ons that customize a policy—such as the Waiver of Premium or the Accidental Death Benefit. Expect questions that ask what happens to a policy's death benefit if a loan is outstanding at the time of the insured's death.
Taxes, Retirement, and Employee Benefits
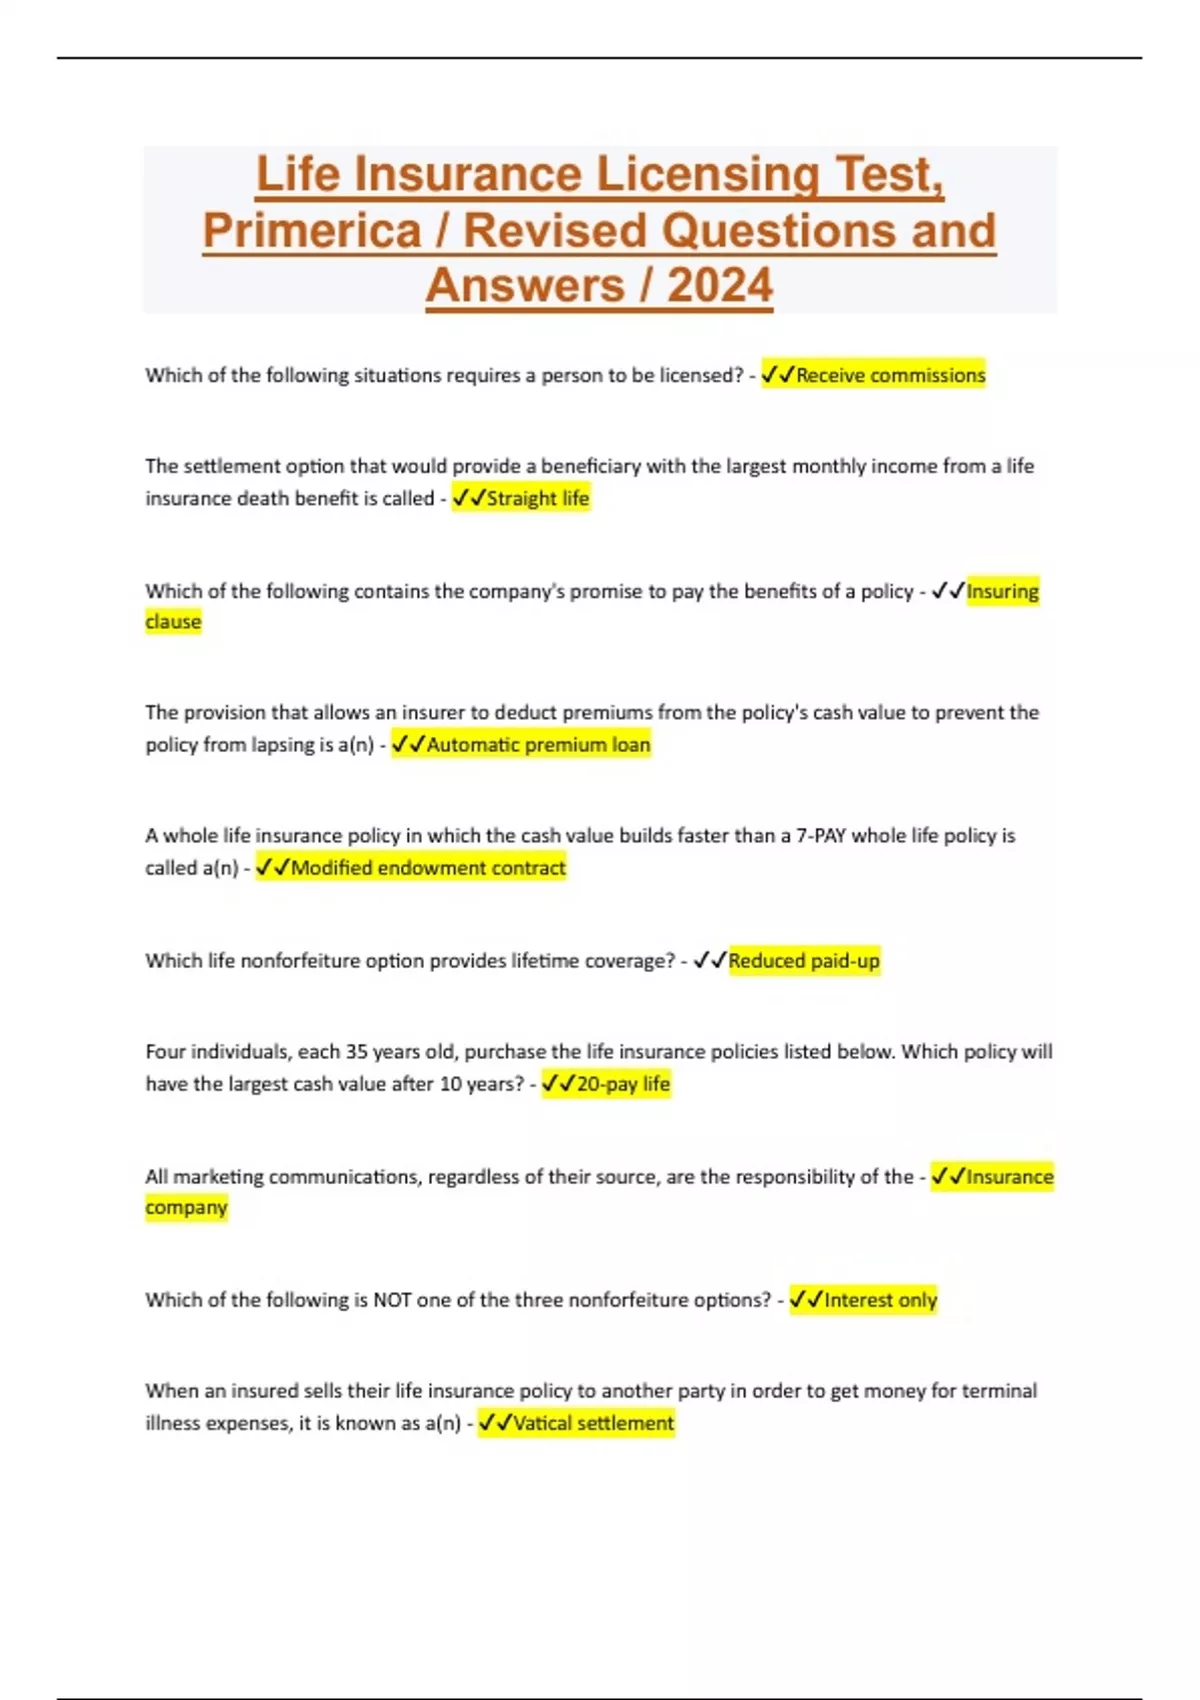
The 2026 exam environment places a high premium on understanding the tax implications of life insurance. Questions frequently cover the tax-free nature of death benefits, the tax-deferred growth of cash values, and the "Modified Endowment Contract" (MEC) rules. If a policy fails the "7-Pay Test," it becomes a MEC, losing many tax advantages; the exam will test your ability to recognize when this transition occurs.

Deciphering Question Logic and "Distractors"
A "distractor" is a multiple-choice option that looks correct but is technically flawed. Understanding how test-writers create these distractors is essential for high performance.
The "Except" and "Not" Format
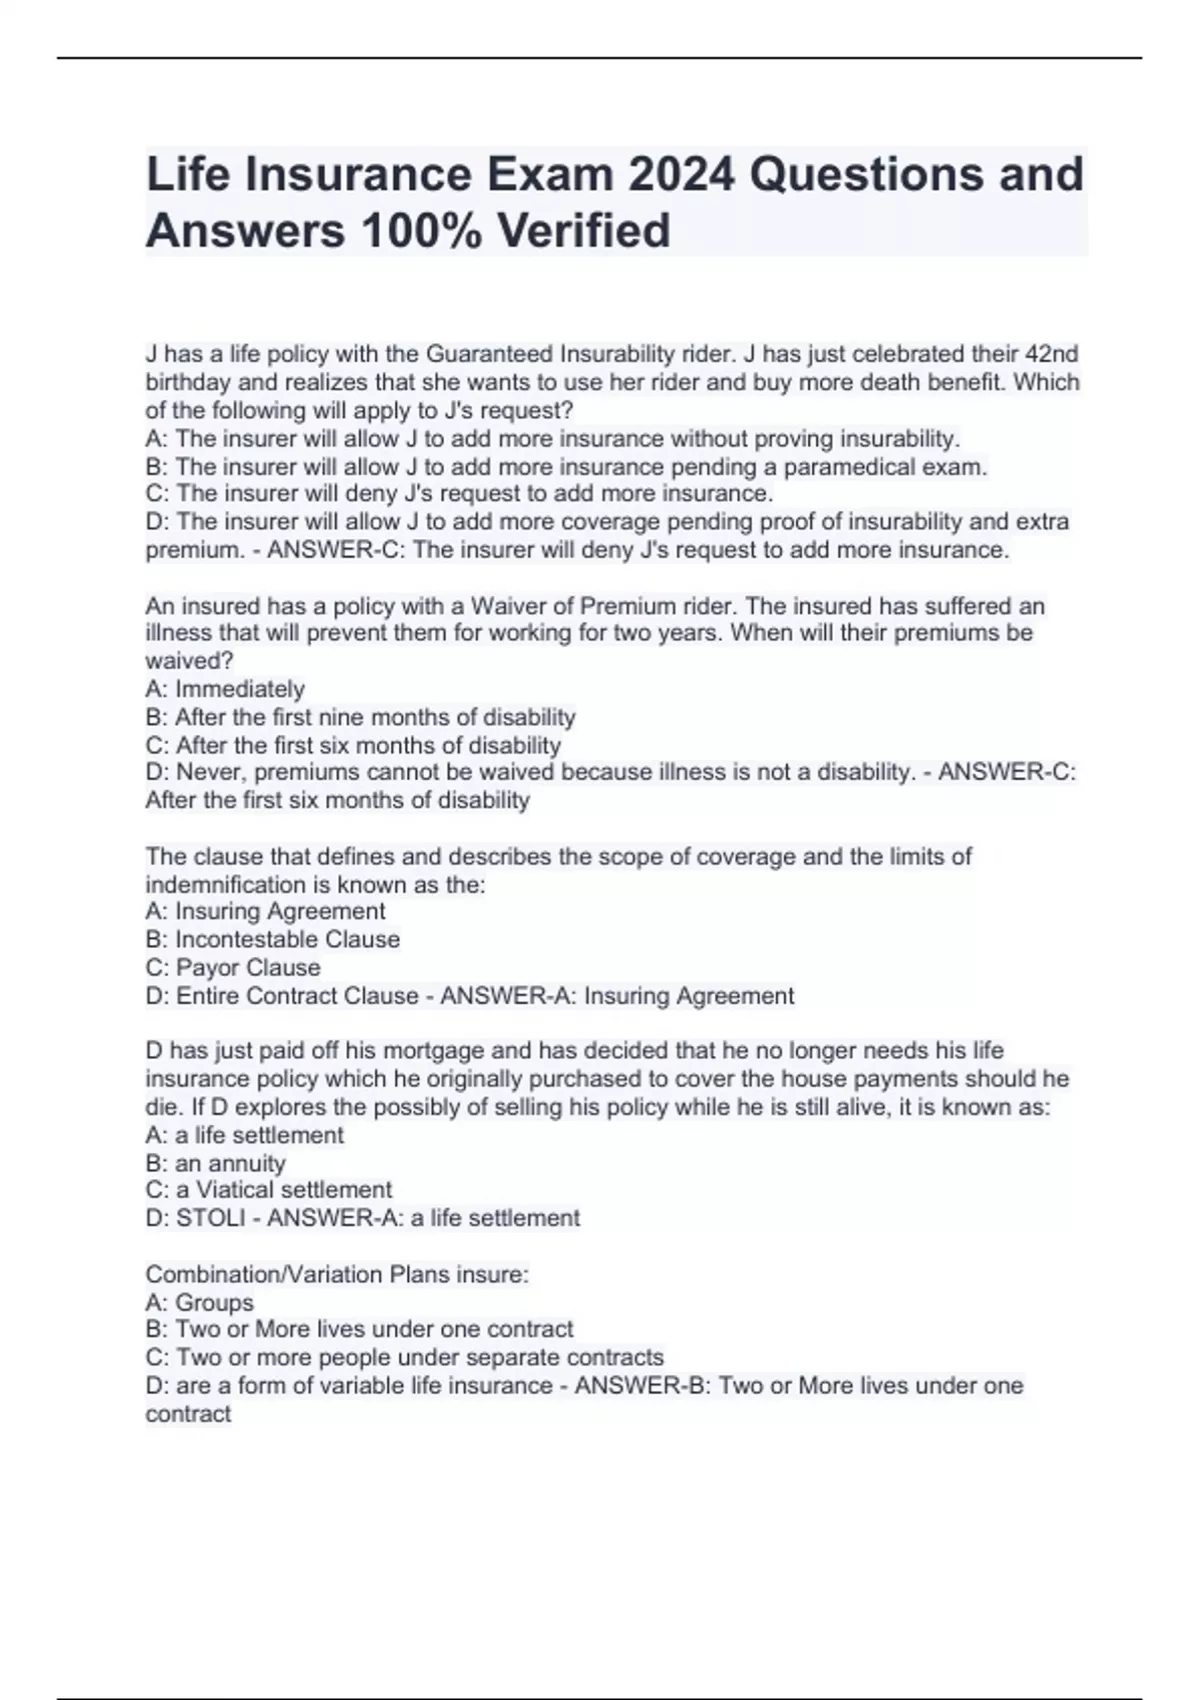
One of the most common pitfalls is the negative stem. A question might ask: "All of the following are characteristics of a Whole Life policy EXCEPT..." Candidates who read too quickly often pick the first correct characteristic they see (Option A), failing to realize the question is asking for the one incorrect characteristic.
The "Half-Right" Answer
Some distractors are partially true. They might correctly describe a concept but apply it to the wrong policy type. For example, a distractor might describe the flexibility of Universal Life in a question specifically about Whole Life.
Double Negatives and Complex Phrasing
Exam providers often use complex sentence structures to test a candidate's attention to detail. Phrases like "Which of the following is not an uncommon provision..." require a moment of mental translation to understand that the question is actually asking: "Which of the following is a common provision?"
The Impact of State-Specific Regulations
While the national portion covers general insurance principles, the state-specific section focuses on the laws passed by your local legislature. In 2026, these questions often center on:
- Licensing Requirements: Who needs a license, how to renew it, and what constitutes a "controlled business."
- Unfair Trade Practices: Detailed questions on rebating (offering incentives), twisting (misrepresenting a policy to induce a switch), and defamation of other insurers.
- The Guaranty Association: How the state protects policyholders if an insurance company becomes insolvent. Importantly, most states forbid agents from using the existence of the Guaranty Association as a selling point.
| Exam Category | Typical Weighting | Difficulty Level | Primary Focus |
|---|---|---|---|
| Product Types | 25% | Medium | Comparing Term, Whole, and Universal policies. |
| Policy Provisions | 30% | High | Legal clauses, riders, and ownership rights. |
| Taxation & Rules | 15% | High | MEC rules, 1035 exchanges, and death benefit taxes. |
| State Regulations | 20% | Medium | Local laws, licensing, and ethics. |
| Marketing Practices | 10% | Low | Advertising rules and forbidden sales tactics. |
Practical Strategies for Navigating the Questions
To succeed, you must move beyond passive reading. Active engagement with the material is the only way to internalize the logic of the test.
- Read the Full Question Twice: Before looking at the answers, identify exactly what the "stem" (the question itself) is asking. Identify key words like "only," "never," "always," or "except."
- Use the Process of Elimination: Even if you are unsure of the correct answer, you can often identify two distractors that are obviously wrong. This increases your probability of success from 25% to 50% immediately.
- Practice with Mock Exams: The 2026 testing environment relies heavily on computer-based interfaces. Use practice tests that mimic the actual software you will use at the testing center. This reduces anxiety and helps you manage your time—usually about 1 to 1.5 minutes per question.
- The "Umbrella" Concept: Sometimes, one answer choice is broader than the others and "covers" them. If you see two options that are both technically true, look for a third option that encompasses both.
Frequently Asked Questions
What is the passing score for the life insurance exam in 2026?
Most states require a scaled score of 70 to pass. It is important to note that a "scaled" score is not necessarily the same as a raw percentage. Testing providers use scaling to account for the varying difficulty levels of different versions of the exam, ensuring that a candidate who takes a "harder" version isn't unfairly penalized.
Are the questions the same in every state?
No. While the national portion covering general insurance principles (like how Whole Life works) is very similar across the country, the state-specific section is unique to each jurisdiction. For example, California’s rules on senior insurance marketing may differ significantly from those in New York or Texas.
Can I skip a difficult question and come back to it?
Yes, most testing centers (Prometric and Pearson VUE) allow you to "flag" a question. It is often a good strategy to skip a question that is causing frustration and return to it later. Often, a subsequent question might provide a clue that helps you answer the one you skipped.
Is the life insurance exam harder than the health insurance exam?
Many candidates find the life insurance exam slightly more intuitive because the product structures (Term vs. Permanent) are very distinct. However, the taxation and retirement planning portions of the life exam can be technically denser than the topics found in the health insurance exam.
How many questions are on the test?
On average, the exam consists of 100 to 150 questions. You will typically be given between 2 and 3 hours to complete it. Some exams also include "pre-test" questions—experimental questions that do not count toward your score but are used by the provider to gather data for future tests. You will not know which questions are pre-test items, so treat every question as if it counts.
Final Recommendation for Candidates
Success in understanding the life insurance qualification test questions depends on your ability to think like a regulator. The test is designed to protect the public by ensuring you won't misrepresent products or violate tax laws. As you study, constantly ask yourself: "How could this concept be turned into a 'which of the following' scenario?"
By focusing on the intent of the laws and the mechanics of the policies rather than just memorizing definitions, you will develop the analytical framework necessary to see through the "distractors" and identify the correct path. Prioritize taking at least three full-length practice exams before your test date to build your "testing stamina" and ensure you are comfortable with the 2026 regulatory environment.
Image Gallery
Select an image to open it in a new tab.



Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
