
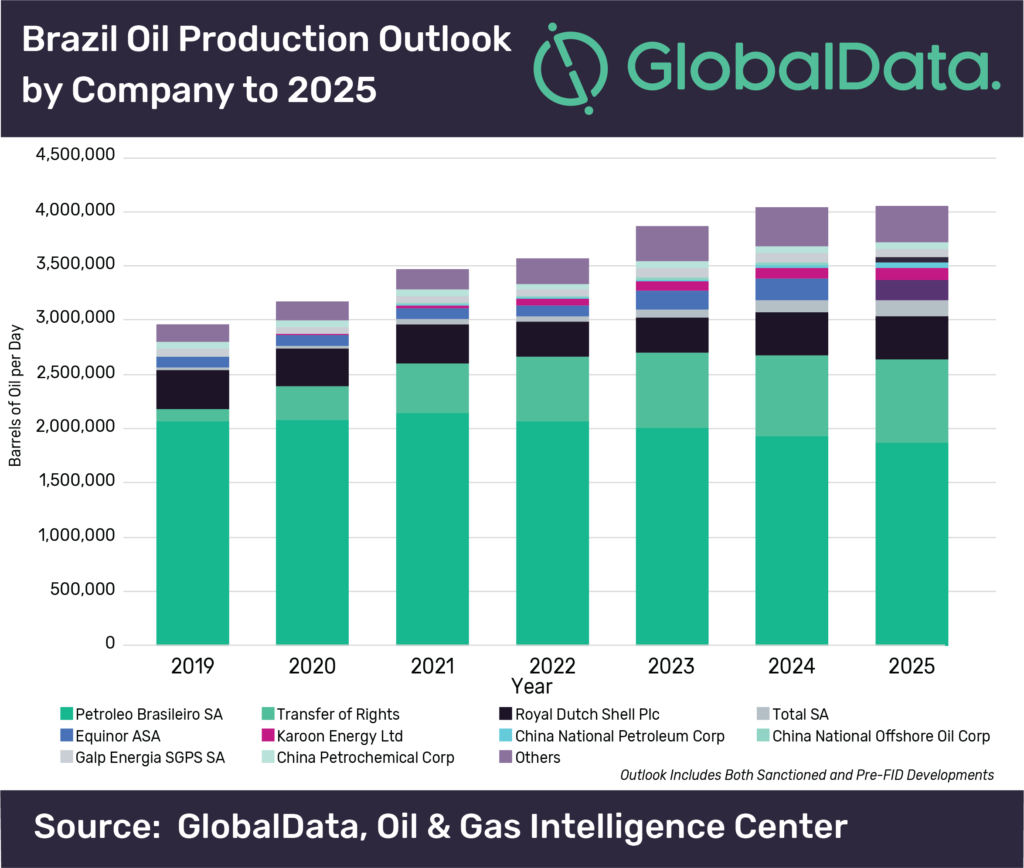
Brazil’s oil sector is dominated by the state-controlled Petrobras, which operates alongside global majors like Shell, Equinor, and TotalEnergies. The market has diversified through the rise of independent producers such as Prio and Brava Energia. In 2026, the industry focuses on maximizing pre-salt efficiency while exploring controversial new frontiers in the Equatorial Margin.
The Brazilian oil and gas landscape is a unique blend of state-driven industrial policy and aggressive private-sector participation. As the largest oil producer in Latin America and a top-ten global producer, Brazil represents a critical geography for energy security and deepwater technological innovation. Understanding the companies operating within this territory requires a look at the historical dominance of the national champion, the strategic shifts of international oil companies (IOCs), and the rapid consolidation of independent local players.
The Dominant Force: Petrobras (Petróleo Brasileiro S.A.)
Petrobras remains the undisputed leader of the Brazilian energy sector. Founded in 1953, it transitioned from a state monopoly to a publicly traded corporation in the late 1990s, though the Brazilian government retains majority voting rights. By 2026, Petrobras has solidified its position as a global leader in ultra-deepwater exploration, primarily through its mastery of the "Pre-salt" (Pré-sal) layers—vast oil reserves trapped beneath thick layers of salt in the Santos and Campos basins.
The company’s 2024–2028 Strategic Plan, which currently guides its 2026 operations, emphasizes a "double resilience" strategy: producing low-cost, low-carbon oil. Petrobras focuses heavily on the Buzios and Mero fields, which are among the most productive in the world. For investors and partners, Petrobras is not just a competitor but a primary operator of the consortia that manage the nation's most lucrative blocks.
The company’s role in 2026 also involves navigating the political complexities of fuel pricing and domestic refining capacity. While it has divested from several mature onshore and shallow-water fields, it retains a near-monopoly on refining, though this has been a point of constant regulatory and political debate regarding market competition.
International Oil Companies (IOCs) in the Brazilian Market
International majors have shifted from being mere financial partners to active operators in Brazil. The regulatory changes introduced between 2016 and 2019, which removed the requirement for Petrobras to be the sole operator in all pre-salt blocks, opened the door for deep involvement by foreign entities.
Shell Brasil
Shell is the largest foreign producer in Brazil. Its presence is characterized by significant equity stakes in some of the country’s most prolific fields, including Tupi and Sapinhoá. In 2026, Shell continues to integrate its Brazilian oil production with its global "Powering Progress" strategy, using the high cash flows from the pre-salt to fund transitions into renewable energy projects within the country, including offshore wind and solar initiatives.
Equinor
The Norwegian state-controlled giant, Equinor, has become a pivotal player in the Brazilian offshore segment. Its flagship project, the Bacalhau field in the Santos Basin, is a cornerstone of its international portfolio. By 2026, Bacalhau is a primary contributor to Equinor’s production volumes outside of the Norwegian Continental Shelf. The company is also noted for bringing advanced digital twin technology and carbon reduction techniques from the North Sea to the Brazilian deepwater.
TotalEnergies
The French major maintains a diversified portfolio in Brazil, with a strong focus on the Mero field (part of the Libra block) and the Iara cluster. TotalEnergies has also been a vocal proponent of exploring the Equatorial Margin, a frontier region near the mouth of the Amazon River that is often compared to the massive discoveries made in neighboring Guyana.
The Rise of Independent Brazilian Companies (Junior Majors)
One of the most significant shifts in the Brazilian market over the last decade has been the emergence of "junior" oil companies. These are typically local entities that have purchased "mature" or "brownfield" assets that Petrobras divested to focus on the high-yield pre-salt.
- Prio (formerly PetroRio): Prio has mastered the art of field revitalization. By acquiring older fields like Frade and Albacora Leste, the company employs aggressive cost-cutting and secondary recovery techniques to extend the economic life of assets. In 2026, Prio is recognized for its operational efficiency and its ability to maintain a very low "lifting cost" (the cost of bringing one barrel of oil to the surface).
- Brava Energia: Formed from the significant merger between 3R Petroleum and Enauta (completed in 2024), Brava Energia has emerged by 2026 as a major consolidated force. This entity manages a complex portfolio of onshore and offshore assets, bridging the gap between small independent operators and the massive international majors.
- PetroRecôncavo: This company specializes in onshore production, particularly in the Recôncavo and Potiguar basins. They have been instrumental in revitalizing Brazil’s interior oil production, proving that there is still significant value in legacy terrestrial fields through modern fracking and enhanced oil recovery (EOR) technologies.
Regulatory Framework and the Role of the ANP
All companies operating in Brazil must navigate the regulations set by the Agência Nacional do Petróleo, Gás Natural e Biocombustíveis (ANP). The ANP is responsible for organizing bid rounds, regulating production, and ensuring that companies adhere to "local content" requirements—rules that mandate a certain percentage of equipment and services must be sourced from Brazilian suppliers.
In 2026, the regulatory environment is increasingly focused on the transition to a low-carbon economy. The ANP has integrated stricter environmental reporting and decommissioning standards. Companies are now legally required to have robust plans for the eventual plugging and abandonment of wells, a process that has become a multi-billion dollar industry in its own right as older fields in the Campos Basin reach the end of their life cycles.
Comparison of Major Oil Players in Brazil (2026)
| Company | Primary Type | Key Asset / Region | Strategic Focus |
|---|---|---|---|
| Petrobras | State-Controlled | Buzios (Santos Basin) | Deepwater/Pre-salt dominance |
| Shell | International Major | Tupi (Santos Basin) | Partnerships and Gas-to-Power |
| Equinor | International Major | Bacalhau (Santos Basin) | Technology transfer and efficiency |
| Prio | Local Independent | Frade / Albacora Leste | Mature field revitalization |
| Brava Energia | Local Independent | Atlanta / Papa Terra | Asset consolidation and growth |
| TotalEnergies | International Major | Mero (Santos Basin) | Frontier exploration/Equatorial Margin |
The Equatorial Margin: The 2026 Frontier
As of 2026, the most significant point of contention and potential growth is the Equatorial Margin. Stretching from the state of Amapá to Rio Grande do Norte, this region is geologically similar to the Guyana-Suriname Basin, where ExxonMobil discovered billions of barrels of oil.
However, exploration here is fraught with environmental challenges. The proximity to the Amazon reef system and the mouth of the Amazon River has led to a protracted licensing battle between oil companies (led by Petrobras) and environmental agencies like IBAMA. In 2026, the industry is closely watching the first exploratory wells in this region, as the results will determine whether Brazil can maintain its status as a top exporter for the next 30 years or if production will begin a slow decline in the 2030s.
Operational Challenges and Infrastructure
Operating in Brazil is not without technical and logistical hurdles. The pre-salt reserves are located 200 to 300 kilometers offshore, beneath 2,000 meters of water and another 5,000 meters of rock and salt.
- FPSO Deployment: Brazil is the world's largest market for Floating Production Storage and Offloading (FPSO) units. These massive vessels are essentially floating refineries. Managing the supply chain for these units is a primary task for companies like SBM Offshore and Modec, who lease these vessels to the oil producers.
- Logistics: The "long-distance" nature of the Santos Basin requires complex helicopter logistics for crew changes and specialized support vessels (PSVs) for equipment delivery.
- Tax Complexity: Brazil’s tax system is notoriously complex. The "REPETRO" tax regime, which provides incentives for the import of oil and gas equipment, is a critical component of any company’s financial planning in the region.
FAQ: Oil Operations in Brazil
Which company produces the most oil in Brazil?
Petrobras is the largest producer, responsible for roughly 70-75% of the country's total output. While international partners share the production in many fields, Petrobras remains the lead operator in the majority of the highest-producing assets.
Is Brazil's oil industry open to foreign investment?
Yes, the industry is highly open. Foreign companies can participate in concession rounds or production-sharing agreements. Since 2016, there has been a concerted effort to attract international capital to share the immense costs of developing the pre-salt reserves.
What is the "Pre-salt" (Pré-sal)?
The pre-salt refers to geological formations found under a layer of salt on the ocean floor. In Brazil, these reserves are found in the Atlantic Ocean. The oil found here is generally of high quality (light oil), which fetches a higher price on the global market and is cheaper to refine.
Are there opportunities for small oil companies in Brazil?
Opportunities for smaller companies primarily exist in the onshore basins (like Recôncavo and Potiguar) and in mature offshore fields. While the pre-salt requires multi-billion dollar investments, smaller "independent" companies thrive by increasing the efficiency of fields that are no longer profitable for giants like Petrobras.
How does the Brazilian government benefit from these companies?
The government benefits through royalties, special participation fees, and taxes. In production-sharing contracts used for the pre-salt, a portion of the "profit oil" is also given directly to the state-owned company PPSA (Pré-Sal Petróleo S.A.), which manages the government’s share.
What are the environmental concerns for oil companies in Brazil?
The primary concerns are the protection of marine biodiversity in the Santos/Campos basins and the preservation of the delicate ecosystem in the Equatorial Margin. Companies in 2026 are under intense pressure to implement Carbon Capture and Storage (CCS) and to minimize flaring (the burning of excess natural gas).
Strategic Recommendations for 2026
For stakeholders looking to engage with oil companies in Brazil, the following actions are recommended:
- Focus on the Supply Chain: The demand for FPSOs and subsea equipment remains at an all-time high. Companies that provide specialized maintenance and digital monitoring for deepwater assets are in high demand.
- Monitor Environmental Licensing: The fate of the Equatorial Margin is the single most important variable for the industry’s long-term growth. Any progress in environmental licensing by IBAMA should be viewed as a major market signal.
- Partner with Independents: For service providers, the rising independent players (Prio, Brava) offer faster decision-making cycles than Petrobras and are often more willing to adopt innovative, cost-saving technologies.
Brazil remains a powerhouse of the global oil industry. While the global energy transition is underway, the low-cost and high-productivity nature of Brazilian pre-salt oil ensures that these companies will remain central to the world’s energy mix throughout 2026 and well into the next decade.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
