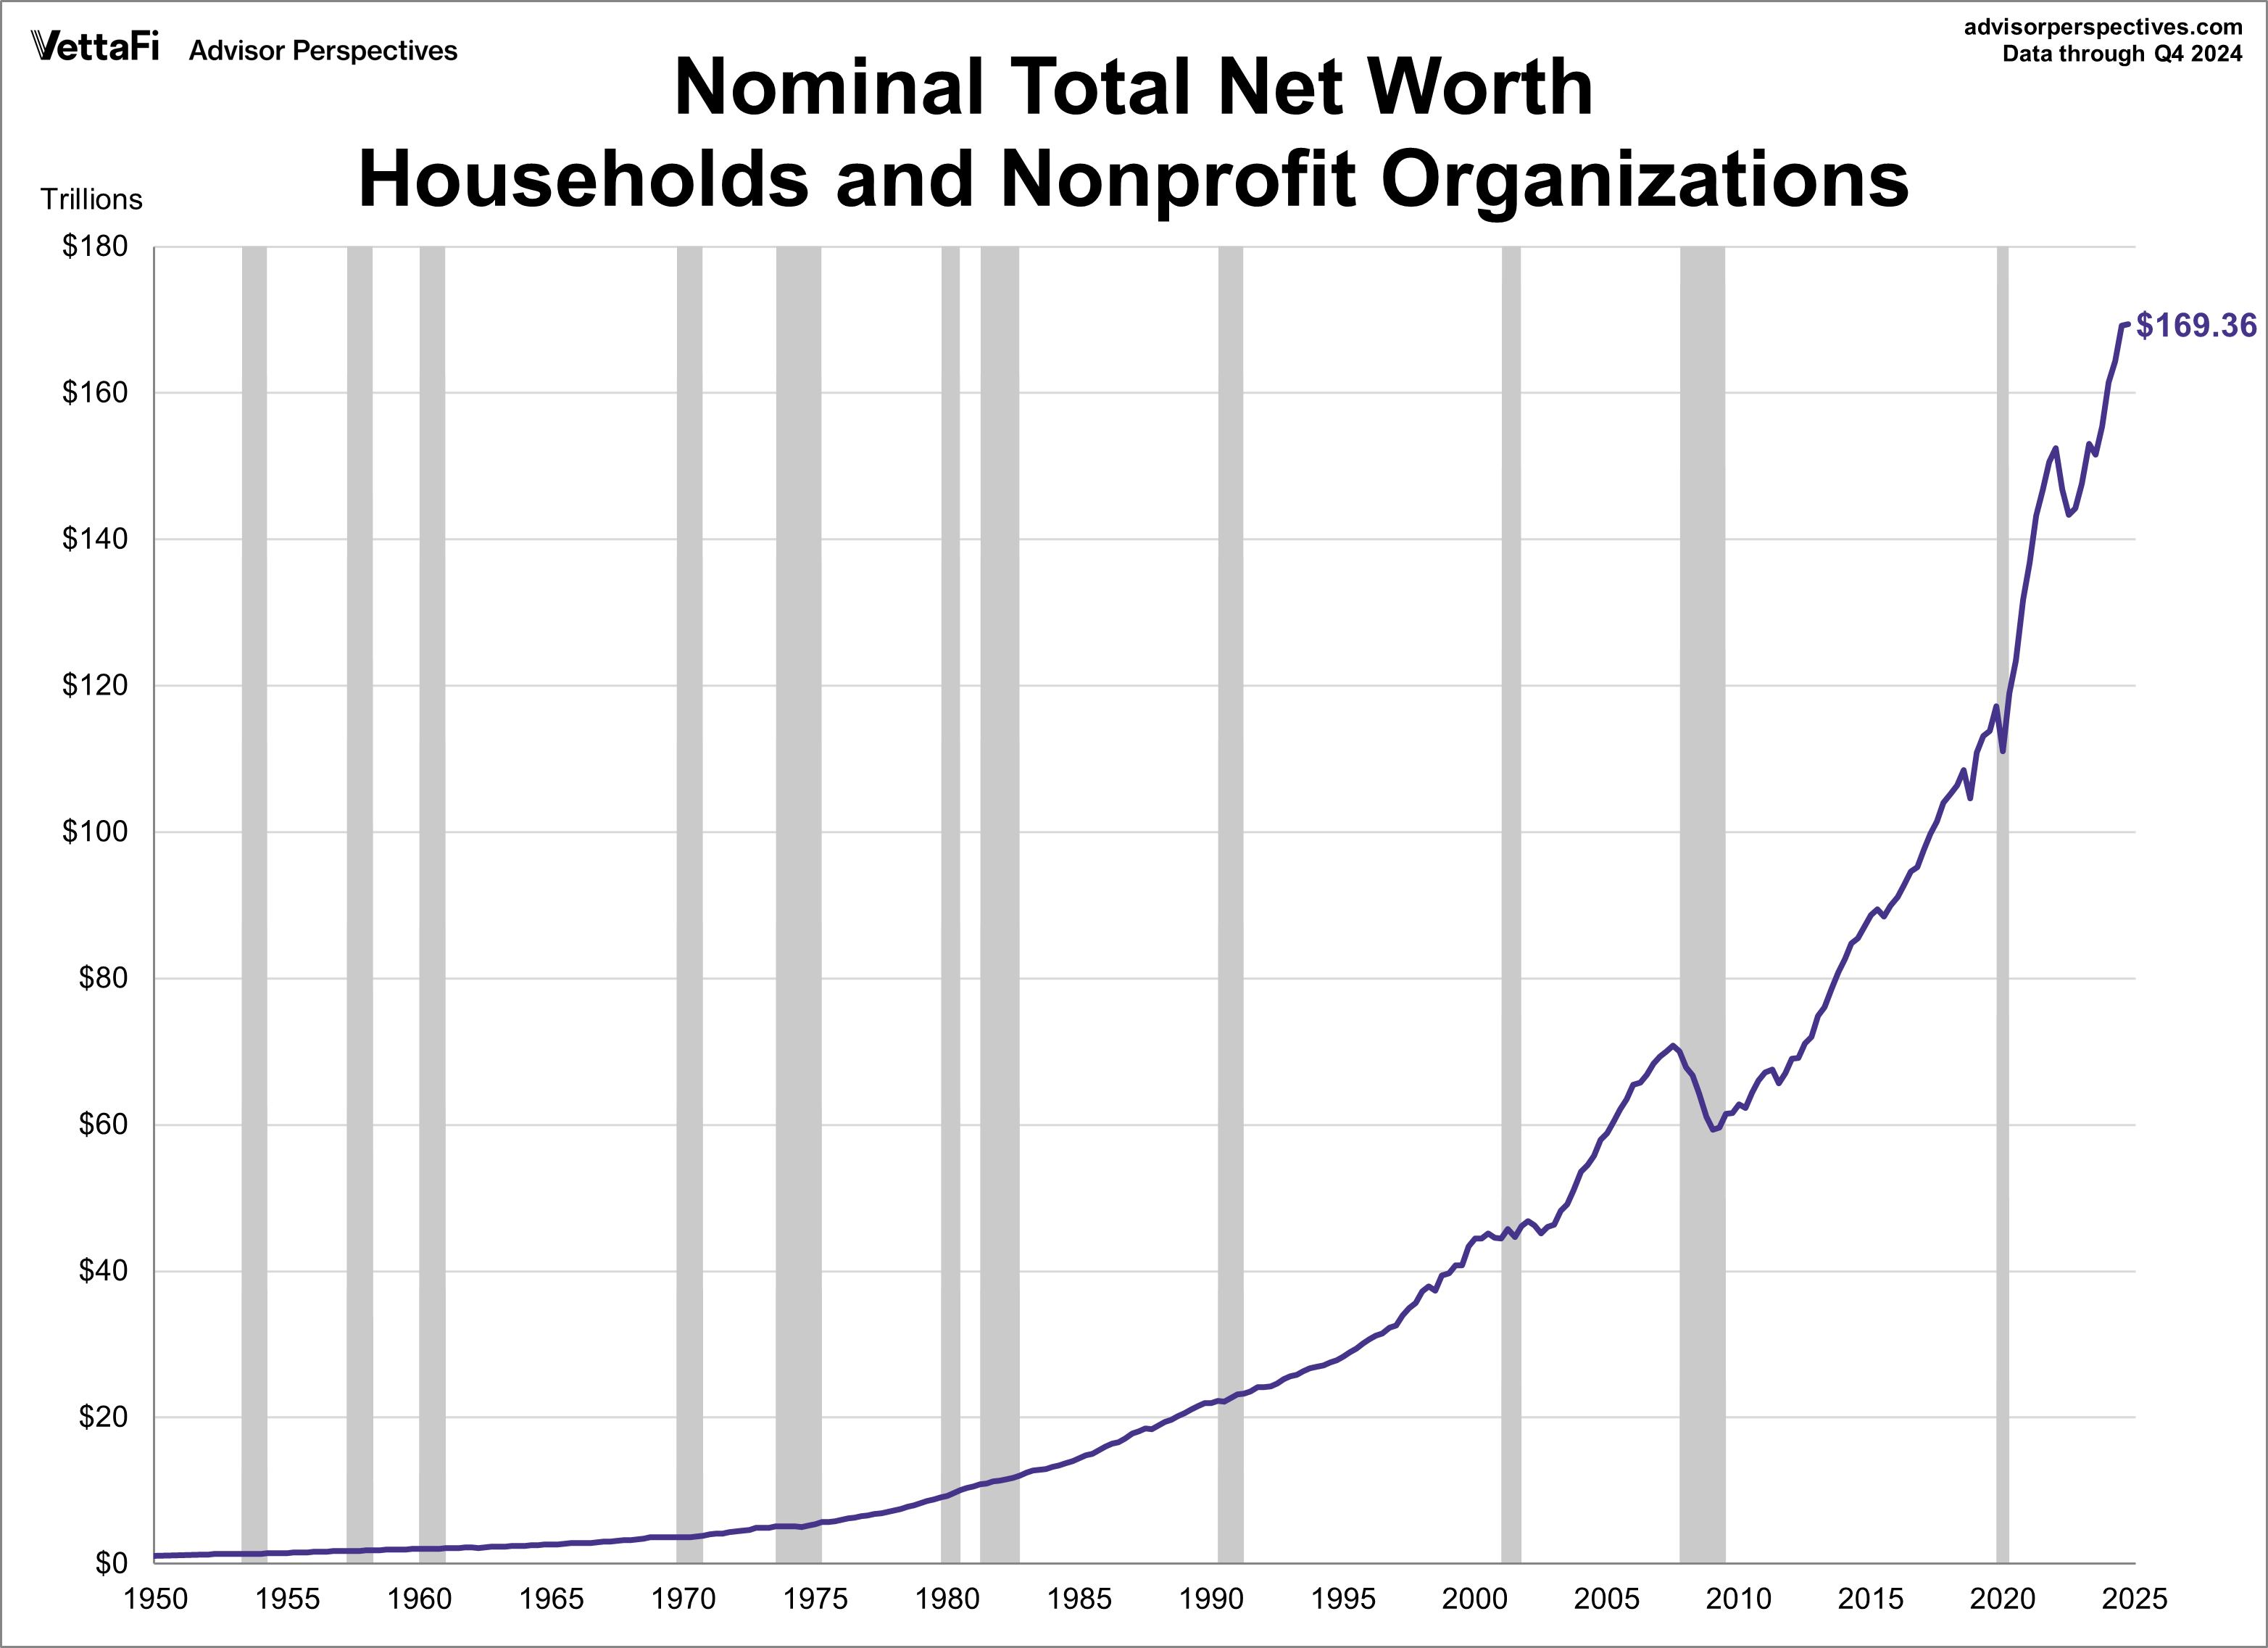
A net worth of $7,150,000 is exceptionally good, placing an individual or household in the top 1.5% to 2% of wealth holders in the United States and the top 0.1% globally in 2026. This "High Net Worth" (HNW) status provides significant financial independence, allowing for a luxurious lifestyle and perpetual wealth growth.
To understand whether $7,150,000 is "good" for your specific situation, one must analyze the figure through the lenses of purchasing power, age-based benchmarks, and the shifting economic landscape of 2026. While the term "7 150" could theoretically refer to a net worth of $7,150, in the context of financial planning and net worth inquiries, it almost universally refers to the $7.15 million milestone. For those at the $7,150 level, the focus remains on foundational liquidity and debt management, whereas the $7.15 million level shifts the focus to wealth preservation and legacy.
Defining the 7.15 Million Milestone in 2026
In 2026, the definition of wealth has been influenced by several years of post-pandemic inflation and shifting market dynamics. A net worth of $7,150,000 is no longer just "comfortable"; it is a tier of wealth that transcends the traditional "millionaire next door" category. According to data trends from the Federal Reserve's Survey of Consumer Finances, a household with over $7 million in net assets possesses more than ten times the median American household wealth.
Net worth is calculated by subtracting all liabilities (mortgages, student loans, credit card debt, business loans) from total assets (real estate equity, brokerage accounts, retirement funds, cash, and business valuations). At the $7.15 million mark, most individuals find that their primary residence represents less than 20% of their total wealth, with the remainder invested in income-producing assets.
The Real-World Purchasing Power
In 2026, $7.15 million provides a level of security that shields a household from most economic downturns. If invested conservatively with a 4% annual withdrawal rate—a standard benchmark in retirement planning—this capital generates approximately $286,000 in annual pre-tax income without touching the principal. This is more than three times the projected median household income for 2026, allowing for a high-end lifestyle even in expensive metropolitan areas like New York City, San Francisco, or London.
Statistical Benchmarking: Where Do You Stand?
Comparing your net worth to the broader population helps quantify the "goodness" of the number. Wealth is relative, and in 2026, the gap between the middle class and the high-net-worth tier has widened.
Percentile Rankings
Statistically, $7.15 million is an elite figure. In the United States, it comfortably clears the threshold for "Accredited Investor" status and approaches the "Qualified Purchaser" threshold (usually $5 million in investable assets).
- Top 1%: Generally starts around $13 million in 2026.
- Top 2%: $7.15 million sits firmly within this bracket.
- Top 5%: Starts around $3.5 million.
- Top 10%: Starts around $2.1 million.
Age-Based Expectations
A "good" net worth is also highly dependent on age. A 30-year-old with $7.15 million is an extreme outlier, likely having benefited from a massive business exit, professional sports career, or significant inheritance. Conversely, for a 70-year-old, this amount represents a lifetime of disciplined saving and compounding, ensuring a legacy for heirs.
| Age Bracket | Median Net Worth (2026 Est.) | $7.15M Status |
|---|---|---|
| 25–34 | $35,000 | Elite (Top 0.1%) |
| 35–44 | $120,000 | Top 1% |
| 45–54 | $210,000 | Top 1.5% |
| 55–64 | $260,000 | Top 2% |
| 65–74 | $310,000 | Top 2.5% |

The Impact of the 2026 Tax Landscape
The year 2026 is a critical pivot point for high-net-worth individuals due to the sunsetting of key provisions in the Tax Cuts and Jobs Act (TCJA). Unless new legislation is passed, the federal estate tax exemption—which hovered around $13 million per person in 2025—is scheduled to be cut roughly in half.
For someone with a $7.15 million net worth, this change is significant. In 2024 and 2025, this individual would be well under the estate tax threshold. However, in 2026, a $7.15 million estate may suddenly face federal estate taxes if the exemption drops to the projected $6-7 million range (adjusted for inflation). This makes "good" wealth management in 2026 more about tax efficiency and estate planning than simple accumulation.
Strategic Considerations for 2026:
- Lifetime Gifting: Utilizing the remaining high exemption amounts before the sunset.
- Irrevocable Trusts: Moving assets out of the taxable estate to protect them from the lower 2026 thresholds.
- Step-up in Basis: Evaluating whether to hold assets until death to reset the capital gains tax or to gift them now.
Lifestyle and Financial Independence (FIRE)
For many, the question "Is it good?" really means "Can I stop working?" At $7,150,000, the answer for most people is a definitive "Yes." This falls into the "Fat FIRE" (Financial Independence, Retire Early) category, which describes a retirement that does not require a "frugal" lifestyle.
The 4% Rule at $7.15M
The 4% rule suggests you can safely withdraw 4% of your portfolio in the first year of retirement and adjust that amount for inflation every year thereafter for at least 30 years.
- Portfolio Value: $7,150,000
- Annual Withdrawal (4%): $286,000
- Monthly Budget: $23,833
This monthly budget allows for premium healthcare, luxury travel, private education for children, and high-end housing. However, "Sequence of Returns Risk" remains a factor. If the market performs poorly in the first few years of retirement, a $286,000 withdrawal might deplete the portfolio faster than anticipated. Wealth managers in 2026 often suggest a more flexible withdrawal rate (3.3% to 3.5%) to ensure the capital lasts 40+ years.
Asset Allocation for a $7.15 Million Portfolio
To maintain and grow this level of wealth, diversification is mandatory. A typical HNW individual in 2026 does not keep $7 million in a savings account. Instead, the capital is spread across various sectors to balance growth and protection.
1. Equities (40–60%)
Low-cost index funds remain the backbone of most portfolios, but at this level, individuals often diversify into:
- Dividend Aristocrats: Stocks that consistently increase dividends, providing a "paycheck."
- International Markets: Emerging markets to hedge against a domestic slowdown.
- Sector-Specific ETFs: Focusing on AI, biotech, and renewable energy sectors which have matured significantly by 2026.
2. Real Estate (15–25%)
Beyond a primary residence, $7.15 million allows for:
- Residential Rentals: Providing steady cash flow and tax advantages through depreciation.
- REITs (Real Estate Investment Trusts): For liquid exposure to commercial and industrial property.
- Syndications: Participating as a limited partner in large-scale apartment or office developments.
3. Alternative Investments (10–15%)
High-net-worth individuals often have access to "alternative" asset classes that are not available to the general public:
- Private Equity: Investing directly in private companies.
- Private Credit: Lending money to businesses at higher interest rates than traditional bonds.
- Collectibles: Fine art, rare watches, or classic cars, which have gained traction as inflation hedges by 2026.
4. Cash and Fixed Income (5–10%)
Maintaining a "cash bucket" of 1–2 years of living expenses (approx. $300,000–$600,000) prevents the need to sell stocks during a market downturn.
Addressing the Ambiguity: What if "7 150" Means $7,150?
While less likely to be the subject of a "net worth" inquiry in a professional context, if your net worth is seven thousand one hundred and fifty dollars, the answer to "is it good" changes drastically.
In 2026, $7,150 is a precarious financial position for an adult. It is above the bottom 20% of the population (who often have negative net worth due to debt), but it is significantly below the median.
- The Problem: $7,150 is often less than three months of essential living expenses in most US cities.
- The Action Plan: Focus on high-interest debt elimination (credit cards) and building an emergency fund. At this level, the "investment" with the highest return is usually "human capital"—upskilling to increase earned income.
Common Pitfalls at the $7.15 Million Level
Having a "good" net worth does not make one immune to financial ruin. In fact, $7 million is often cited as a "danger zone" where individuals feel wealthy enough to spend lavishly but are not yet "rich" enough to sustain that spending indefinitely without careful management.
- Lifestyle Creep: Upgrading to a $4 million home with $100,000 in annual property taxes and maintenance can quickly erode a $7.15 million nest egg.
- Over-Concentration: Keeping too much wealth in a single company's stock (often the result of an IPO or employee stock options) exposes the individual to catastrophic loss if that one company fails.
- Under-Insuring: At this level, you are a target for litigation. High-net-worth individuals require Umbrella Insurance (typically $5M–$10M in coverage) to protect assets from lawsuits.
- Lack of Liquidity: Having $7.15 million in land or private business equity is "good" on paper, but if you cannot access cash to pay taxes or bills, you are "asset rich and cash poor."
Comparison Table: Net Worth Tiers in 2026
| Feature | $1 Million (Entry Level) | $7.15 Million (HNW) | $25 Million+ (VHNW) |
|---|---|---|---|
| Retirement Readiness | Partial; requires social security/pension. | Full; high-end lifestyle possible. | Generational; wealth survives for decades. |
| Investment Access | Standard Brokerage/IRA. | Hedge Funds, Private Equity, IPOs. | Direct Venture Capital, Family Office. |
| Tax Complexity | Moderate (Standard 1040). | High (K-1s, Trust Returns). | Extreme (Global tax structures). |
| Primary Risk | Outliving money/Inflation. | Lawsuits/Tax law changes. | Market systemic collapse. |
| Estate Strategy | Simple Will. | Irrevocable Trusts/Gifting. | Charitable Foundations/GRATs. |
Frequently Asked Questions
Is $7.15 million enough to retire at age 40?
Yes, but it requires a disciplined budget. Using a conservative 3.5% withdrawal rate to account for a longer retirement horizon, you would have $250,250 per year. If your desired lifestyle costs more than this, or if you live in a very high-cost city without owning your home outright, you may need to continue working part-time or reduce expenses.
Does a $7.15 million net worth make me "rich"?
In 2026, "rich" is a subjective term. Statistically, you are in the top 2%, which most would define as rich. However, in "wealth hubs" like Aspen, Miami, or Monte Carlo, $7 million is considered "comfortable middle class" among the local elite. Most sociologists and economists define $7.15 million as "High Net Worth" but not "Ultra High Net Worth" (which starts at $30 million).
Should I pay off my mortgage if I have $7.15 million?
In 2026, this depends on your interest rate versus your expected investment return. If you have a legacy mortgage at 3% or 4%, it is mathematically superior to keep the debt and invest the cash in assets yielding 7%+. However, many HNW individuals choose to pay off their primary residence for the psychological "peace of mind," which is a valid choice when you have a $7.15 million surplus.
How much of my $7.15 million should be in cash?
Financial advisors generally recommend keeping 6 to 12 months of living expenses in a high-yield savings account or money market fund. If your annual spend is $250,000, you should keep approximately $125,000 to $250,000 liquid. Keeping more than $1 million in cash is generally discouraged as it loses purchasing power to inflation.
Can I afford a private jet or yacht with $7.15 million?
No. Owning and maintaining a private jet or a large yacht usually requires a net worth exceeding $50 million to $100 million. At $7.15 million, the "entry price" of these assets would consume a massive portion of your capital, and the annual maintenance (often 10% of the purchase price) would quickly deplete your net worth. Chartering or fractional ownership is a more sustainable way for someone at the $7M level to enjoy these luxuries occasionally.
Next Steps for Managing 7.15 Million
If you have reached or are approaching a net worth of $7,150,000 in 2026, your priorities should shift from accumulation to preservation.
- Audit Your Estate Plan: Given the 2026 tax sunset, meet with an estate attorney immediately to ensure your assets are protected from increased federal taxes.
- Optimize for Taxes: Work with a CPA who specializes in high-net-worth clients to explore tax-loss harvesting, charitable remainder trusts, and municipal bonds.
- Secure Umbrella Insurance: Ensure you have at least $7 million in liability coverage to protect your assets from personal injury claims or other lawsuits.
- Review Asset Location: Ensure your most tax-inefficient assets (like high-yield bonds) are held in tax-advantaged accounts (like an IRA), while growth assets are held in taxable accounts to take advantage of long-term capital gains rates.
A net worth of $7,150,000 is an incredible achievement. It represents a level of freedom that the vast majority of the global population will never experience. By managing it with the same discipline used to acquire it, you can ensure financial security for yourself and future generations.
Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
