Understanding the Workers Compensation Policy Conditions Section 2

Workers compensation policy conditions Section 2 outlines the fundamental contractual obligations that policyholders must fulfill to maintain coverage and ensure the effective processing of claims. This section typically details the employer’s duties regarding the inspection of workplaces, the maintenance of payroll records, and the mechanisms by which the insurer determines final premiums, serving as the bridge between theoretical coverage and actual financial liability.
The Role of Conditions in Workers Compensation Policies
A workers compensation policy is a legal contract, and like any binding agreement, its effectiveness depends on the adherence of both parties to specific rules. The "Conditions" section of a standard policy—most notably the NCCI (National Council on Compensation Insurance) standard form—is divided into multiple parts. Section 2 is specifically designed to manage the "administrative" life of the policy.
While the "Information" page (the declarations page) defines who is covered and for how much, the conditions section defines how the relationship operates on a day-to-day basis. If an employer fails to meet these conditions, the insurer may have grounds to deny a claim, audit the premium, or even cancel the policy mid-term. Understanding this section is essential for risk managers and business owners who want to avoid disputes during the audit process or during the high-stakes period following an employee injury.
Inspection and Workplace Safety Obligations
One of the most critical components of Section 2 is the insurer’s right to inspect the insured's premises. Insurers are not merely financial entities; they are risk management partners. By including an inspection clause, the policy grants the insurer the right, though not the obligation, to enter the business premises to evaluate safety conditions, machinery, and operational procedures.
It is important to recognize that the insurer's inspection is conducted for the purpose of underwriting and rating. It is not a substitute for a comprehensive OSHA (Occupational Safety and Health Administration) compliance audit. However, if an insurer identifies hazardous conditions during an inspection, they may require the employer to implement corrective measures as a condition of maintaining the policy. Failure to cooperate with these requests can lead to a formal notice of cancellation. Employers should treat these inspections as an opportunity to reduce their experience modification factor, which directly influences premium costs.
The Importance of Payroll Record-Keeping
Perhaps the most frequent source of friction between businesses and insurance carriers involves payroll records. Section 2 mandates that the insured must maintain detailed, accurate records of all employees, their classifications, and the remuneration (wages) paid to them.
Because workers compensation premiums are calculated based on payroll—specifically, the amount of money paid to employees within specific class codes—the insurer must be able to verify these numbers. Under Section 2, the insurer maintains the right to examine these books at any time during the policy period and for up to three years after the policy expires.
Common mistakes in record-keeping include:
- Misclassification: Assigning an employee to a lower-risk (and cheaper) class code when their actual duties fall into a higher-risk category.
- Failure to track overtime: While some states allow the exclusion of the "overtime premium" portion of wages, the base pay must still be clearly demarcated.
- Incomplete 1099 tracking: Failing to distinguish between true independent contractors and misclassified employees can lead to significant "premium adjustment" invoices following an audit.
Premium Determination and the Audit Process
The "Premium" condition within Section 2 explains that the initial premium paid at the start of the policy is merely an estimate. Because a business’s actual payroll may fluctuate throughout the year due to seasonal hiring, layoffs, or rapid expansion, the final premium must be calculated after the policy term concludes.
The process of "premium adjustment" is governed by the conditions in this section. The insurer will perform a final audit to ensure the estimated premium aligns with the actual risk exposure. If the business paid more in wages than estimated, the employer will receive a bill for the additional premium. If they paid less, a refund or credit is issued. Business owners who ignore the documentation requirements or fail to cooperate with the audit process can face severe penalties, including the application of punitive "audit non-compliance" charges, which can be significantly higher than the actual premium owed.
Transfer of Your Rights and Duties
Section 2 also addresses the legal transferability of the policy. In the event of a merger, acquisition, or the death of an individual policyholder, the policy cannot simply be "handed off" to a new entity without the insurer's written consent.
This condition exists because the risk profile of a company is tied to its ownership and management. If a business changes hands, the insurer needs to re-evaluate the risk. Neglecting to inform the carrier of a change in legal structure or ownership can lead to a gap in coverage, leaving the business entirely exposed to uninsured liability if an employee is injured shortly after a transfer of assets.
Comparison of Key Compliance Areas
The following table summarizes the primary administrative obligations found within Section 2 of a standard workers compensation policy.
| Compliance Area | Employer Requirement | Potential Consequence of Failure |
|---|---|---|
| Workplace Inspection | Provide access to premises for safety evaluation. | Policy cancellation or loss of coverage. |
| Payroll Accuracy | Maintain detailed, class-specific wage records. | Additional charges during final audit. |
| Premium Payment | Remit payments for adjusted final premiums. | Collections, interest, and potential litigation. |
| Ownership Changes | Notify insurer of business structure changes. | Denial of coverage for the new entity. |
| Record Retention | Retain data for at least 3 years post-expiration. | Inability to dispute audit results. |
Handling Disputes Regarding Audits and Classifications
If a disagreement arises regarding the outcome of an audit or the application of a specific classification code, Section 2 provides the framework for resolution. Employers have the right to request a formal review if they believe the insurer has applied incorrect rates or misinterpreted the nature of their operations.
To effectively contest an audit finding, the burden of proof rests on the employer. You must provide concrete evidence—such as tax filings, certified payroll logs, and job duty descriptions—to support your claim. It is advisable to maintain a "workers compensation file" throughout the year, rather than scrambling to organize documentation only after an audit notice is received. If the dispute remains unresolved, the next step typically involves an appeal to the state's rating bureau or insurance department, though this is often a time-consuming process.
Common Misunderstandings About Section 2
One of the most persistent myths is that once a premium is paid, the policy is "locked in." Many businesses operate under the assumption that their premium is a fixed cost. However, Section 2 explicitly creates the mechanism for variable pricing. When a business experiences a "premium adjustment," it is not necessarily an error by the insurer; it is a feature of the policy designed to ensure that the premium accurately reflects the risk exposure that actually occurred.
Another common misunderstanding involves the "independent contractor" status. Employers often believe that if they sign a contract labeling a worker as an independent contractor, the insurer will accept this at face value. However, the condition regarding payroll records implies that the insurer has the right to look behind the contract to the reality of the work performed. If the insurer determines that these individuals are, in fact, employees under state law, the business will be assessed premiums for them during the final audit.
Practical Advice for Maintaining Compliance
To stay in compliance with the conditions outlined in Section 2, businesses should adopt a proactive stance. First, establish a clear system for coding employees. Ensure that all HR software is capable of segmenting payroll by the specific class codes listed on your policy. If you have employees whose duties span multiple categories, ensure your record-keeping practices are granular enough to justify the allocation of their wages to the appropriate class.
Second, schedule an internal pre-audit three months before the end of your policy term. Review your payroll totals against the estimates provided to your broker at the start of the year. If you notice a significant discrepancy, contact your insurance agent immediately. Proactively addressing a potential premium increase is always better than receiving a massive, unexpected invoice from the carrier.
Third, maintain an open line of communication regarding physical changes to your business. If you open a new branch in a different state, renovate a facility, or introduce new heavy machinery to your production line, notify your broker. These changes may trigger a need for a mid-term endorsement, which is often easier to handle than a retroactive audit adjustment.
Navigating the Future of Policy Compliance (2026 Context)
As of 2026, many insurance carriers have transitioned to digital, real-time auditing platforms. While this has streamlined the verification process for many, it also means that errors in payroll reporting are caught much faster. Relying on paper records is no longer the standard; businesses should ensure their accounting software is integrated or at least compatible with the reporting requirements of their carrier.
Frequently Asked Questions
What happens if I refuse an inspection by the insurance carrier? Refusing an inspection is a direct violation of the policy conditions. The insurer has the right to cancel your policy for failure to cooperate. Always coordinate with your broker to ensure the inspection is scheduled at a time that minimizes operational disruption.
Why did my final premium increase after the audit? Your final premium likely increased because your actual payroll exceeded the estimates provided at the policy's inception. Workers compensation rates are applied to your total payroll; if you hired more staff or paid more in wages than projected, the additional risk exposure requires a higher premium.
Can I appeal the results of an insurance audit? Yes. You have the right to challenge audit findings. You must submit a written dispute to the insurer detailing exactly which figures or classifications you believe are incorrect, supported by relevant payroll documentation.
Does Section 2 cover injury claims? No. Section 2 covers the conditions, obligations, and premium calculations. The actual coverage for medical expenses and lost wages for injured employees is found in Section 1 of the policy.
How long should I keep payroll records for audit purposes? Standard policy conditions require that you retain these records for three years following the expiration of the policy. However, many accounting best practices suggest keeping them for seven years to satisfy general tax and regulatory requirements as well.
Final Recommendation
The conditions in Section 2 are not merely fine print; they are the operational manual for your workers compensation coverage. Treat your payroll documentation and safety records as critical assets. If you are uncertain about how your current record-keeping practices align with your policy requirements, request a "compliance check" from your insurance broker. By ensuring that your payroll and classification records are audit-ready at all times, you protect your company from unexpected financial volatility and maintain a healthy, transparent relationship with your insurance carrier.
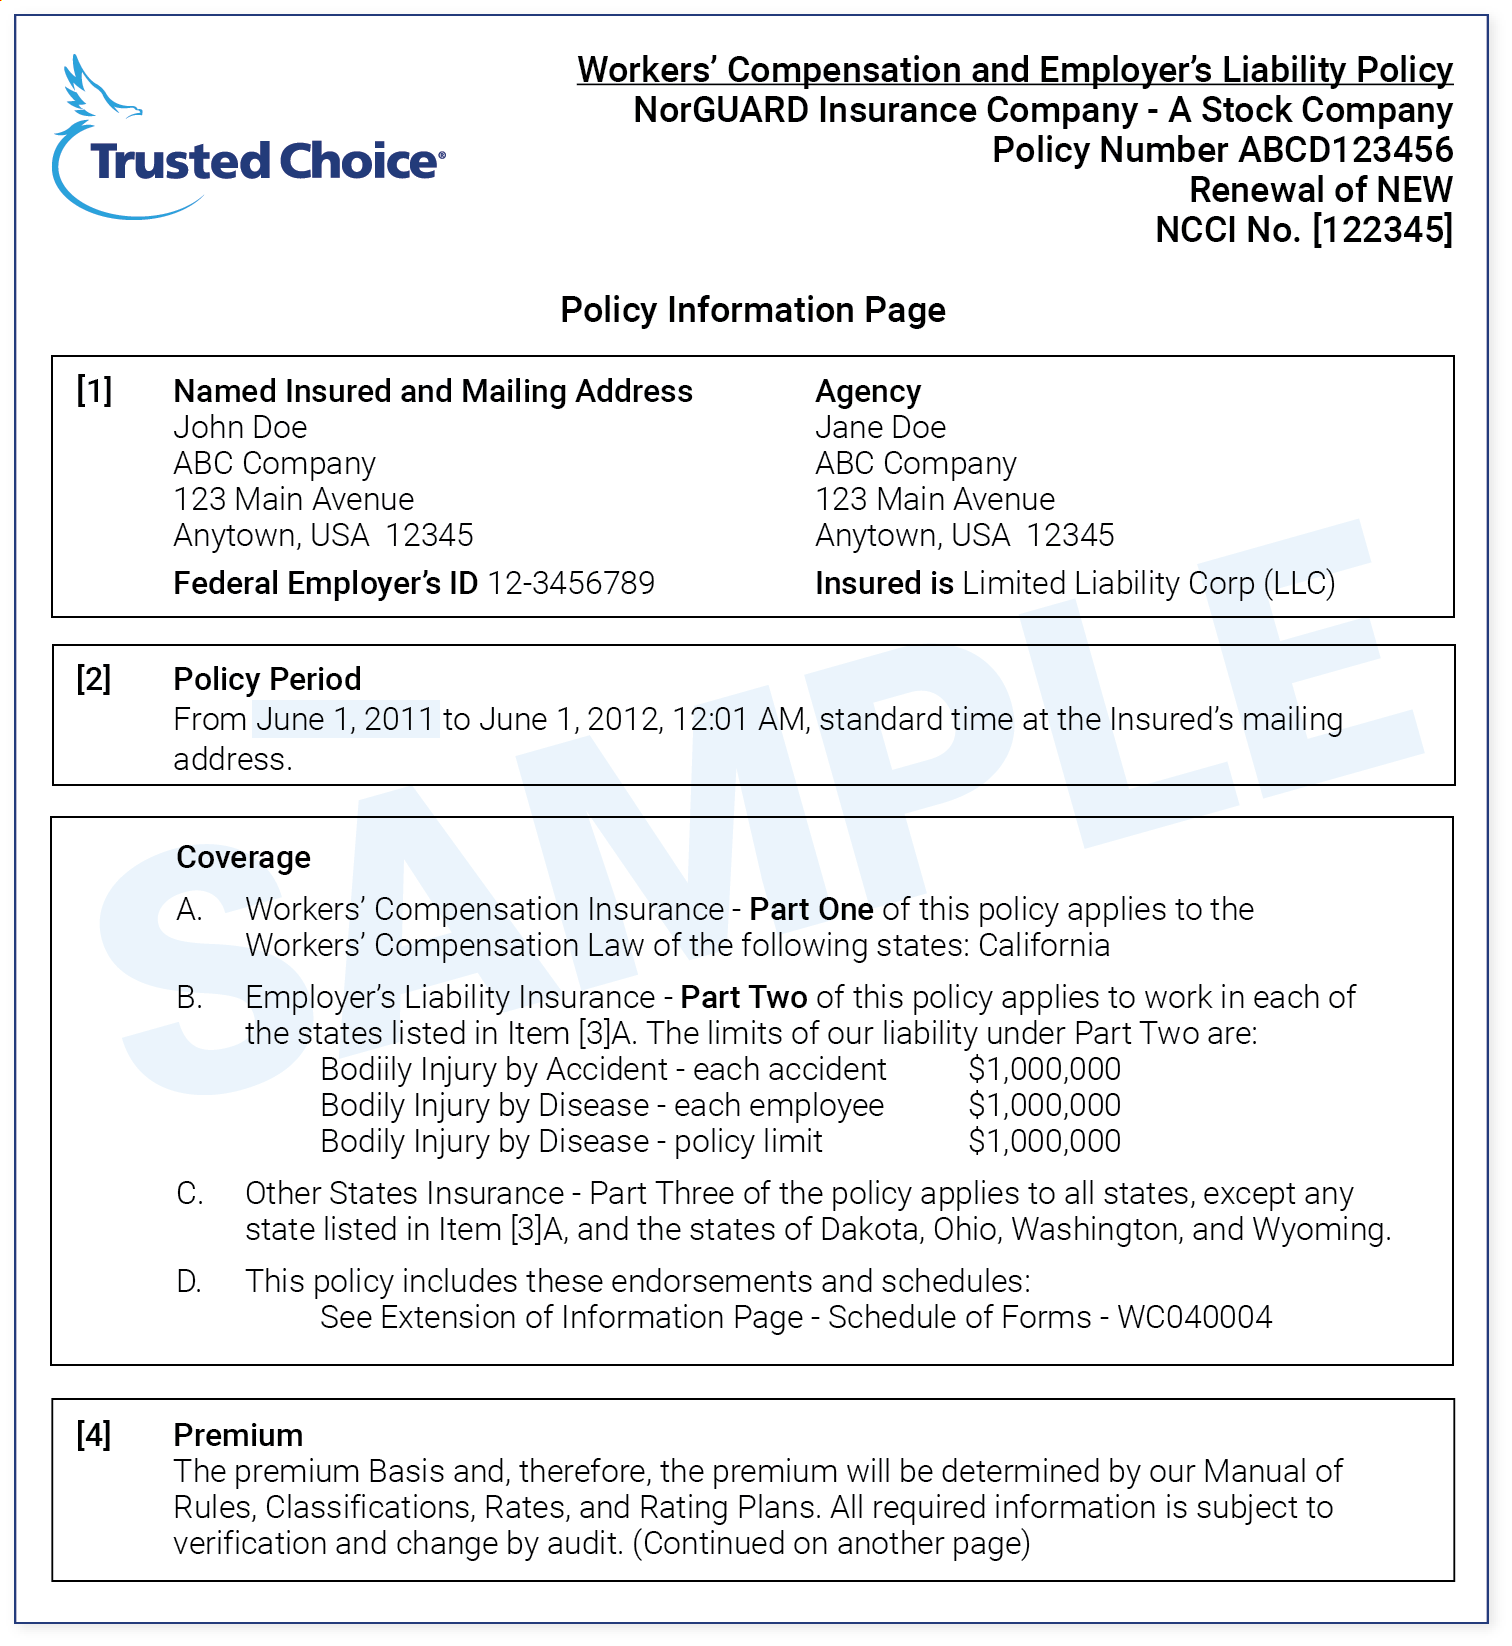
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
