
Obtaining term coverage life insurance for individuals associated with Blackwater—now operating under the umbrella of Constellis and Academi—requires navigating high-risk underwriting and specialized "war zone" exclusions. While standard retail policies often deny coverage for private military contractors (PMCs) deployed to hostile environments, specialized brokers and employer-sponsored group plans provide essential financial protection for these high-risk professionals.
Understanding the Landscape of Life Insurance for Private Security Contractors
The name "Blackwater" remains synonymous with the private military and security industry, though the entity has evolved through several rebrandings, including Xe Services and Academi, before becoming a core part of the Constellis group. In 2026, the demand for private security remains high globally, but the insurance market for these individuals is markedly different from that of the general public.
For a contractor working for an organization like Constellis (formerly Blackwater), term life insurance is a temporary policy that provides a death benefit if the insured passes away during the policy term. However, the nature of the work—protecting high-value targets, performing convoy security, or training foreign national forces—creates a risk profile that most "Main Street" insurance companies are unwilling to touch. Underwriters look at the occupational hazards, the specific geographic location of the deployment, and the nature of the tasks performed.
Most standard term life insurance policies contain a "War Exclusion" or "Act of War" clause. This means that if an individual dies due to military action or in a designated conflict zone, the policy will not pay out. For a contractor at the former Blackwater, this makes a standard policy virtually useless during deployment. To solve this, contractors must seek out policies with specialized riders or go through the "surplus lines" market, where insurers like Lloyd’s of London specialize in high-stakes risks.
The Underwriting Challenges for High-Risk Personnel
When applying for term coverage life insurance, a contractor must undergo a rigorous underwriting process. This is the method by which an insurance company evaluates the risk of insuring a person and determines the premium. For those in the private security sector, the underwriting process is split into three primary categories: medical risk, lifestyle risk, and occupational/geographic risk.
Occupational and Geographic Risk
This is the most significant hurdle. If you are a static security guard in a low-risk country, your rates might be near standard. However, if your contract involves "Blackwater-style" operations—mobile security, high-threat protection (HTP), or intelligence support in volatile regions—the risk of "violent death" increases exponentially. Underwriters use data from the U.S. State Department and international security analysts to categorize regions. A deployment to a Level 4 "Do Not Travel" zone will trigger either a flat rejection from standard carriers or a significant "flat extra" fee.
The "Flat Extra" Fee Structure
Instead of just raising the "rating" (like moving from Preferred to Standard), insurers often apply a "flat extra." This is a specific dollar amount—for example, $5.00 or $10.00 per $1,000 of coverage—added to the base premium. If a contractor wants a $500,000 policy and has a $5.00 flat extra due to their work with Academi/Constellis in a conflict zone, they would pay an additional $2,500 per year on top of their base premium.
The Impact of Previous Deployments
Even if a contractor is currently "on the beach" (between contracts) or working stateside, their history with Blackwater or similar firms can affect their eligibility. Insurers often ask if the applicant intends to travel to high-risk areas in the next 12 to 24 months. If the answer is yes, the policy will be underwritten as if the contractor is already deployed.

Comparing Group Life vs. Individual Term Policies
For many contractors, the primary source of life insurance is the group policy offered by their employer. Organizations like Constellis typically offer a base level of life insurance as part of the benefits package.
Group Life Insurance Through the Employer
Employer-provided life insurance is often "guaranteed issue" up to a certain amount, meaning there is no medical exam. Crucially, these group policies are often negotiated to include coverage for work-related deaths, even in conflict zones. However, there are significant downsides. The coverage amount is often capped at a low multiple of the contractor's salary (e.g., 1x or 2x annual pay), which may not be enough to support a family. Furthermore, this coverage is usually not portable; if the contractor leaves the company or the contract ends, the coverage vanishes.
Individual Term Life Insurance
An individual term policy is owned by the contractor, not the company. It stays in force regardless of employment status, as long as premiums are paid. For a former Blackwater operative, an individual policy provides long-term stability. The challenge is finding a policy that does not exclude the specific risks associated with the job. Contractors often have to work with specialized high-risk brokers who have access to the "Specialty" or "International" markets.
The Role of the Defense Base Act (DBA) Insurance
It is critical to distinguish between term life insurance and Defense Base Act (DBA) insurance. All U.S. government contractors working overseas are required to be covered by DBA insurance, which is essentially workers' compensation for contractors.
If a contractor is killed while performing their duties under a U.S. government contract, the DBA insurance provides a death benefit to the surviving spouse and children. This benefit is calculated based on the contractor's average weekly wage and is paid out as a recurring benefit rather than a single lump sum.
While DBA provides a safety net, it is not a replacement for term life insurance. DBA only covers deaths that occur "in the course of employment." If a contractor dies of natural causes, an accident while on leave, or in a situation not covered by the government contract, DBA will not pay. Term life insurance provides the "24/7" coverage that DBA lacks.
Key Policy Clauses: What to Look For
When reviewing a policy for a high-risk security role, the "fine print" is where the policy's value is truly determined. Contractors must be vigilant about several specific clauses:
- War and Terrorism Exclusion: Most standard policies exclude death resulting from war, insurrection, or terrorism. For a private security contractor, this exclusion must be removed or "bought back" via a rider.
- Aviation Exclusion: If the contractor’s role involves flying in non-commercial aircraft (such as helicopters or private transport planes used by firms like Constellis), they must ensure the policy covers "non-scheduled aviation."
- Active Duty Military Status: Some policies have clauses that trigger if the policyholder returns to active military duty. While PMCs are civilians, many are former military, and the policy should clearly state how it handles a return to government service.
- Guaranteed Renewability: Given the physical toll of security work, ensuring the policy cannot be canceled if the insured's health declines is vital.
Costs and Coverage Limits for Private Security Personnel
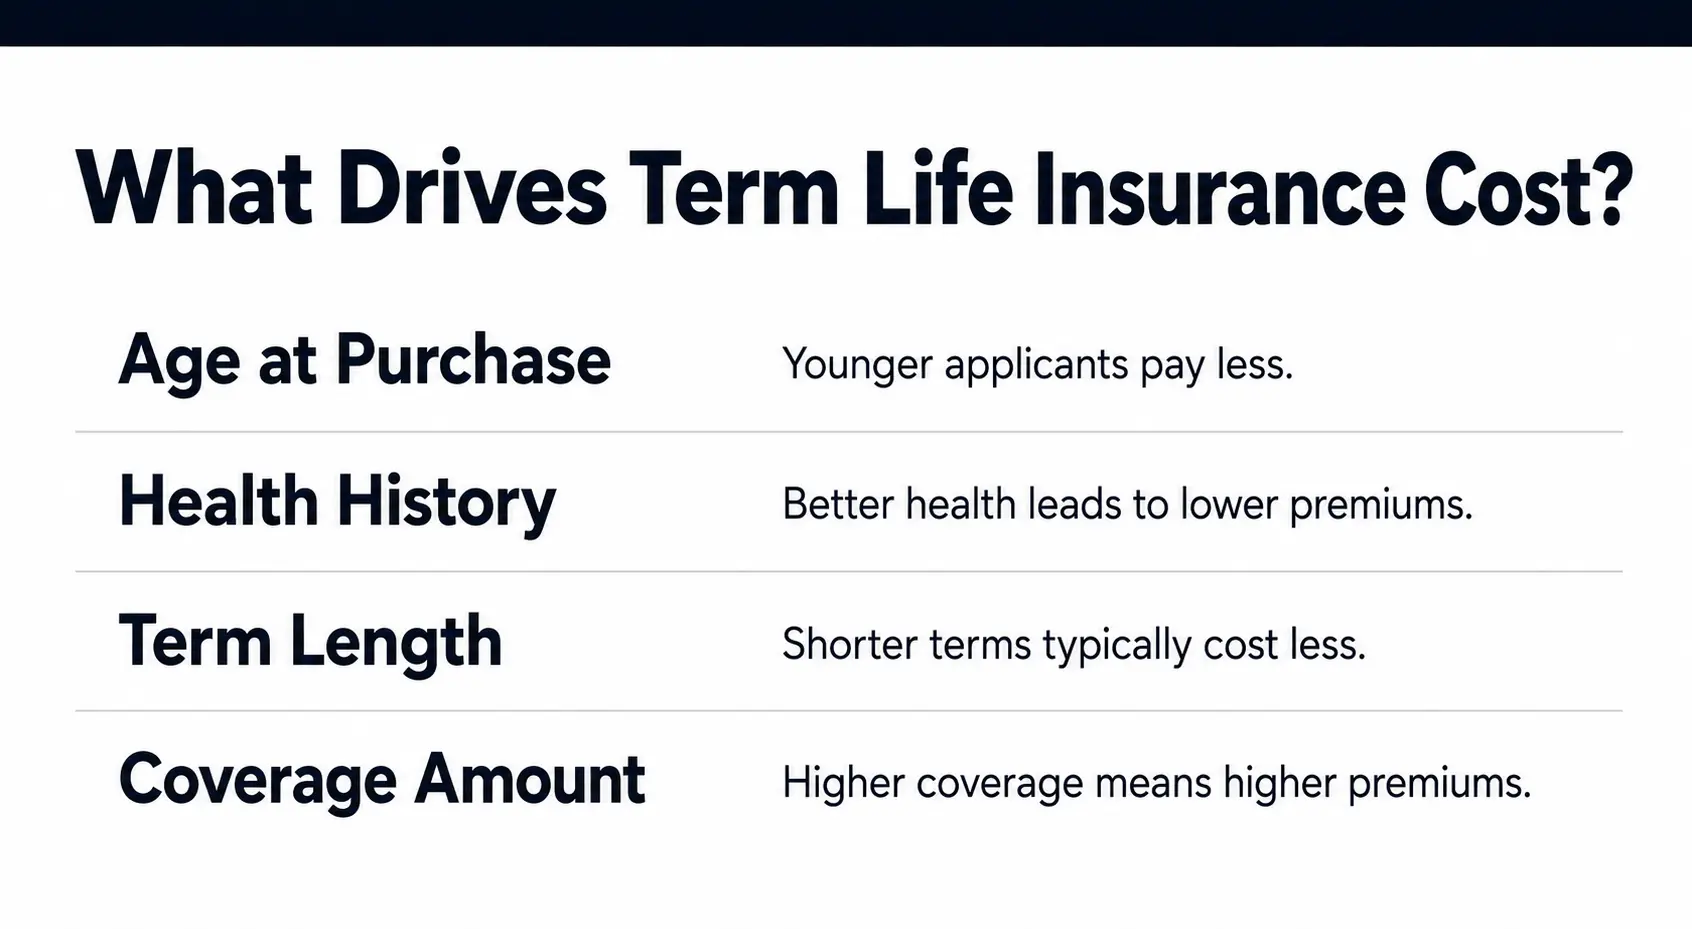
The cost of term coverage for someone in the "Blackwater" niche is significantly higher than for a civilian office worker. Below is a conceptual comparison of how premiums might look for a 35-year-old male in good health seeking $500,000 in 20-year term coverage in 2026.
| Feature | Standard Civilian Policy | Private Security (Low Risk Zone) | Private Security (High Risk/Conflict Zone) |
|---|---|---|---|
| Availability | Widely Available | Moderate Availability | Specialty Markets Only |
| Medical Exam | Required (usually) | Required | Required + Occupational Review |
| War Exclusion | Standard | May be present | Must be removed/waived |
| Estimated Monthly Premium | $25 - $40 | $60 - $100 | $250 - $600+ (includes flat extra) |
| Portability | Yes | Yes | Often Yes (if individual policy) |
| Primary Risk Factor | Health/Age | Travel/Geopolitics | Direct Occupational Hazard |
Note: These figures are estimates for illustrative purposes based on 2026 market trends for high-risk life insurance products.
Steps to Securing Coverage as a Private Military Contractor
If you are currently employed by or seeking employment with a firm like Constellis or Academi, follow these steps to ensure you are properly covered:
1. Audit Your Employer-Provided Benefits
Review the Summary Plan Description (SPD) for your company’s group life insurance. Determine if it covers "Hostile Action" and "War Risk." Identify the "Free Cover Limit"—the amount of insurance you get without having to provide medical evidence.
2. Seek a High-Risk Specialty Broker
Do not apply to five different standard companies online. Every time you are declined, it is recorded in the MIB (formerly Medical Information Bureau) database, which can make future applications harder. Instead, find a broker who specializes in "High-Risk Life Insurance" or "Contractor Insurance." They will "shop" your case informally to underwriters before a formal application is submitted.
3. Be Transparent in the Application
Honesty is paramount. If you fail to disclose your intent to deploy to a high-risk region and then die in that region, the insurance company can deny the claim based on "material misrepresentation." Provide details about your specific role; an administrative contractor at a secure base is viewed differently than a Tier 1 security professional on a mobile team.
4. Consider AD&D as a Supplement
Accidental Death and Dismemberment (AD&D) insurance is often easier to obtain than traditional life insurance for high-risk roles. While it doesn't cover death by natural causes, it provides a significant payout for accidental death or catastrophic injury (loss of limbs, sight, etc.), which are high-risk factors in the security industry.
Frequently Asked Questions
Can I get term life insurance if I am already deployed?
It is extremely difficult to start a new policy while you are already in a conflict zone. Most insurers require the "wet signature" and medical exam to be completed while you are on U.S. soil or in a non-hazardous country. If you are already deployed, you may need to wait until your next R&R (Rest and Recuperation) leave to finalize a policy.
Does the "Act of War" clause always apply to contractors?
In standard policies, yes. However, specialty policies designed for the private security industry explicitly remove or modify this clause. You must ensure your policy includes a "War Risk Rider" or similar language that confirms the insurer is aware of and accepting the risk of death in a conflict zone.
What happens if the company name changes from Blackwater to something else?
The name of the company (Blackwater, Xe, Academi, Constellis) is less important than the nature of the work and the location. As long as you accurately describe your duties and the region where you work, a name change of your employer does not invalidate your policy. However, you should notify your broker if your job description changes significantly (e.g., moving from an office role to a field role).
Are premiums tax-deductible for contractors?
Generally, personal life insurance premiums are not tax-deductible for the individual. However, if you are an independent contractor (1099) and the life insurance is required by a contract or is part of a business structure, you should consult a tax professional. For most W-2 employees of security firms, premiums are paid with after-tax dollars.
Is there a maximum age for coverage in this industry?
Most high-risk underwriters for PMCs will offer coverage up to age 60 or 65, provided the individual can pass the medical exam. However, the "flat extra" fees often increase as the contractor ages, making the cost of coverage very high for older contractors in field roles.
How do I prove my "Blackwater" experience won't make me uninsurable?
Underwriters value experience. A seasoned professional with 15 years of experience in high-threat environments is often seen as a lower risk than a "rookie" on their first deployment, as the veteran is perceived to have better situational awareness and survival skills. Highlight your training and longevity in the field.
Practical Recommendation for Contractors
For anyone currently or formerly associated with the Blackwater legacy of companies, the most robust strategy is a layered approach. Rely on the company-provided group life insurance for your "base" coverage, but supplement it with a private, high-risk term policy that you own personally. This ensures that even if you change employers or the company changes its benefits structure, your family remains protected. Always work with a broker who understands the difference between a "Standard" risk and a "Surplus" risk to avoid unnecessary denials on your insurance record.
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
