
In Michigan, you can obtain a life insurance loan if you own a permanent life insurance policy, such as whole life or universal life, that has accumulated sufficient cash value. These loans allow policyholders to borrow against their policy’s equity using the Michigan Insurance Code's consumer protections, typically without credit checks or lengthy bank approval processes.
As of 2026, life insurance remains a foundational pillar of financial planning for Michigan residents. Beyond the primary purpose of providing a death benefit to beneficiaries, permanent policies offer a unique feature: the ability to access liquid capital through policy loans. Unlike traditional bank loans, these are private agreements between the policyholder and the insurance company, governed by specific state statutes and the language of the individual contract.
Navigating the landscape of insurance-based lending requires an understanding of both the mechanical operations of the policy and the regulatory environment maintained by the Michigan Department of Insurance and Financial Services (DIFS). Whether you are looking to cover emergency expenses, fund a business venture, or manage a temporary cash flow gap, understanding the nuances of life insurance loans is essential for protecting your long-term financial health.
The Mechanism of Life Insurance Loans in Michigan
To understand if you can get a life insurance loan, you must first distinguish between the two primary types of life insurance: term and permanent. Term life insurance provides coverage for a specific period (e.g., 10, 20, or 30 years) and does not accumulate cash value. Consequently, you cannot take a loan against a term policy.
Permanent life insurance, including whole life, universal life, and variable life, includes a "savings" component known as cash value. A portion of your premium payments is directed into this account, where it grows over time on a tax-deferred basis. In Michigan, once your cash value reaches a certain threshold—usually after the policy has been in force for three to five years—you gain the right to borrow against it.
It is a common misconception that you are "borrowing your own money." In reality, the insurance company provides you with a loan from its own general fund, using your policy’s cash value as collateral. This distinction is critical because it explains why your cash value can continue to earn dividends or interest even while a loan is outstanding, though the rate of return on the collateralized portion may be reduced.
Legal Framework: Michigan Insurance Code and Policy Loans
Life insurance policies sold in Michigan must comply with the Michigan Insurance Code (Act 218 of 1956). This legislation ensures that certain "standard provisions" are included in every contract to protect the consumer. Specifically, Chapter 40 of the Code addresses life insurance and annuity contracts.
Under Michigan Compiled Laws (MCL) 500.4022, insurance companies are required to include a provision that allows the policyholder to borrow an amount equal to or less than the cash surrender value of the policy. The law also dictates how interest rates can be applied to these loans. Michigan allows for either a fixed interest rate (often capped at 8% depending on the policy vintage) or an adjustable rate that is tied to a recognized index, such as the Moody’s Corporate Bond Yield Average.
The Michigan Department of Insurance and Financial Services (DIFS) oversees these regulations to ensure that insurers do not charge usurious rates and that they provide clear disclosures regarding how loans affect the policy’s death benefit and potential for lapse.
Eligibility Requirements for Michigan Policyholders
While Michigan law mandates the inclusion of loan provisions in permanent policies, eligibility is not instantaneous. To secure a loan in 2026, you generally must meet the following criteria:
- Policy Type: You must hold a permanent policy. This includes Whole Life, Universal Life, Indexed Universal Life (IUL), or Variable Universal Life (VUL).
- Accumulated Cash Value: There must be enough equity in the policy to support the loan. Most insurers require a minimum loan amount (e.g., $500 or $1,000) and will only lend up to 90% or 95% of the total cash surrender value to ensure the policy remains in force.
- Premium Status: The policy must be in good standing. If you are in a grace period for unpaid premiums, the insurer may require you to bring the policy current before approving a loan.
- Ownership Rights: You must be the absolute owner of the policy. If the policy has been collaterally assigned to a bank for a different loan or is owned by an Irrevocable Life Insurance Trust (ILIT), the process for obtaining a loan becomes significantly more complex and may require third-party consent.
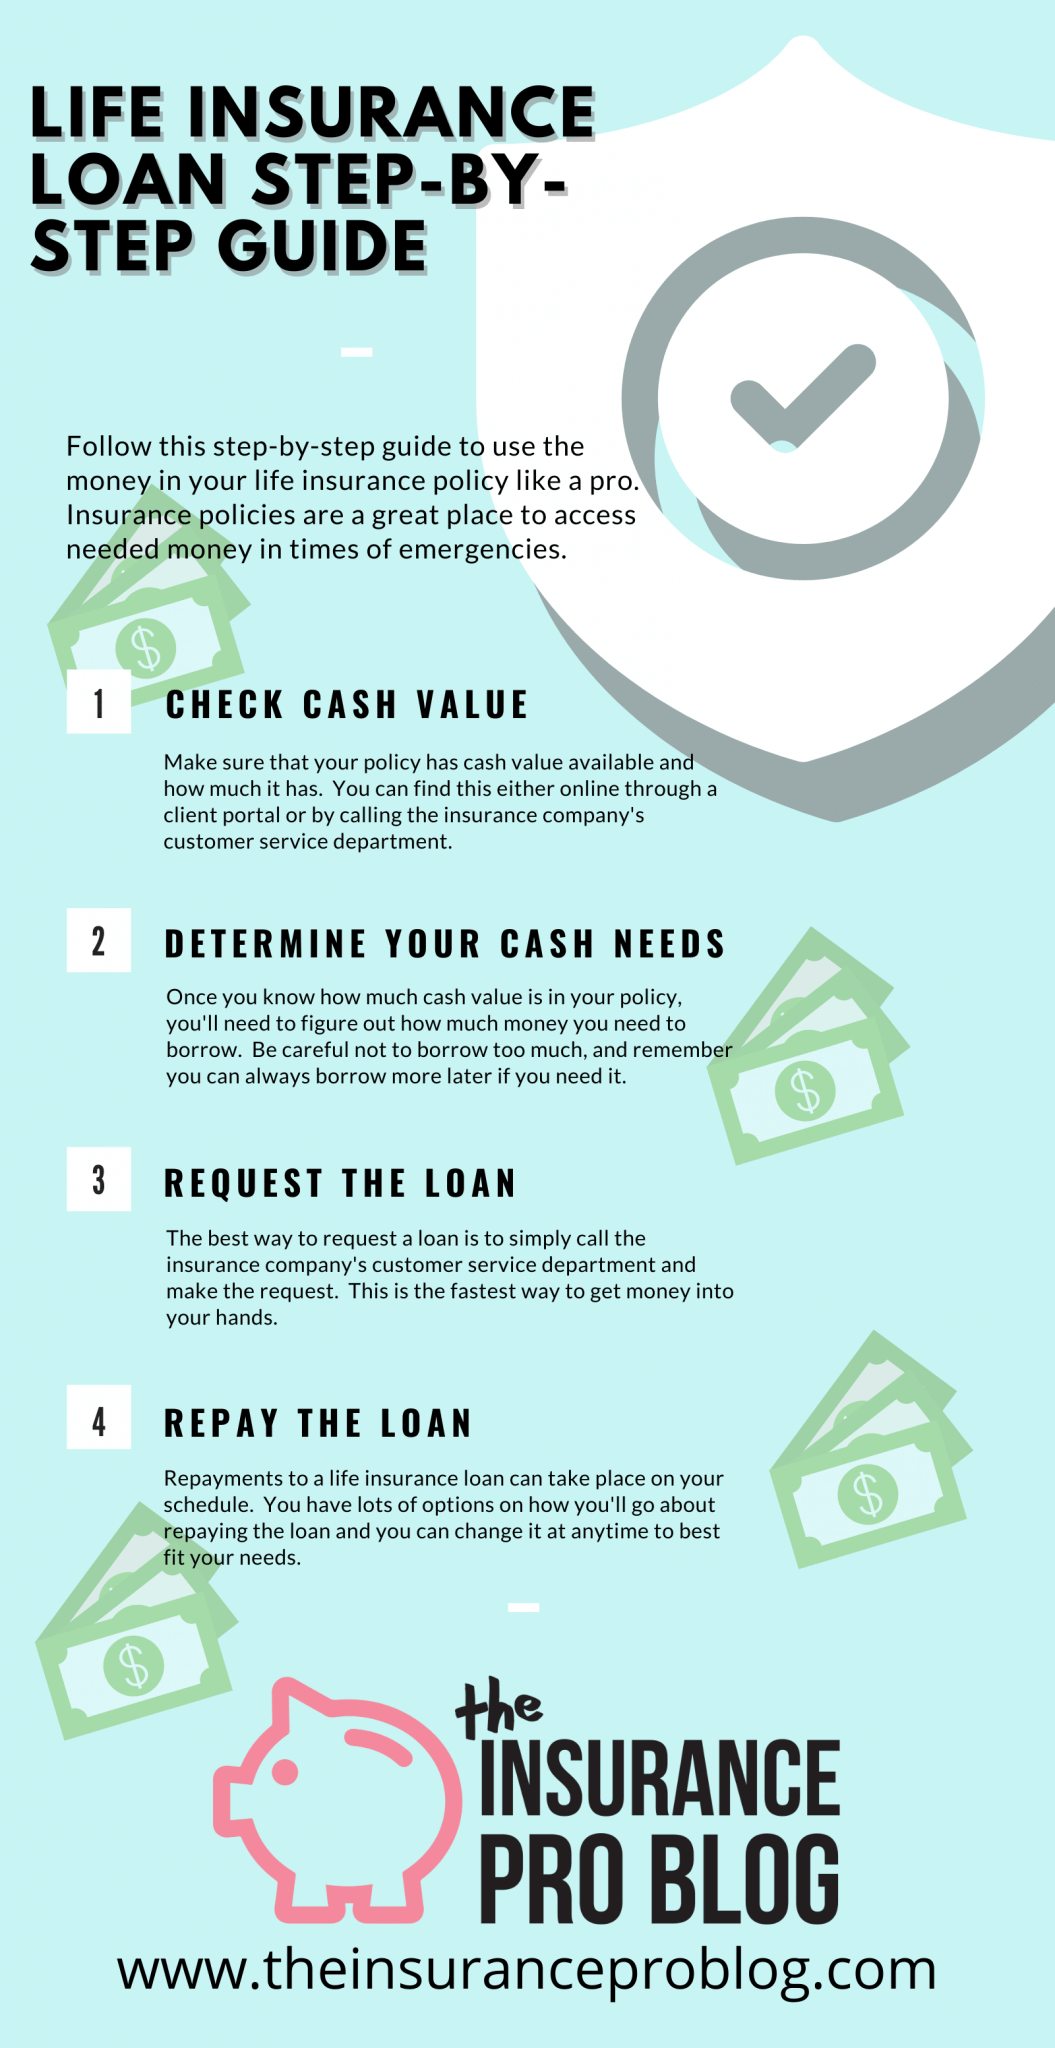
The Step-by-Step Process of Securing Your Loan
The process of obtaining a life insurance loan in Michigan is significantly faster than traditional lending because the loan is fully secured by the policy's cash value. There is no credit check, no income verification, and no "purpose of loan" inquiry.
- Request an Illustration: Before taking a loan, ask your insurance agent or the company's customer service department for an "in-force illustration." This document projects how the loan will affect your cash value and death benefit over time.
- Verify the Available Loan Value: The insurance company will calculate your maximum loan limit based on the current cash surrender value minus any existing loans and the next year's anticipated interest.
- Complete the Loan Request Form: Most major insurers operating in Michigan, such as Northwestern Mutual, Michigan Millers, or State Farm, provide online portals where you can request a loan. Alternatively, you can submit a paper form.
- Choose a Disbursement Method: Funds are typically sent via Electronic Funds Transfer (EFT) to your bank account or via a physical check. In 2026, most Michigan residents receive funds within 3 to 5 business days.
- Set Up a Repayment Plan: While the insurer will not force a repayment schedule, it is prudent to establish one to avoid the accumulation of compound interest.
Interest Rates and Repayment Terms in 2026
In the 2026 financial environment, interest rates on life insurance loans remain competitive compared to personal loans or credit cards. Rates typically range between 4% and 8%.
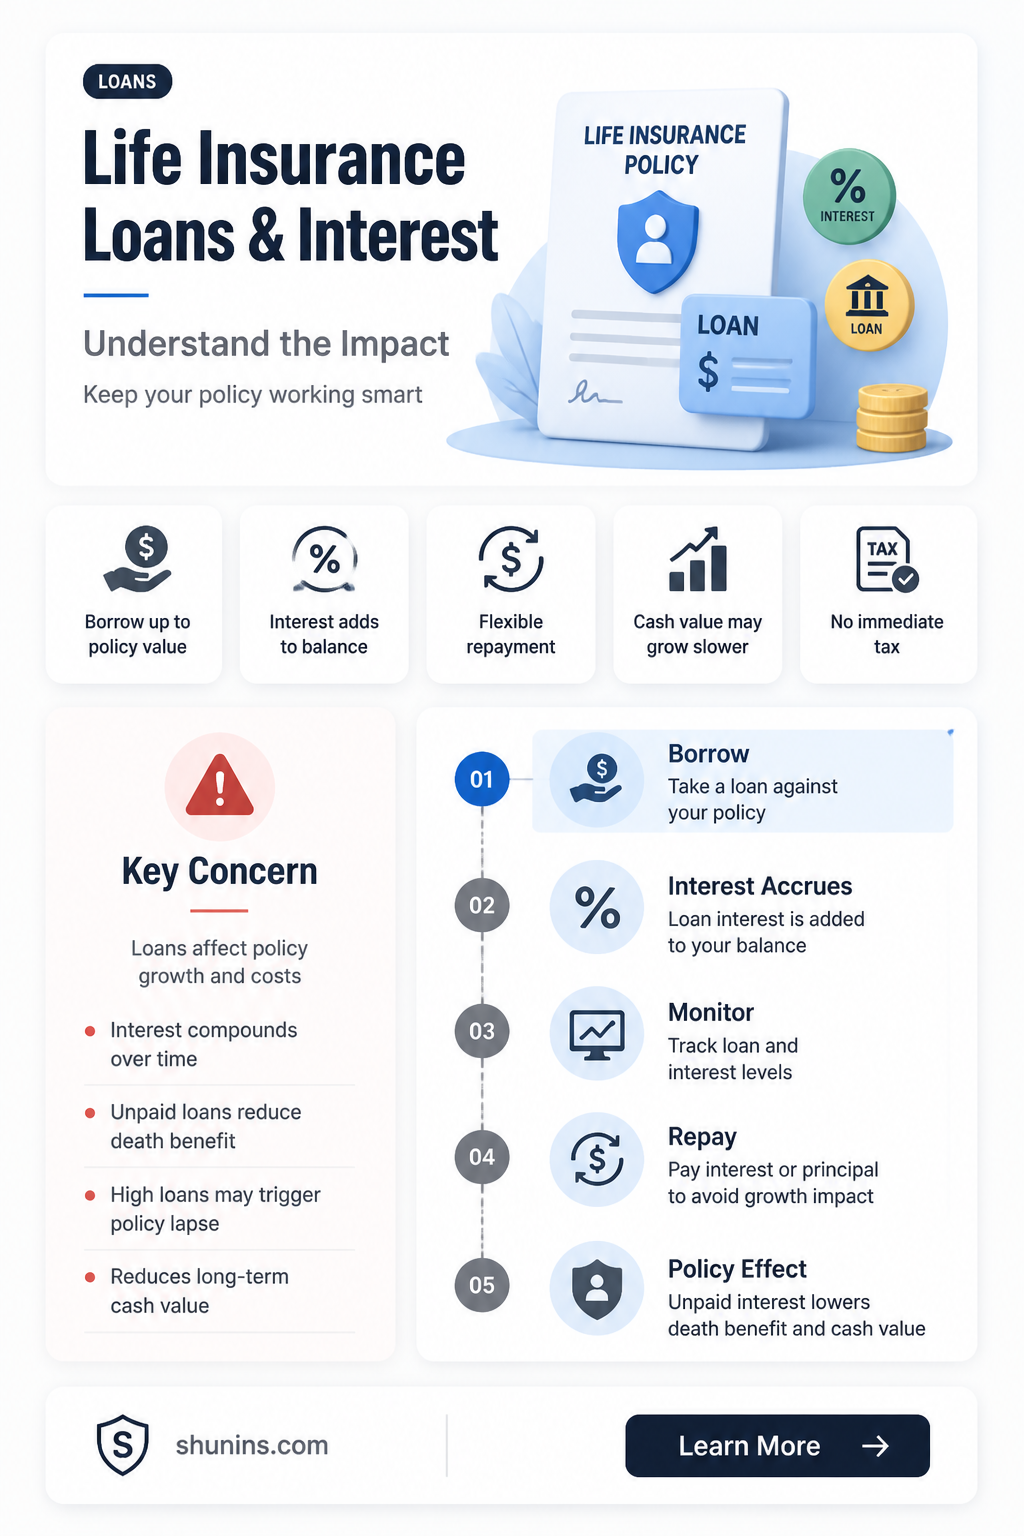
One of the most significant advantages of a policy loan in Michigan is the flexibility of repayment. You are not legally required to make monthly payments. Any unpaid interest is simply added to the loan balance (capitalized). However, this convenience comes with a risk: if the total loan balance plus accrued interest exceeds the policy's cash value, the policy will enter a "lapse" status. If the policy lapses, the loan is considered "repaid" using the cash value, which may trigger a significant tax liability.
Comparison: Policy Loans vs. Alternative Financing
| Feature | Life Insurance Loan | Traditional Bank Loan | Credit Card |
|---|---|---|---|
| Credit Check | None | Required | Required |
| Interest Rates | Generally Low (4-8%) | Moderate to High | Very High (15-25%+) |
| Repayment Schedule | Flexible/Optional | Fixed Monthly | Fixed Monthly Minimum |
| Tax Implications | Generally Tax-Free | None | None |
| Impact on Assets | Reduces Death Benefit | None (Unsecured) | None |
Potential Risks: Lapses, Taxes, and Death Benefit Impacts
While the ability to get a life insurance loan in Michigan offers financial flexibility, it is not without hazards. Borrowers must be aware of the "tax trap" and the impact on their beneficiaries.
The Modified Endowment Contract (MEC) Risk
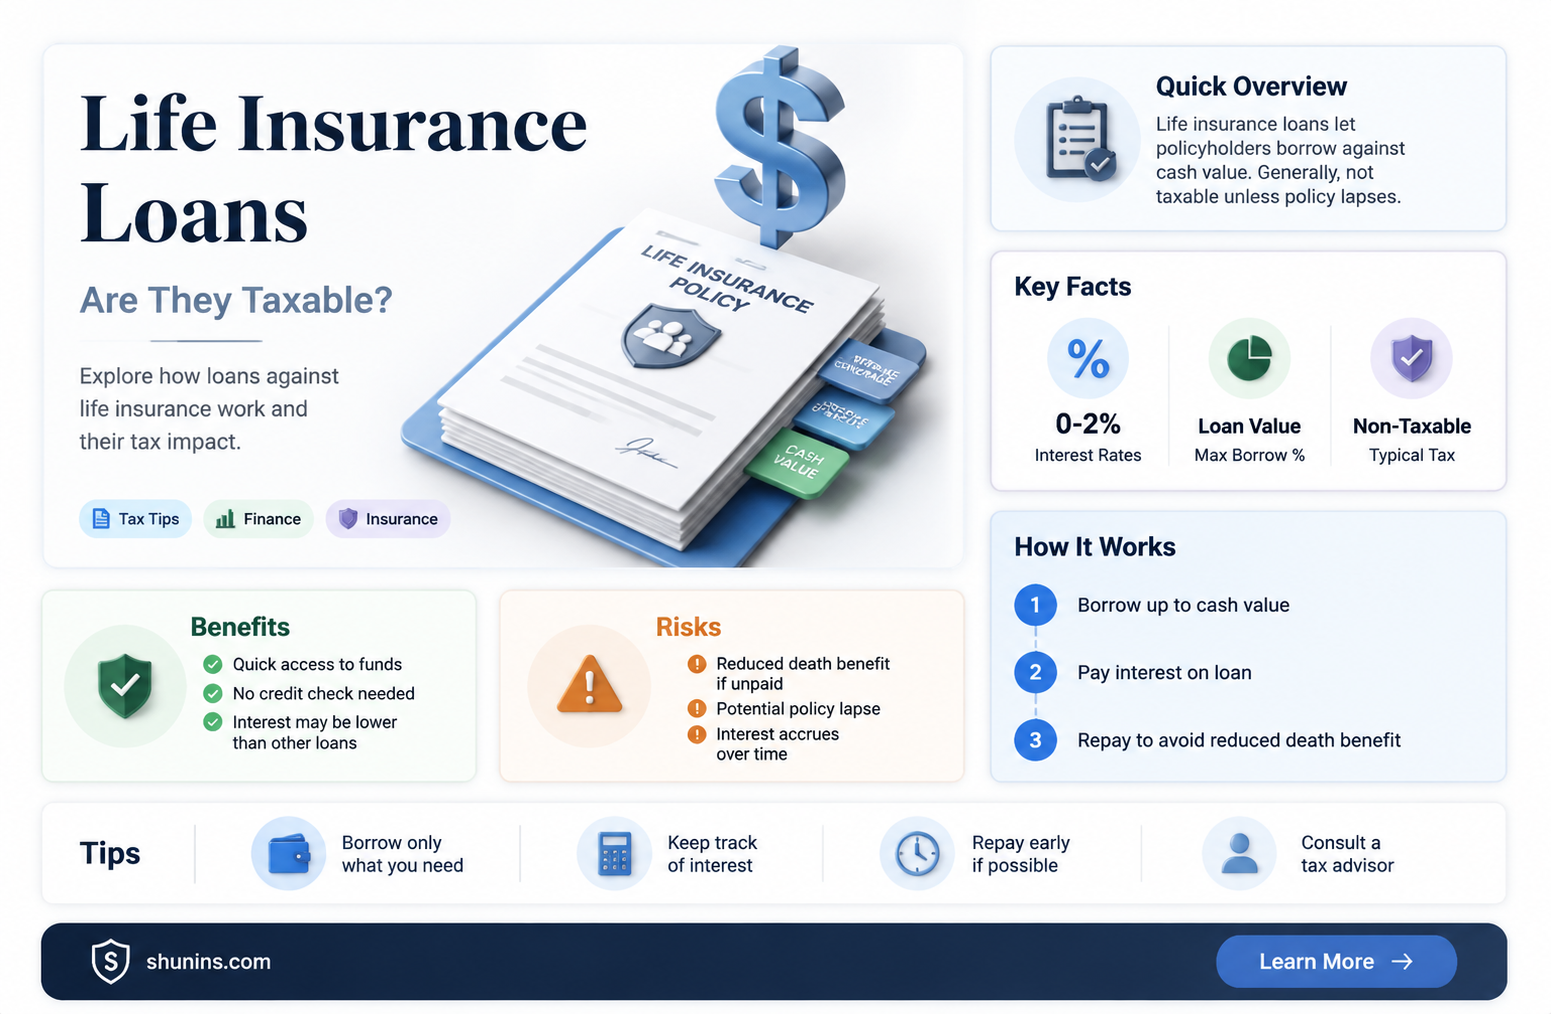
Under the Internal Revenue Code, if a policy is funded too quickly, it may be classified as a Modified Endowment Contract (MEC). If your policy is a MEC, any loan you take is treated as "income first" for tax purposes, meaning you will owe taxes on the growth portion of the loan. Furthermore, if you are under age 59½, you may be subject to a 10% federal tax penalty. Always verify the MEC status of your policy with a tax professional before borrowing.
Death Benefit Reduction
The most direct impact of a loan is the reduction of the death benefit. If you have a $500,000 policy and take a $50,000 loan, your beneficiaries will only receive $450,000 if you pass away before the loan is repaid. For Michigan families relying on these funds for mortgage protection or college tuition, this reduction can be devastating.
The Lapse and Tax Liability
If the loan balance grows to the point that it exceeds the cash value, the policy will terminate. When this happens, the IRS treats the forgiven loan as a "distribution." You will be taxed at your ordinary income rate on the amount of the loan that exceeds the total premiums you paid into the policy (your cost basis). For long-standing policies, this can result in a massive, unexpected tax bill.
Alternatives to Life Insurance Loans in Michigan
If the risks of a policy loan seem too high, Michigan residents have other ways to access their policy's value:
- Partial Withdrawals: Some universal life policies allow for withdrawals. Unlike loans, withdrawals do not accrue interest, but they permanently reduce the cash value and death benefit. Withdrawals are generally tax-free up to your cost basis.
- Cash Surrender: You can cancel the policy entirely and receive the cash surrender value. This ends your coverage and may trigger taxes on the gains.
- Policy Dividends: If you have a participating whole life policy, you may be able to take your annual dividends in cash rather than using them to buy more coverage or pay premiums.
- Bank Collateral Assignment: Some Michigan banks allow you to use your life insurance policy as collateral for a bank loan. This might offer a lower interest rate than the insurance company’s internal loan rate, but it involves credit checks and fixed repayment terms.
Frequently Asked Questions
Does taking a life insurance loan in Michigan affect my credit score?
No. Because the loan is secured by your own policy’s cash value, insurance companies do not report these loans to credit bureaus like Equifax, Experian, or TransUnion. Similarly, failing to repay the loan will not damage your credit score; it will simply reduce your death benefit or cause the policy to lapse.
Can the insurance company deny my loan request?
If you have a permanent policy with sufficient cash value and meet the contractual requirements, the insurer generally cannot deny your loan. In Michigan, the right to a policy loan is a contractual and statutory right. However, they can delay the disbursement for up to six months under certain extreme economic conditions, though this is very rare.
What happens if I die before the loan is repaid?
If the insured individual dies with an outstanding loan, the insurance company will subtract the loan balance plus any accrued interest from the total death benefit. The remaining balance is then paid to the named beneficiaries.
Are there any restrictions on how I use the loan money in Michigan?
No. There are no restrictions on the use of funds. Michigan policyholders use life insurance loans for everything from home repairs and medical bills to supplementing retirement income or investing in a new business.
Is the interest on a life insurance loan tax-deductible?
Generally, no. For most individuals, interest paid on a life insurance policy loan is considered personal interest and is not tax-deductible. If the loan is used for business purposes, you should consult with a Michigan-based CPA to determine if the interest can be categorized as a business expense.
Practical Recommendations for Michigan Policyholders
Before proceeding with a life insurance loan in Michigan, take the following steps:
- Review your original policy contract: Locate the "Policy Loans" section to identify your specific interest rate and any minimum or maximum borrowing limits.
- Calculate the "Cost of Capital": Compare the policy loan rate against other available options. If you have a high credit score, a 2026-era personal loan might occasionally offer a lower rate than an older life insurance policy with a fixed 8% rate.
- Plan for Repayment: Even though it isn't required, treat the loan like any other debt. Setting up a monthly repayment schedule protects your death benefit and prevents the "interest-on-interest" growth that leads to policy lapses.
- Consult a Professional: If your loan is substantial, speak with a financial advisor to understand how the reduction in death benefit fits into your overall estate plan.
By following these guidelines, you can leverage the liquidity of your life insurance policy to meet your immediate financial needs while ensuring that your long-term protection remains intact.
Image Gallery
Select an image to open it in a new tab.




Celine Dubois
Contemporary Living and Global Arts Columnist
