Navigating Flour Bluff Auto Insurance in Corpus Christi, TX: Coverage, Requirements, and Local Considerations
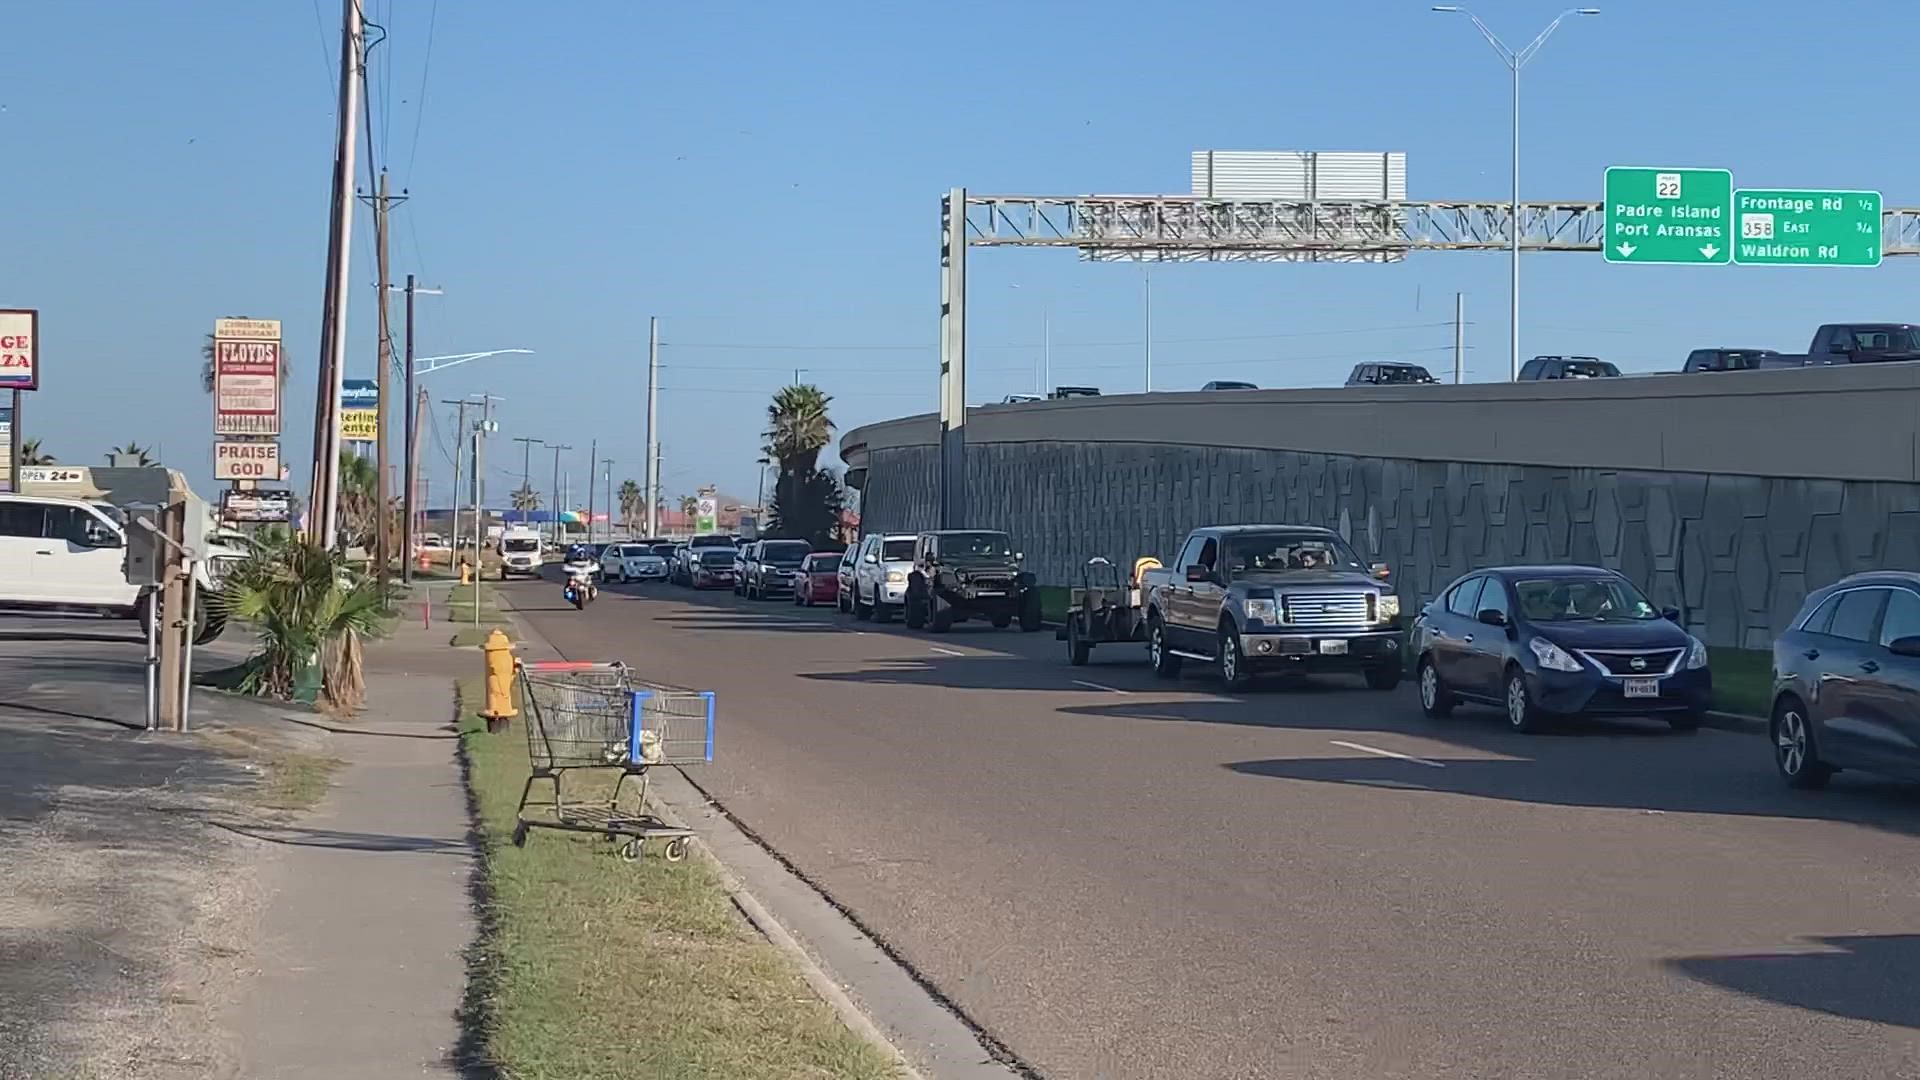
Securing the right auto insurance policy in Flour Bluff, a distinct coastal community within Corpus Christi, Texas, requires understanding state minimum requirements, local driving conditions, and coastal risk factors. Drivers in this area must maintain Texas liability limits, account for weather risks like tropical storms, and navigate ZIP code-based rating factors that influence local premiums.
Understanding the Flour Bluff Insurance Landscape
Flour Bluff is a unique southeastern suburb of Corpus Christi, bounded by the Laguna Madre and Corpus Christi Bay. While it falls under the municipal jurisdiction of Corpus Christi, its coastal geography, bridge-heavy commuting routes, and proximity to Padre Island introduce specific localized variables that auto insurance carriers factor into policy pricing.
When shopping for auto insurance in this area, you are buying a contract governed by Texas insurance laws, but your rates will reflect the specific risk profile of the 78418 ZIP code. Insurance companies evaluate historical claim frequencies in the area, which include weather-related incidents, local traffic density along Waldron Road and SPID (State Highway 358), and commuter patterns across the JFK Causeway.
Legal Auto Insurance Requirements in Texas
Before evaluating local factors, every driver registering a vehicle in Corpus Christi must comply with the Texas Motor Vehicle Safety-Responsibility Act. Texas operates under a "fault" system, meaning the driver who causes an accident is responsible for the resulting damages.
State Minimum Liability Limits (The 30/60/25 Rule)
To legally drive on public roads in Flour Bluff and throughout Texas, your auto insurance policy must carry at least the following liability limits:
- $30,000 of bodily injury liability per person.
- $60,000 of total bodily injury liability per accident.
- $25,000 of property damage liability per accident.
While these minimum limits satisfy legal requirements, they are often insufficient to cover the total costs of a modern traffic accident. If you cause a severe collision, medical bills and vehicle replacement costs can quickly exceed these thresholds, leaving your personal assets vulnerable to lawsuits.
Proof of Insurance Mandates
Texas law requires you to show proof of financial responsibility when:
- You are involved in a traffic accident.
- You are stopped by law enforcement during a traffic stop.
- You renew your vehicle registration at the Nueces County Tax Assessor-Collector’s office.
- Your vehicle is inspected during its annual state inspection.
Drivers can present physical paper cards or digital insurance cards displayed on a smartphone. Texas law enforcement and the Texas Department of Motor Vehicles (TxDMV) utilize the TexasSure verification system to electronically verify active liability coverage.
Factors That Influence Auto Insurance Rates in Flour Bluff
Insurance underwriters use algorithmic risk scoring to determine premiums. Several distinct elements shape what you will pay for coverage in the Flour Bluff area of Corpus Christi.
ZIP Code and Geographic Risk
The 78418 ZIP code encompasses Flour Bluff, Padre Island (partially), and surrounding marshland areas. Insurance companies assess regional data points, including:
- Accident Frequencies: High-traffic corridors such as Waldron Road, personal injury rates on the JFK Causeway, and intersections near Naval Air Station Corpus Christi (NAS Corpus Christi) impact local claims data.
- Weather and Environmental Exposures: Flour Bluff’s coastal geography exposes vehicles to high winds, severe thunderstorms, and potential coastal flooding or tropical storm surges. Comprehensive coverage is vital for protecting vehicles against weather-related perils.
Driving Record and Claims History
Your personal driving habits remain one of the heaviest-weighted pricing factors. Insurers review your Motor Vehicle Record (MVR) for:
- Speeding tickets and moving violations within the past three to five years.
- At-fault accidents and insurance claims.
- Major infractions, such as Driving While Intoxicated (DWI) or reckless driving.
Vehicle Make, Model, and Safety Features
The type of vehicle you drive alters your insurance costs. Vehicles with advanced safety ratings, anti-lock brakes, and electronic stability control often qualify for discounts. Conversely, high-performance sports cars, luxury vehicles, and models with expensive electronic sensors embedded in windshields or bumpers command higher comprehensive and collision premiums due to repair complexity.
Credit-Based Insurance Scores
Under Texas law, insurance companies are permitted to use credit history to help determine insurance rates. Drivers with higher credit-based insurance scores generally qualify for lower premiums, as statistical data indicates a correlation between credit health and claim frequency.
Comprehensive vs. Collision and Coastal Coverages
Given Flour Bluff's peninsular location, standard liability-only policies leave significant financial gaps. Protecting your vehicle against environmental and physical damage requires optional coverages.
Comprehensive Coverage
Comprehensive insurance covers damage to your vehicle from non-collision incidents. In Flour Bluff, this is particularly important for protection against:
- Windstorm and hail damage during severe Texas gulf coast storms.
- Flood damage if your vehicle is parked in a low-lying area during a tidal surge or torrential rain event.
- Animal strikes (e.g., deer or coastal wildlife) or vandalism and theft.
Collision Coverage
Collision coverage pays for repairs to your vehicle if you collide with another car, a guardrail, a telephone pole, or if your vehicle rolls over. If you are financing or leasing your vehicle through a bank or credit union, your lender will mandate both comprehensive and collision coverage regardless of your geographic location.
Uninsured/Underinsured Motorist (UM/UIM) Coverage
Uninsured and underinsured motorist coverage protects you if you are hit by a driver who carries no insurance or lacks adequate limits to pay for your medical bills and car repairs. Given regional uninsured motorist rates, adding UM/UIM coverage to your policy is a widely recommended safeguard.
| Coverage Type | What It Protects Against | Required by Texas Law? | Recommended for Flour Bluff? |
|---|---|---|---|
| Bodily Injury Liability | Injuries you cause to others in an accident | Yes (Minimum 30/60) | Essential (Higher limits recommended) |
| Property Damage Liability | Property/vehicles you damage in an accident | Yes (Minimum $25,000) | Essential (Higher limits recommended) |
| Personal Injury Protection (PIP) | Medical bills and lost wages for you and your passengers, regardless of fault | No (Requires written rejection) | Highly Recommended |
| Comprehensive Coverage | Theft, vandalism, fire, hail, wind, and flood damage | No (Required by lenders) | Highly Recommended (Coastal exposure) |
| Collision Coverage | Damage to your vehicle from a crash or rollover | No (Required by lenders) | Recommended for newer/financed cars |
| Uninsured/Underinsured (UM/UIM) | Accidents involving drivers with insufficient or no insurance | No (Requires written rejection) | Highly Recommended |
Comparing Insurance Options in Corpus Christi
Drivers in Flour Bluff can purchase auto insurance through three primary distribution channels, each offering distinct advantages and limitations.
Captive Insurance Agents
Captive agents work exclusively for one insurance company (such as State Farm, Allstate, or Farmers).
- Pros: Deep familiarity with their company’s specific policy structures, bundle discounts for home and auto, and local office accessibility.
- Cons: They cannot shop rates across competing carriers if your rates increase.
Independent Insurance Agents
Independent agents represent multiple insurance networks and carriers.
- Pros: They can compare quotes across dozens of regional and national insurers to find the most competitive rate for your specific driver profile.
- Cons: Service quality and claims support can vary depending on the specific agency you choose.
Direct-to-Consumer Online Insurers
Direct insurers (such as GEICO, Progressive, or direct-write web platforms) allow you to purchase policies online or over the phone without an agent.
- Pros: Convenient purchasing process, easy policy management apps, and quick quote generation.
- Cons: Lack of personalized local advice regarding coastal specificities or deductible optimization.
Ways to Lower Your Auto Insurance Premiums
Insurance premiums can fluctuate based on market conditions, but several practical strategies help reduce your monthly or annual costs in Flour Bluff:
- Bundle Policies: Combining your auto insurance with homeowners, renters, or umbrella policies through the same provider usually triggers multi-policy discounts ranging from 10% to 25%.
- Increase Deductibles: Raising your comprehensive and collision deductibles from $500 to $1,000 lowers your monthly premium. Ensure you have cash savings set aside to cover the higher out-of-pocket cost if you file a claim.
- Maintain a Clean Driving Record: Avoiding traffic violations and participating in defensive driving courses can qualify you for safe-driver discounts.
- Utilize Telematics Programs: Many insurers offer app-based tracking devices that monitor your driving habits (speed, braking smoothness, mileage). Safe drivers can earn significant discounts through these programs.
- Ask About Affinity Discounts: Check if your employer, alumni association, professional organization, or military service (relevant given NAS Corpus Christi) qualifies you for group discount rates.
Frequently Asked Questions About Flour Bluff Auto Insurance
Does my auto insurance cover flood damage in Flour Bluff?
Standard liability insurance does not cover flood damage to your vehicle. To protect your car against rising water or storm surges common to coastal Corpus Christi, you must carry optional comprehensive coverage. Check your policy declarations page to confirm that comprehensive coverage is active.
Are insurance rates higher in Flour Bluff compared to other parts of Corpus Christi?
Insurance rates vary by ZIP code based on localized claims data, traffic density, and weather risk. Coastal ZIP codes like 78418 can experience different rating adjustments than inland neighborhoods due to windstorm and environmental risk exposures evaluated by actuarial tables.
What should I do immediately after a car accident in Corpus Christi?
First, ensure everyone is safe and move vehicles out of active traffic lanes if it is safe to do so. Call local law enforcement (Corpus Christi Police Department or Nueces County Sheriff depending on the exact location) to file an official accident report. Exchange insurance information, photograph the damage and scene, and report the claim to your insurance provider as soon as possible.
Does Texas require Personal Injury Protection (PIP)?
Texas law requires auto insurers to offer at least $2,500 in PIP coverage, but you have the legal right to reject it in writing. PIP covers medical expenses and lost wages for you and your passengers regardless of fault. Accepting this coverage provides a financial safety net for medical bills before liability claims are settled.
Can I use a digital insurance card during a traffic stop in Texas?
Yes. Texas law officially recognizes electronic proof of insurance. You can display your active insurance card on a smartphone screen when requested by a law enforcement officer. It is still wise to keep a physical copy in your glove compartment in case your phone battery dies.
Next Steps for Flour Bluff Drivers
To secure the most appropriate auto insurance policy for your vehicle in Flour Bluff, gather your current policy details, driver's license numbers, and Vehicle Identification Numbers (VINs). Request quotes from at least three different providers—combining independent agents and direct carriers—to compare coverage limits, deductibles, and premium costs. Review your policy annually to ensure your coverage levels adapt to changes in your vehicle's value, driving habits, and household needs.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
