
Navigating the landscape of 1-2-3 life insurance options requires a clear understanding of how different policy tiers align with your financial goals and the specific mechanisms of a death benefit. These plans typically structure coverage into three progressive levels of protection, allowing policyholders to select a death benefit payout amount that best serves their beneficiaries' immediate needs, debt obligations, or long-term financial security.
Defining the 1-2-3 Life Insurance Framework
When you encounter the phrase "1 2 3 life insurance options," it generally refers to a simplified tier-based approach to policy selection. Insurance carriers often utilize this model to reduce the complexity of the decision-making process for consumers. Instead of navigating dozens of permutations, applicants are presented with three distinct pathways.
Typically, the "1" represents a foundational or "starter" level of coverage, often designed for final expense planning or modest debt repayment. The "2" indicates a mid-tier policy, frequently balancing premium affordability with a more substantial death benefit to cover significant living costs like mortgage balances or education funds. The "3" represents a premier or maximum coverage tier, aimed at comprehensive estate planning, income replacement, or legacy building.
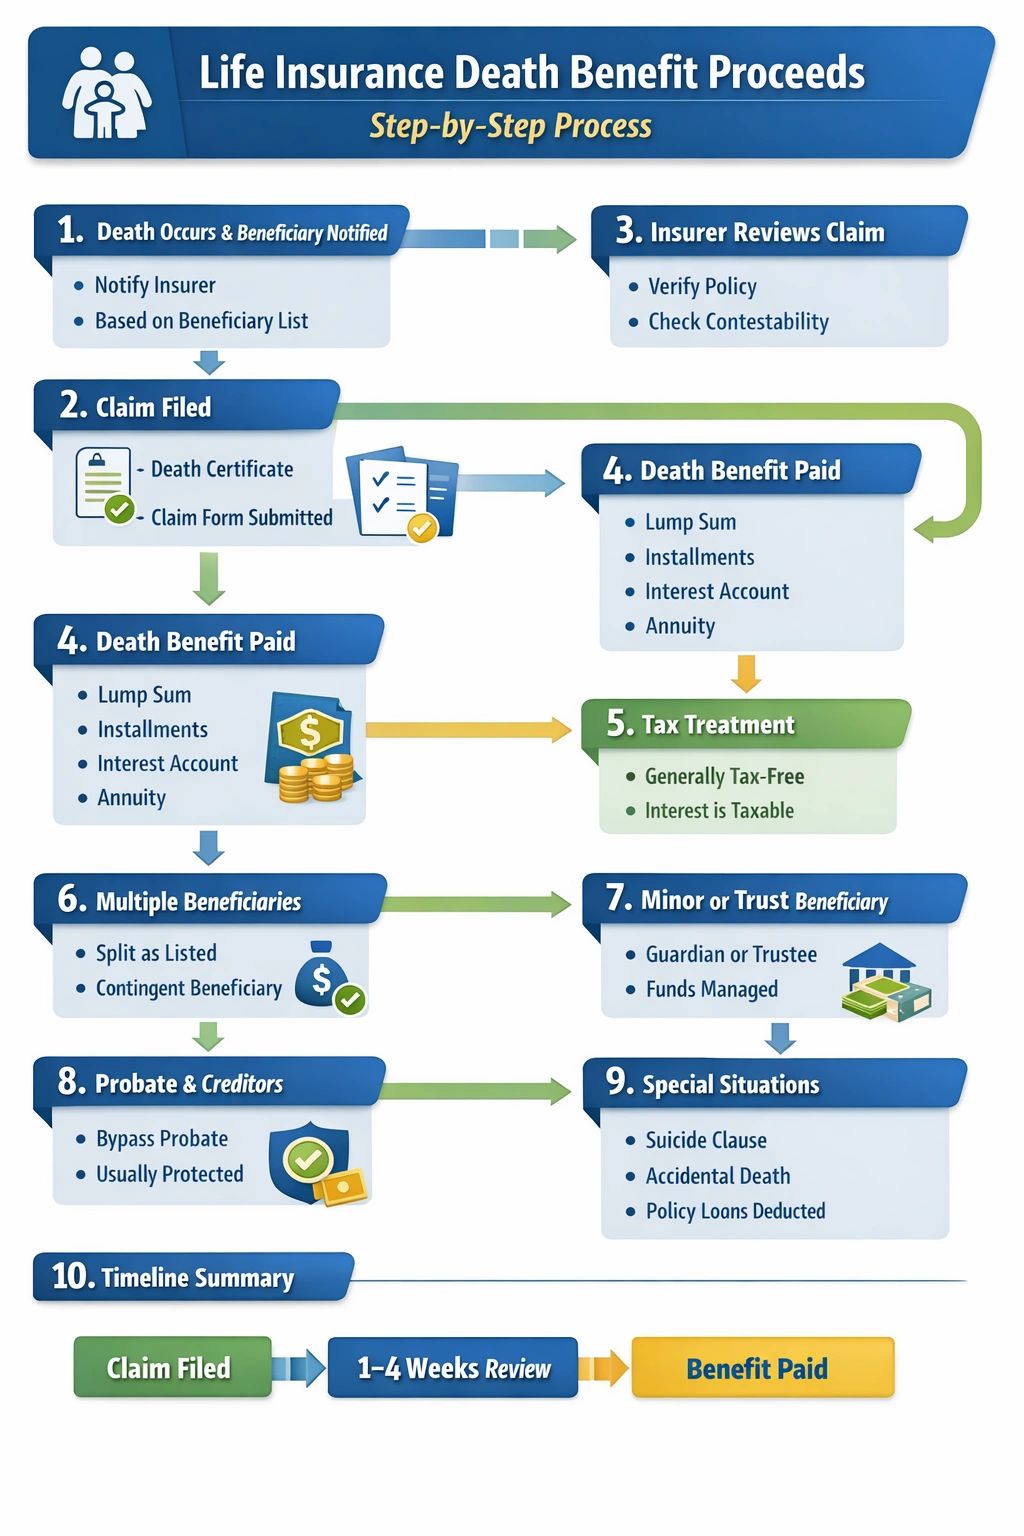
The death benefit—the core component of any life insurance contract—is the tax-free lump sum paid to your designated beneficiaries upon your passing. Understanding how the "1-2-3" options influence this benefit is critical, as the size and terms of the payout vary significantly across these tiers.
Analyzing Death Benefit Mechanics
A death benefit is not a static concept; it is a contractual obligation governed by the policy type and the specific tier chosen under the 1-2-3 model. Regardless of the tier, the primary purpose remains to provide liquidity to your survivors.
Term Life vs. Permanent Options
Within the 1-2-3 structure, you will often find a mix of term and permanent insurance products.
- Term Coverage: Usually found in the "1" or "2" tier, this provides a death benefit for a specified duration (e.g., 10, 20, or 30 years). If the insured passes away during this window, the benefit is paid. If the term expires, the coverage ends.
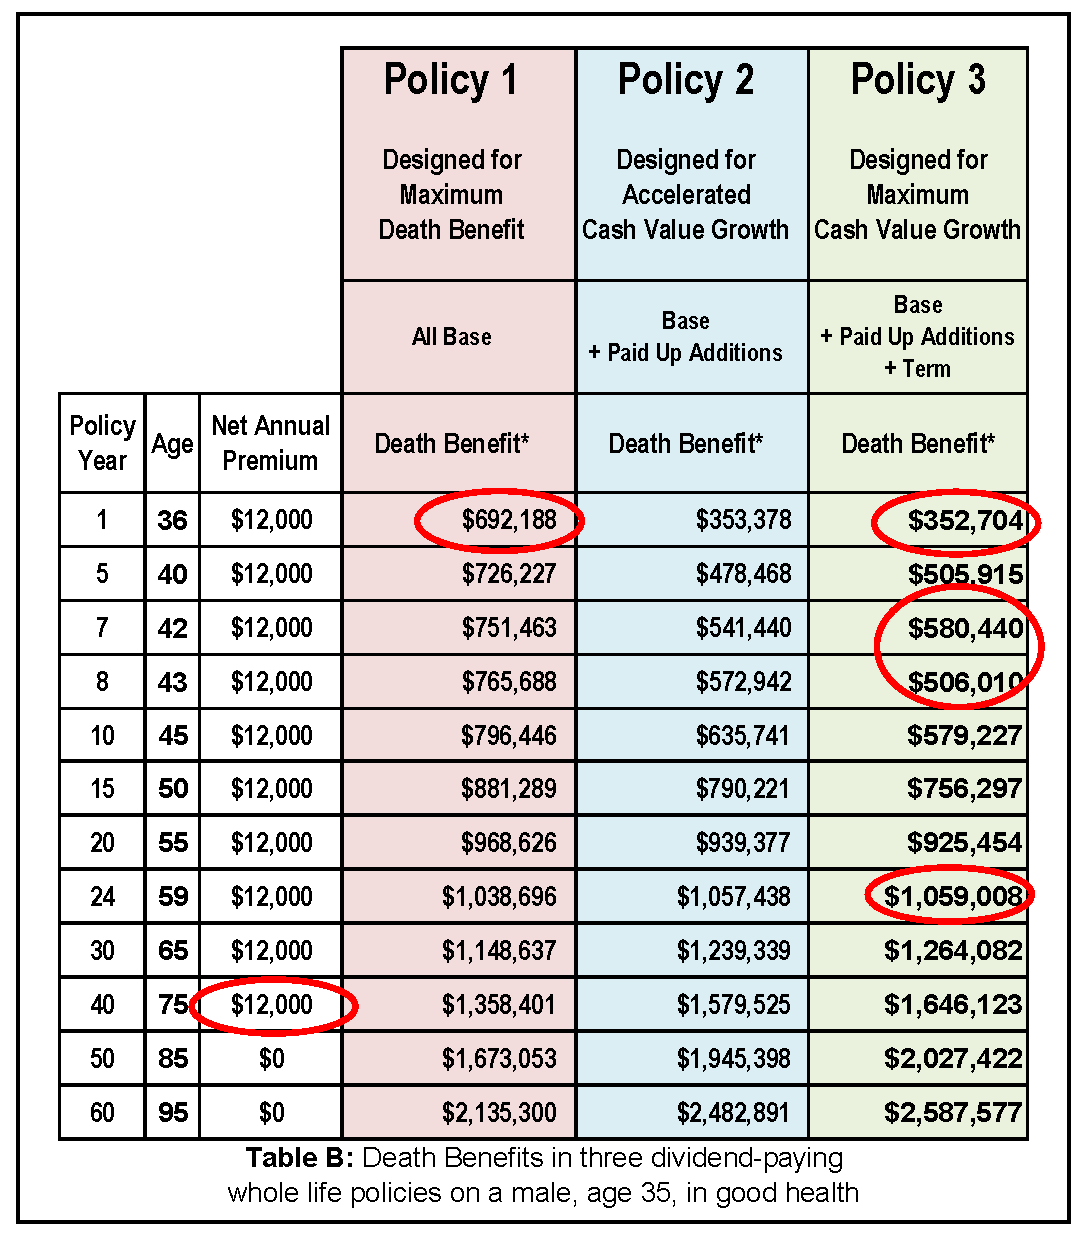
- Permanent Coverage: Often reserved for the "3" tier, products like whole or universal life insurance offer a death benefit that remains in effect as long as premiums are paid. These policies often incorporate a cash value component, which can impact the net death benefit if you choose to borrow against the policy or if the death benefit is designed as a "face amount plus cash value."
Evaluating the Three Tiers of Coverage
To make an informed decision, you must evaluate what each tier actually secures for your beneficiaries.
Tier 1: Foundation and Final Expense
The entry-level option is typically designed for simplicity. The death benefit here is often modest, intended specifically to cover end-of-life expenses such as funeral costs, burial or cremation, and minor outstanding debts. Because the death benefit is lower, the underwriting process for this tier is frequently "simplified issue," meaning you may not require a comprehensive medical exam, though you will still need to answer health-related questions.
Tier 2: Income Protection and Debt Management
The middle tier is the most common choice for working families. The death benefit is calculated to replace a portion of lost income over a set number of years or to retire a specific liability, such as a mortgage. At this level, you are moving beyond simple expenses and into the realm of wealth preservation. The underwriting is usually fully medically underwritten, which can lead to lower premiums for the same death benefit compared to simplified options.
Tier 3: Estate Planning and Legacy
The third tier is the premium level of coverage. Here, the death benefit is significant and is often used to cover estate taxes, provide a large inheritance, or fund a charitable endowment. These policies are highly technical and often involve financial advisors or estate planners to ensure the beneficiary designations and ownership structures are optimized for tax efficiency.
Comparison Table: 1-2-3 Insurance Model
| Feature | Tier 1 (Entry) | Tier 2 (Mid) | Tier 3 (Premier) |
|---|---|---|---|
| Primary Goal | Final Expenses | Debt/Income Coverage | Wealth Transfer/Estate |
| Death Benefit Size | Low ($10k–$50k) | Moderate ($100k–$500k) | High ($500k+) |
| Underwriting | Simplified | Fully Underwritten | Highly Customized |
| Premium Cost | Low / Fixed | Balanced / Tiered | High / Variable |
| Duration | Usually Permanent | Usually Term | Permanent |
Factors Influencing Your Choice
Choosing between these options is rarely about which "number" is best, but rather which aligns with your current life stage. In 2026, economic factors such as inflation and prevailing interest rates influence the cost of premiums, particularly for permanent products.
- Financial Liabilities: List all debts—mortgages, student loans, and credit lines. A Tier 2 policy is often selected to match the remaining balance of these debts.
- Income Replacement Needs: If you are the primary earner, the death benefit should ideally replace 5 to 10 times your annual income. This points toward the upper end of Tier 2 or the beginning of Tier 3.
- Future Insurability: If you opt for a lower tier now with the intent to upgrade later, you must consider the risk of "insurability decline." If your health changes, you may not qualify for the higher tiers of coverage in the future. Buying as much as you can afford early in life is a common strategy to lock in lower rates.
The Role of Beneficiaries and Tax Implications
The death benefit is generally received by beneficiaries as a tax-free lump sum. However, there are nuances. If you name your estate as the beneficiary rather than an individual, the death benefit may become subject to probate and potentially estate taxes.
Furthermore, under the 1-2-3 model, ensure that your beneficiary designations are updated regularly. A death benefit is a contract governed by the policy document, not your will. If your life insurance documentation says one thing and your will says another, the insurance company will follow the policy contract, which can lead to unintended outcomes for your heirs.
Common Mistakes to Avoid
- Underestimating Inflation: A death benefit that seems adequate in 2026 may be insufficient in 2046. If you choose a term-based option in the 1-2-3 structure, ensure the term is long enough to cover your peak years of financial responsibility.
- Ignoring Riders: Many 1-2-3 plans allow you to add "riders"—additional benefits like accelerated death benefits. This feature allows you to access a portion of your death benefit early if you are diagnosed with a terminal illness. This can be a vital financial bridge during medical crises.
- Assuming Coverage Starts Immediately: While some simplified policies have near-instant coverage, others have a "contestability period" (typically two years) during which the insurance company investigates the accuracy of your application. Ensure your health declarations are completely accurate to avoid future disputes regarding the death benefit payout.
Frequently Asked Questions
Does the death benefit change if I change my 1-2-3 tier later? Yes, most carriers allow you to upgrade or downgrade your coverage, though upgrades almost always require new medical underwriting and will result in higher premiums based on your attained age at the time of the change.
Is the death benefit of a 1-2-3 policy always paid in cash? Usually, yes. It is typically paid as a single lump sum. However, some policies offer "settlement options" where the death benefit can be paid out in installments or held by the insurer to earn interest, depending on the policy terms.
What happens if I miss a premium payment on my policy? This depends on the tier. Term policies (usually Tier 1 or 2) have a "grace period," after which the policy lapses and the death benefit is lost. Permanent policies (Tier 3) may use the accumulated cash value to pay the premium automatically, preventing a lapse as long as there is sufficient value.
Are there any circumstances where the death benefit is not paid? Yes, the most common is death by suicide within the initial contestability period, which is typically the first two years of the policy. Additionally, if there was material misrepresentation on your health application, the claim may be denied.
Can I have multiple tiers of 1-2-3 insurance? Absolutely. Many individuals carry a Tier 1 policy for funeral expenses and a Tier 2 policy for mortgage protection. These are separate contracts with separate death benefits.
Next Actions for Policy Selection
To move forward, start by calculating your "Total Need" based on your current debts and the income you wish to provide for your dependents. Compare this against your monthly budget. Once you have a target figure, request a "specimen policy" from your provider. Read the definitions section specifically for the "Death Benefit" to ensure you understand any exclusions or conditions related to the payout. If your financial situation is complex, consult with a fee-only financial planner to verify that your selected tier aligns with your broader tax and estate goals.

Image Gallery
Select an image to open it in a new tab.



Mateo Castillo
Decentralized Finance and E-Payments Strategist
