Determining which lender offers the best Home Equity Line of Credit (HELOC) depends on whether you prioritize low interest rates, rapid funding speed, or high loan-to-value (LTV) limits. In 2026, Figure remains the leader for speed and digital ease, while Bethpage Federal Credit Union and Bank of America offer the most competitive rates and fee structures for traditional borrowers.
The HELOC market in 2026 is characterized by a mix of traditional banking stability and fintech-driven efficiency. As home equity levels remain near historic highs for many long-term homeowners, lenders have refined their products to offer more flexibility, including hybrid fixed-rate options that protect borrowers from the volatility of the prime rate. Selecting the "best" lender requires an analysis of your specific financial profile, including your credit score, the amount of equity available in your property, and how quickly you need access to funds.
The Evolution of HELOCs in 2026
The landscape for home equity products has shifted significantly over the last few years. In 2026, the primary differentiator between lenders is no longer just the interest rate, but the integration of "fixed-rate lock" features. This allows a borrower to take a draw from their variable-rate line of credit and convert that specific balance into a fixed-rate loan, providing a hedge against inflation.
Furthermore, the "appraisal gap" has narrowed. Most top-tier lenders now utilize Automated Valuation Models (AVMs) and "drive-by" exterior inspections rather than full interior appraisals, which has slashed the time-to-fund from weeks to mere days for qualified applicants. When searching for the best lender, it is essential to look beyond the introductory "teaser" rate and examine the lifetime margin, annual fees, and the flexibility of the draw period.
Top-Rated HELOC Lenders by Category
To find the right fit, it is helpful to categorize lenders based on their primary strengths. Different financial institutions cater to different risk profiles and urgency levels.
Figure: Best for Speed and Convenience
Figure has revolutionized the home equity space by utilizing blockchain technology and advanced data analytics to provide a 100% online application process.
- Speed: They are widely recognized for their ability to fund loans in as little as five days, assuming no manual appraisal is required.
- Structure: Unlike a traditional revolving HELOC, Figure typically requires an initial draw of the full amount, though you can draw more as you pay it down. This makes it a hybrid between a home equity loan and a line of credit.
- Best For: Borrowers who have a high credit score (usually 680+) and need cash quickly for an immediate project, such as a major home repair or debt consolidation.
Bank of America: Best for Existing Customers
For those who prefer a traditional banking relationship, Bank of America offers some of the most robust features and loyalty discounts in the industry.
- Relationship Discounts: They often provide rate reductions (sometimes up to 0.625%) for customers who maintain significant balances in their Preferred Rewards accounts.
- No Closing Costs: On many of their HELOC products, Bank of America covers the closing costs, provided the line remains open for a specific period (usually three years).
- Best For: Current Bank of America customers with high liquid assets who want a reliable, long-term line of credit with no annual fees.
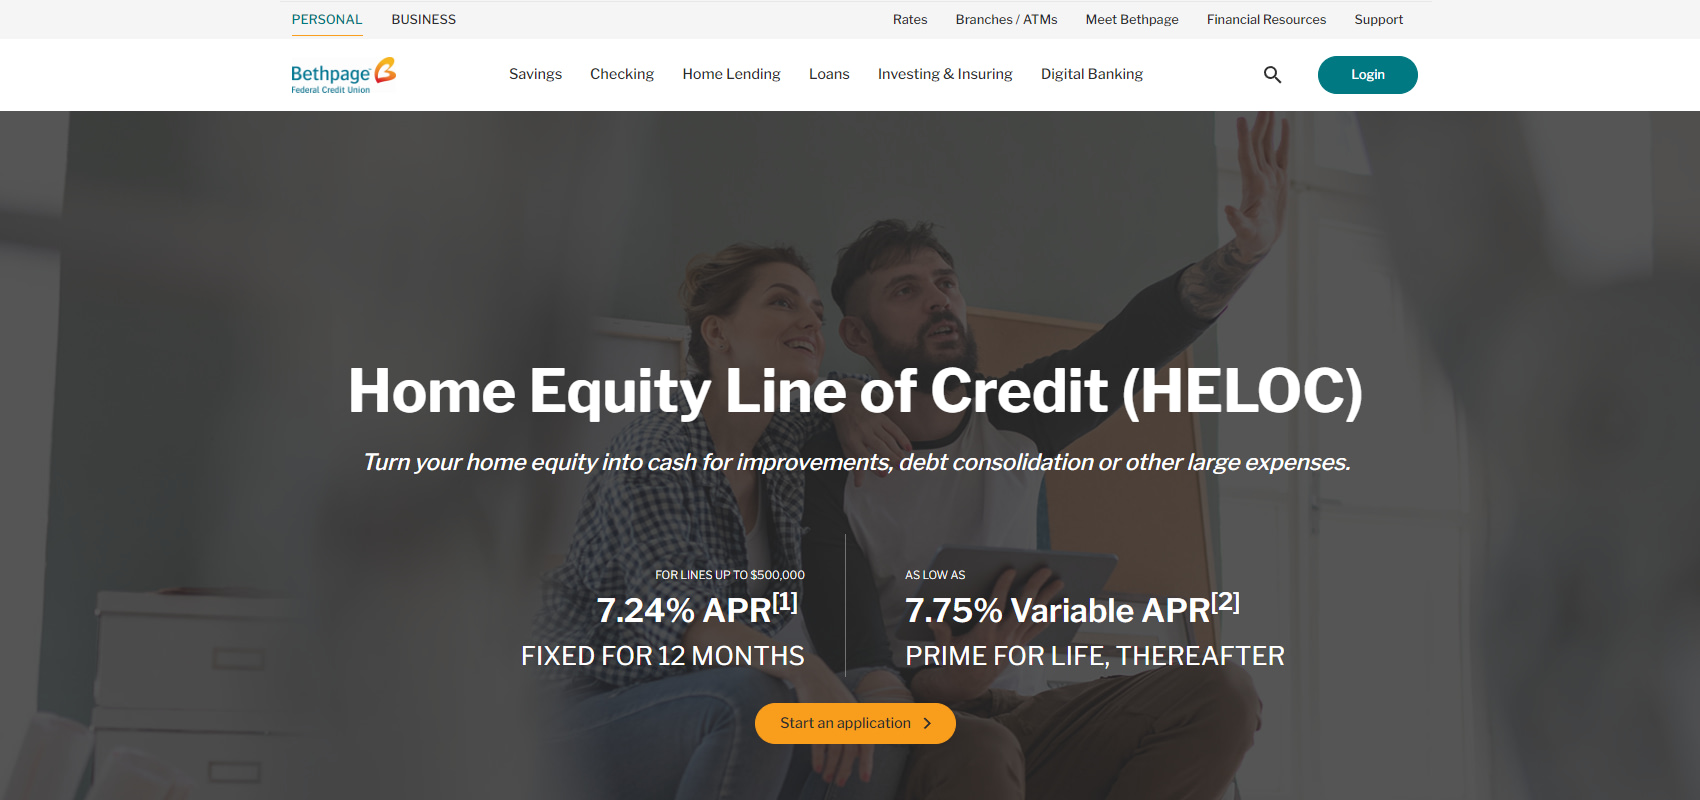
Bethpage Federal Credit Union: Best for Low Rates and Fees
Credit unions often outperform national banks because they are member-owned. Bethpage Federal Credit Union is frequently cited as a top choice for borrowers across the United States.
- Minimal Fees: They are known for having no closing costs on lines up to $500,000, no application fees, and no annual fees.
- Introductory Rates: Bethpage often offers a 12-month introductory rate that is significantly lower than the standard variable APR.
- Best For: Borrowers who are cost-conscious and willing to join a credit union (which often requires only a small deposit) to secure the lowest possible long-term costs.
PenFed Credit Union: Best for High Loan-to-Value (LTV)
PenFed (Pentagon Federal Credit Union) is open to anyone and is particularly competitive for those who have less equity but strong credit.
- High LTV Limits: While many lenders cap their total financing at 80% of the home's value, PenFed occasionally allows for a Combined Loan-to-Value (CLTV) ratio of up to 85% or 90% depending on the borrower's location and creditworthiness.
- Accessibility: Their digital platform is robust, bridging the gap between a traditional credit union and a modern fintech company.
- Best For: Homeowners who want to maximize the amount of equity they can tap into.
Comparison of Top 2026 HELOC Providers
The following table summarizes the key metrics for leading lenders as of mid-2026. These figures represent standard offerings for borrowers with excellent credit (740+).
| Lender | Best For | Max LTV | Typical Funding Time | Key Feature |
|---|---|---|---|---|
| Figure | Speed | 85% | 5–10 Days | Fully digital/Blockchain-backed |
| Bank of America | Loyalty Perks | 80% | 30–45 Days | Relationship rate discounts |
| Bethpage FCU | Lowest Fees | 80% | 20–30 Days | No closing costs on large lines |
| PenFed | High LTV | 90% | 15–25 Days | Competitive 90% CLTV options |
| Rocket Mortgage | Ease of Use | 80% | 10–20 Days | Superior mobile app experience |
Critical Factors for Comparing HELOC Offers
When evaluating these lenders, you must look at the specific terms of the agreement. The "best" lender on paper might be the most expensive if you do not understand the underlying mechanics of their HELOC product.
Variable vs. Fixed Rates
Most HELOCs are tied to the U.S. Prime Rate as published in the Wall Street Journal. The lender adds a "margin" to this rate (e.g., Prime + 1%). In 2026, many lenders offer a "fixed-rate option." This allows you to lock in the interest rate on a portion of your balance for a set term, such as 5, 10, or 20 years. This protects you if interest rates rise during your 10-year draw period.
Closing Costs and Annual Fees
Be wary of lenders that offer an ultra-low rate but make up for it with high closing costs. Some lenders charge for:
- Professional Appraisals: $400 to $800.
- Annual Membership Fees: $50 to $100.
- Inactivity Fees: Charged if you don't use the line.
- Early Disclosure Fees: Charged if you close the account within the first 2-3 years.
The best lenders in 2026, such as Bank of America and many credit unions, waive most of these fees to remain competitive in a crowded market.
Draw and Repayment Periods
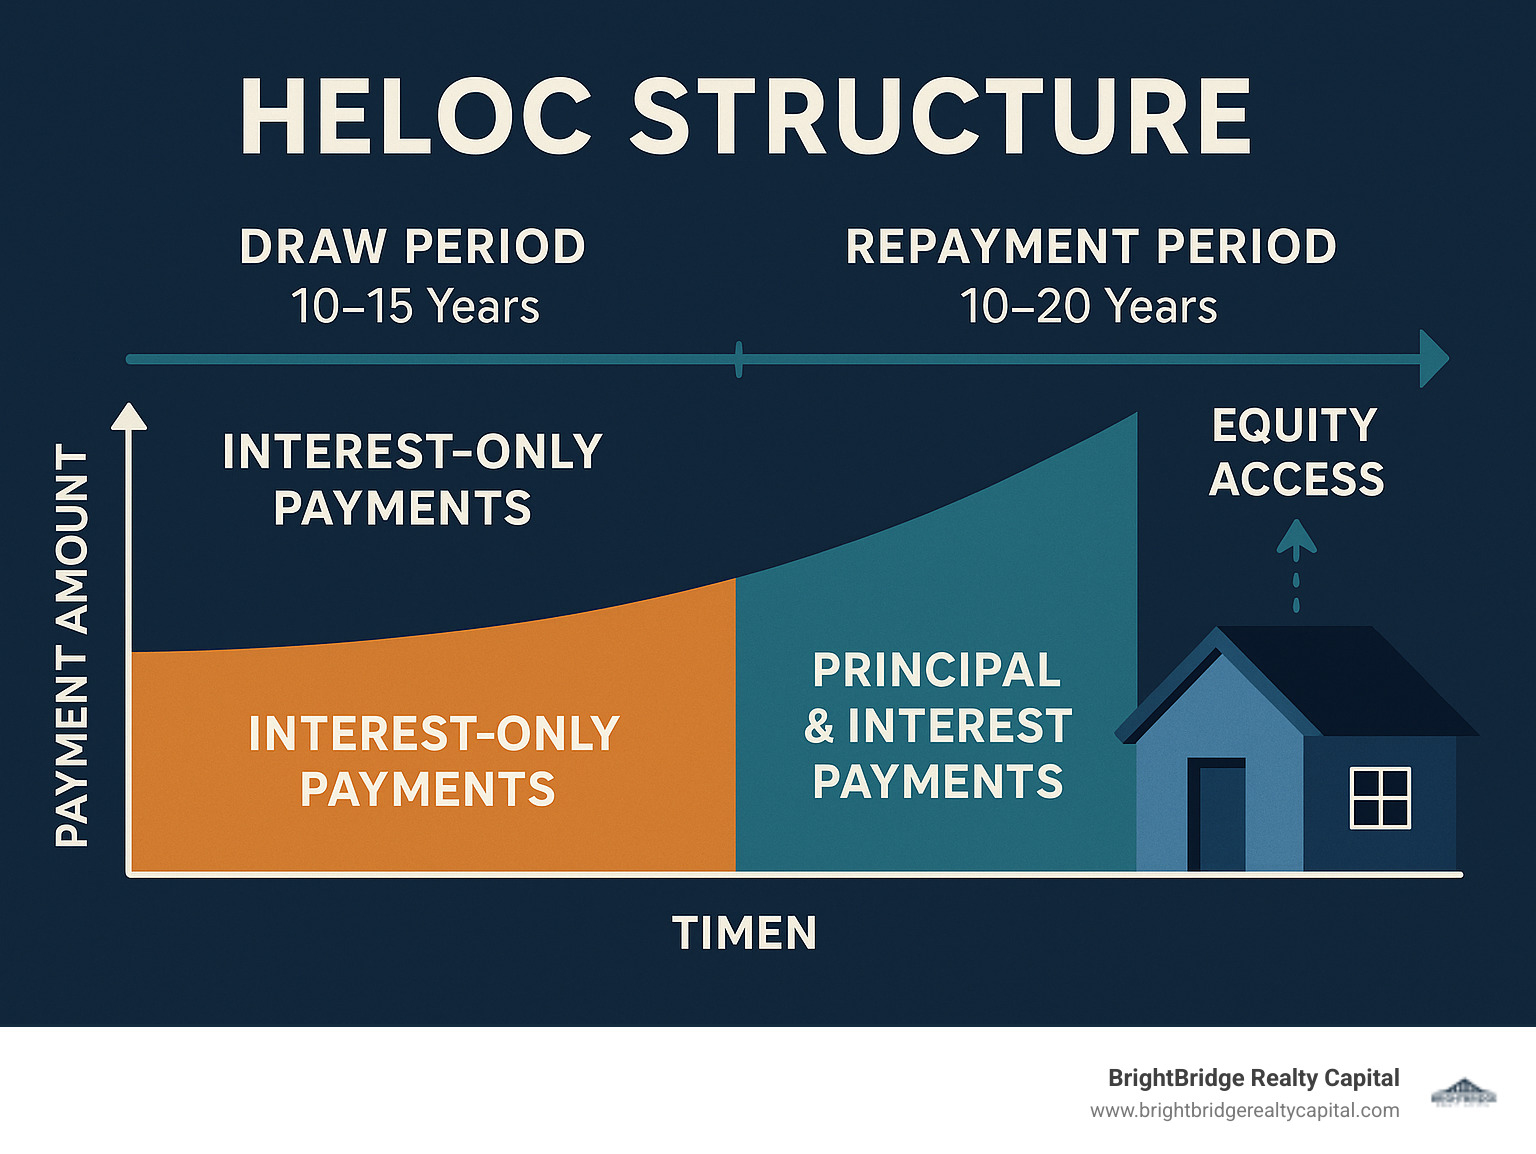
The standard HELOC has a 10-year draw period followed by a 20-year repayment period. During the draw period, you typically only have to pay interest on the amount you use. Once the repayment period begins, you must pay both principal and interest, which can lead to a significant "payment shock." Ensure your lender provides clear projections of what your payments will look like once the draw period ends.
Eligibility Requirements and Documentation
To qualify for the best rates from the lenders mentioned above, you generally need to meet several criteria. Requirements have become slightly more stringent in 2026 as lenders guard against property value fluctuations.
- Credit Score: While some lenders accept scores as low as 620, the "best" rates are reserved for those with a score of 740 or higher.
- Debt-to-Income (DTI) Ratio: Most lenders prefer a DTI below 43%, though some flexible lenders may go up to 50% if you have high cash reserves.
- Equity Buffer: You generally need to leave at least 15% to 20% equity in your home. For example, if your home is worth $500,000, your total debt (mortgage + HELOC) usually cannot exceed $400,000 to $425,000.
- Documentation: Expect to provide recent W-2s, pay stubs, tax returns (if self-employed), and a recent mortgage statement. Fintechs like Figure may verify this data instantly through a link to your bank account via services like Plaid.
Common Pitfalls to Avoid When Choosing a Lender
Even with a top-rated lender, borrowers can fall into traps if they aren't careful. One major mistake is failing to calculate the "Fully Indexed Rate." Lenders often advertise an introductory rate of 2.99% or 3.99% for the first six months. However, once that period expires, the rate jumps to the Prime Rate plus your margin. If the Prime Rate is 7% and your margin is 1%, your rate becomes 8% overnight.
Another pitfall is the Balloon Payment. While rare among the major lenders listed here, some smaller regional banks offer HELOCs where the entire balance is due at the end of the draw period. Always confirm that your HELOC converts to a traditional amortizing loan at the end of the 10-year mark.
Finally, consider the Total Cost of Credit. A lender offering a rate that is 0.25% higher but charges zero closing costs might actually be cheaper over five years than a lender with a lower rate but $2,000 in upfront fees, especially if you only plan to carry a small balance.
Strategies for Getting the Lowest HELOC Rate
To ensure you get the best possible offer in 2026, follow these expert strategies:
- Shop Three Lenders: Always get a quote from your current mortgage servicer, one national bank, and one credit union. They each use different risk models.
- Check Your "CLTV": If your Combined Loan-to-Value is exactly 80%, try to ask for a slightly smaller line of credit to bring it down to 79%. Lenders often have "rate triggers" where a 1% difference in equity can lower your interest rate by 0.25%.
- Improve Your Credit First: If your score is 730, taking a month to pay down credit card balances to get above 740 can save you thousands of dollars over the life of the HELOC.
- Ask About the Floor: Most HELOCs have an "interest rate floor," which is the lowest the rate can ever go. If the floor is high (e.g., 5%), you won't benefit if the economy enters a period of extremely low rates.
Frequently Asked Questions
Which lender is fastest for a HELOC in 2026?
Figure is currently the fastest lender in the industry, often providing approval and funding in under 10 days. This is achieved through an entirely digital process that avoids traditional, time-consuming appraisals in favor of data-driven valuations.
Can I get a HELOC with a 620 credit score?
Yes, but you likely won't get the "best" rates. Lenders like Rocket Mortgage and certain local credit unions are more lenient with credit scores, but they may limit your LTV to 75% or charge a higher margin over the prime rate.
Are there HELOC lenders that don't require an appraisal?
Most modern lenders, including Figure and Bank of America, use Automated Valuation Models (AVMs) for many properties. If the AVM can confidently determine your home's value based on recent local sales data, a traditional in-person appraisal is often waived.
Is interest on a HELOC tax-deductible in 2026?
According to the IRS, interest on home equity debt is generally only deductible if the funds are used to buy, build, or substantially improve the taxpayer’s home that secures the loan. If you use the money to pay off credit cards or buy a car, the interest is typically not deductible.
What is a "Fixed-Rate Lock" on a HELOC?
A fixed-rate lock is a feature offered by lenders like Bank of America and PNC that allows you to convert a portion of your variable-rate balance into a fixed-rate loan with a set repayment term. This provides the flexibility of a HELOC with the stability of a home equity loan.
Final Recommendation
For the majority of homeowners in 2026, Bethpage Federal Credit Union offers the best balance of low interest rates and minimal fees, making it the top choice for long-term value. However, if your primary concern is receiving funds immediately for an urgent project, Figure is the superior option due to its streamlined digital interface and rapid closing times. Before committing, always request a "Truth in Lending" disclosure from at least two lenders to compare the APR and total estimated fees over the life of the loan.
Image Gallery
Select an image to open it in a new tab.



Declan O'Connor
Higher Education and Campus Culture Reporter
