Understanding Drive NJ Auto Insurance Company: Coverage, Claims, and Policy Management
Drive New Jersey Insurance Company is an active underwriting subsidiary of The Progressive Corporation that issues personal and commercial auto insurance policies in New Jersey. Policies underwritten by Drive New Jersey are serviced through Progressive’s digital network and independent insurance agents, offering liability, comprehensive, collision, and state-mandated Personal Injury Protection (PIP) coverages.
What Is Drive New Jersey Insurance Company?
If you reviewed your motor vehicle insurance identification card, declarations page, or billing invoice in New Jersey and noticed the legal entity listed as Drive New Jersey Insurance Company, you are looking at one of the primary underwriting subsidiaries of The Progressive Corporation.
Progressive operates through dozens of distinct, state-specific insurance subsidiaries to comply with local insurance laws and regulatory frameworks. Drive New Jersey Insurance Company is licensed and regulated by the New Jersey Department of Banking and Insurance (DOBI) to sell and underwrite automobile insurance policies across the state.
- The Progressive Corporation (Parent Company)
- Drive New Jersey Insurance Company (NJ Licensed Underwriting Entity)
- Independent Agents Distribution Channel
- Direct Online/Phone Progressive Portal
- Drive New Jersey Insurance Company (NJ Licensed Underwriting Entity)
Historically, Progressive established the "Drive Insurance from Progressive" brand name during the mid-2000s specifically to market products sold through local independent insurance brokers. While marketing branding often emphasizes the parent brand name "Progressive," the actual legal contract, policy liability, and financial obligations remain with Drive New Jersey Insurance Company for covered policyholders in the state.
Understanding this distinction is vital when filing claims, submitting official legal documentation, responding to queries from the New Jersey Motor Vehicle Commission (NJ MVC), or identifying your insurer after a motor vehicle collision.
New Jersey Auto Insurance Laws and Statutory Requirements
Driving in New Jersey requires navigating one of the most highly regulated and unique auto insurance systems in the United States. Drive New Jersey Insurance Company must structure its policy options to conform strictly to New Jersey statutes.
New Jersey operates under a mandatory "no-fault" auto insurance structure regarding medical treatment following an accident, coupled with statutory choices regarding policy types and tort options.
1. Basic Policy vs. Standard Policy
New Jersey law permits drivers to select between two fundamentally different policy types:
- The Standard Policy: Provides comprehensive protection and is selected by the vast majority of drivers. It offers higher bodily injury liability limits, flexible Personal Injury Protection (PIP) limits, optional comprehensive and collision coverages, and choices regarding your right to sue for pain and suffering.
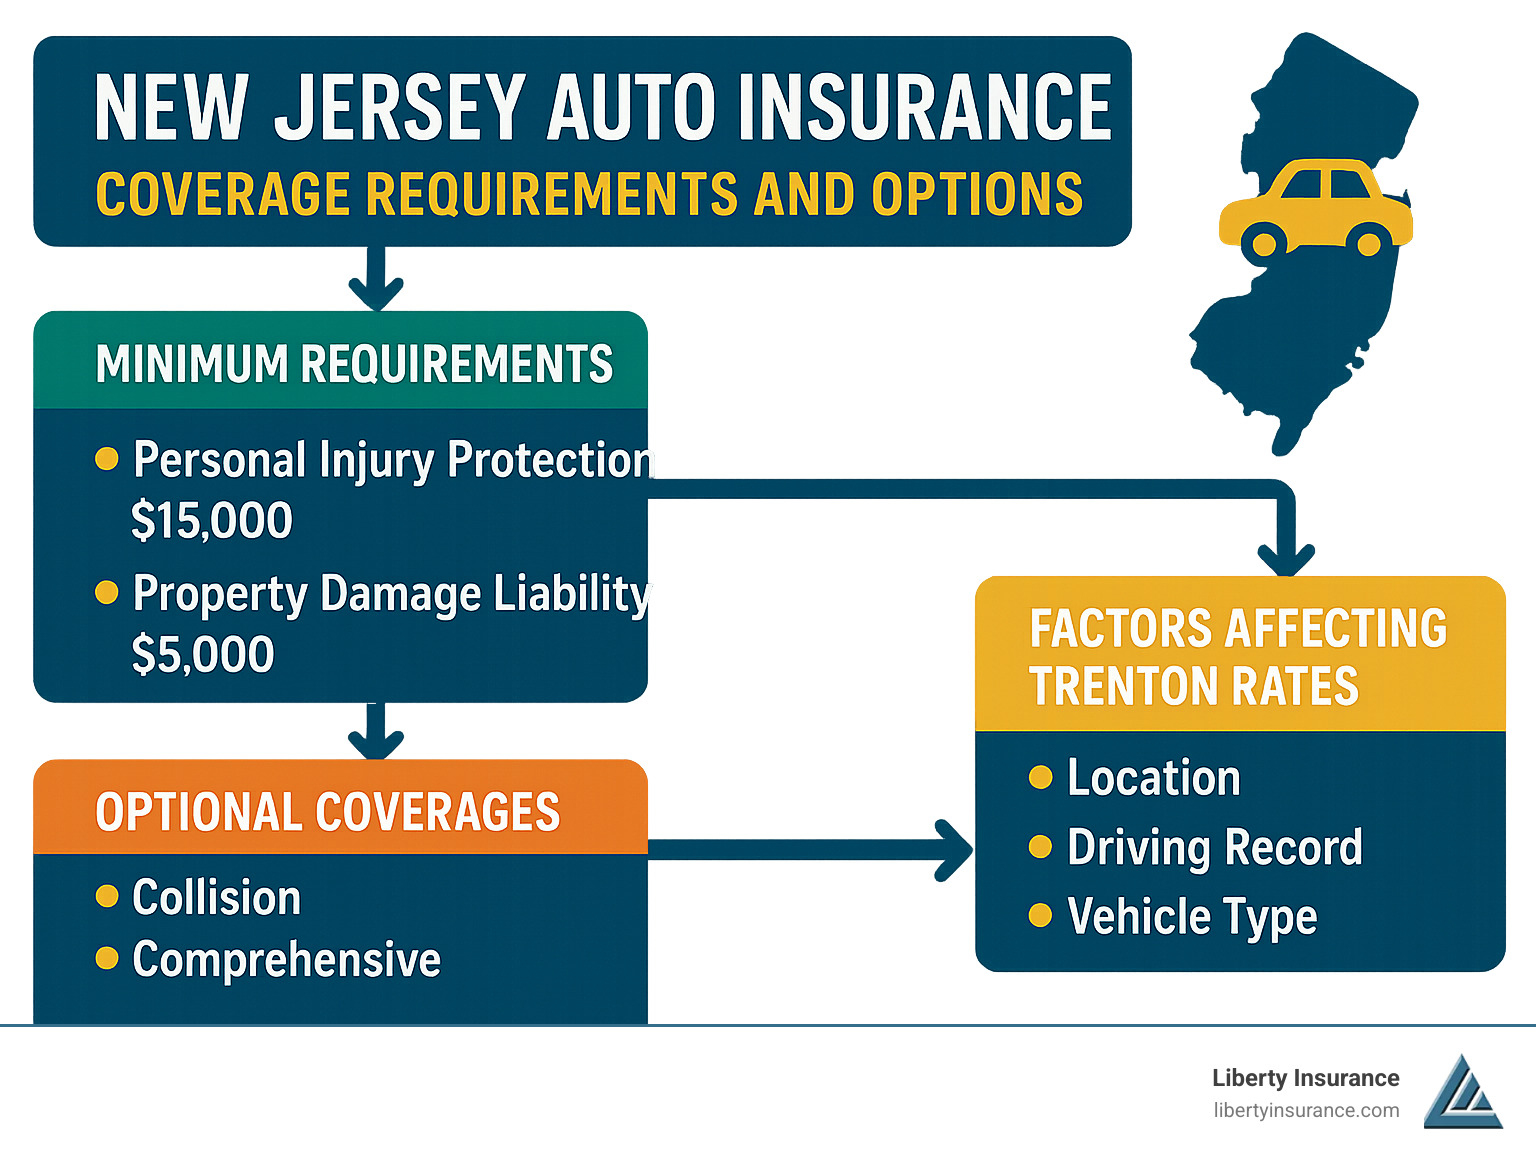
- The Basic Policy: Offers a stripped-down, lower-cost alternative designed for individuals with limited assets. It provides limited PIP coverage ($15,000 per person, up to $250,000 for specific severe brain or spinal cord injuries) and $10,000 in property damage liability per accident, but typically excludes bodily injury liability coverage unless added as an option.
2. Statutory Minimum Liability Limits
For standard policies in New Jersey, minimum liability requirements have increased to keep pace with medical inflation and vehicle repair costs. Effective state regulations set minimum liability thresholds for standard auto policies at:
- Bodily Injury Liability: $35,000 per person / $70,000 per accident
- Property Damage Liability: $25,000 per accident
Drive New Jersey Insurance Company writes standard policies meeting or exceeding these statutory minimums, alongside customizable liability limits up to $250,000/$500,000 or combined single limits for higher-net-worth policyholders.
| Coverage Type | Mandatory Minimum |
|---|---|
| Bodily Injury (Per Person) | $35,000 |
| Bodily Injury (Per Accident) | $70,000 |
| Property Damage (Per Accident) | $25,000 |
| Personal Injury Protection (Standard Limit) | $15,000 - $250,000 |
3. Personal Injury Protection (PIP) Choices
In New Jersey, PIP covers medical expenses for you and qualified members of your household if injured in an auto accident, regardless of who caused the collision. When structuring a policy underwritten by Drive New Jersey Insurance Company, policyholders make two key choices regarding PIP:
- Medical Limit Choice: Standard PIP default coverage is $250,000, though policyholders can select reduced limits ($15,000, $50,000, $75,000, or $150,000) in exchange for lower premium rates.
- Primary Health Insurer Option: You can select your private health insurance provider as the primary payer for auto accident injuries, which provides a premium discount on the PIP portion of your policy. If your health insurer does not cover motor vehicle injuries (e.g., Medicare or Medicaid), Drive NJ must remain the primary PIP carrier.
4. Tort Rights (Right to Sue Options)
New Jersey drivers must choose between two tort options on their declaration page, directly affecting their ability to sue an at-fault driver for non-economic damages (such as pain and suffering):
- Limitation on Lawsuit Option (Verbal Threshold): You agree to restrict your right to sue an at-fault driver for non-economic pain and suffering unless your injury falls into one of six specific legal categories: death, dismemberment, significant disfigurement, displaced fractures, loss of a fetus, or permanent injury within a reasonable degree of medical probability. This choice results in a reduced policy premium.
- No Limitation on Lawsuit Option (Zero Threshold): You retain the unrestricted legal right to sue an at-fault driver for any injury caused by a crash, regardless of severity. Selecting this option increases policy premiums substantially.
Core Coverage Options Underwritten by Drive NJ
Policies issued by Drive New Jersey Insurance Company through Progressive incorporate various standard and supplemental coverage features. Designing an effective policy requires matching these options to your vehicle value, driving habits, and risk tolerance.
- Mandatory Coverages
- Bodily Injury Liability
- Property Damage Liability
- Personal Injury Protection
- Uninsured/Underinsured Motorist
- Physical Damage
- Collision Coverage
- Comprehensive Coverage
- Custom Parts & Equipment
- Supplemental Add-Ons
- Roadside Assistance
- Rental Reimbursement
- Gap Insurance
- Trip Interruption
Liability Coverage
- Bodily Injury Liability: Pays for medical bills, loss of income, and legal defense costs if you cause an accident resulting in injury or death to another party.
- Property Damage Liability: Covers repairs or replacement costs for damaged property—such as another driver's vehicle, utility poles, guardrails, or buildings—caused by your vehicle.
Physical Damage Coverages
- Collision Coverage: Covers physical damage to your insured vehicle resulting from a collision with another car, rollover, or impact with an object (e.g., tree, fence, or guardrail), subject to your selected deductible ($250, $500, $1,000, or higher).
- Comprehensive Coverage: Protects against non-collision physical loss or damage, including theft, vandalism, weather damage (hail, flooding, wind), hitting an animal (such as a deer), fire, or windshield breakage.
Uninsured and Underinsured Motorist Coverage (UM/UIM)
Despite strict mandatory coverage laws, uninsured drivers remain on the road. UM/UIM coverage protects you, your passenger, and your vehicle if you are hit by a driver who carries no insurance or whose liability limits are insufficient to cover your total damages. Under New Jersey regulations, standard policies must include UM/UIM limits equal to or lower than your chosen Bodily Injury liability limits.
Optional Add-Ons
Drive New Jersey policyholders can customize their policies with several specialized protections:
- Loan/Lease Payoff (Gap Insurance): Pays the difference between the actual cash value (ACV) of a totaled vehicle and the remaining balance owed on your loan or lease, up to 25% of the vehicle value.
- Roadside Assistance: Provides 24/7 towing, battery jump-starts, flat-tire changes, fuel delivery, and lockout services across New Jersey and nationwide.
- Rental Car Reimbursement: Pays for a rental vehicle up to daily and total policy caps (e.g., $30/day up to $900 total) while your primary covered vehicle undergoes repairs following an insured loss.
- Custom Parts and Equipment (CPE) Coverage: Protects aftermarket equipment installed on your vehicle, such as custom rims, modified audio systems, or specialized paint work.
How to Get Quotes and Manage Policies
Because Drive New Jersey Insurance Company operates within the broader Progressive ecosystem, customers have multiple paths for securing quotes, modifying coverage, and managing administrative tasks.
1. Obtaining Quotes
You can request quotes for a policy underwritten by Drive New Jersey Insurance Company through:
- Direct Digital Channels: Submitting vehicle details, driver profiles, and address information via Progressive's online platform.
- Independent Insurance Agencies: Working with licensed New Jersey insurance brokers who write policies through Drive New Jersey alongside other competitive carriers.
- Telephone Service: Requesting quotes directly from customer service representatives.
2. Managing Policy Documentation
Once a policy is active, administrative management is centralized under Progressive's portal. You can access policy documents using:
- The Progressive Mobile App: Downloadable digital insurance cards accepted by law enforcement and the NJ MVC during vehicle registrations or roadside inspections.
- Online Account Dashboard: Accessing declarations pages, making policy endorsements (adding drivers, removing vehicles, changing deductibles), and requesting physical replacement cards.
- Paper Statements: Mailed policy documentation sent prior to annual or semi-annual renewal dates.
Comprehensive Policy Comparison Matrix
Selecting policy configurations involves balancing cost, asset protection, and legal exposure under New Jersey law. The table below outlines typical structural choices available through Drive New Jersey Insurance Company:
| Policy Element | Basic Policy Framework | Standard Policy (Minimum Limits) | Standard Policy (Enhanced Protection) |
|---|---|---|---|
| Primary Target Audience | High-risk drivers, minimal personal assets | Price-sensitive drivers seeking basic legal compliance | Drivers seeking comprehensive asset protection |
| Bodily Injury Liability | None (Optional $10k per accident available) | $35,000 / $70,000 | $100,000 / $300,000 or $250,000 / $500,000 |
| Property Damage Liability | $10,000 per accident | $25,000 per accident | $50,000 or $100,000 per accident |
| PIP Medical Coverage | $15,000 standard ($250k for brain/spinal) | $15,000 to $250,000 (Selectable) | $250,000 (Maximum default protection) |
| Tort Right Choice | Limitation on Lawsuit (Mandatory) | Choice of Limitation or No Limitation | Choice of Limitation or No Limitation |
| Collision & Comprehensive | Not Available | Optional (High Deductible) | Included ($250 - $500 Deductible) |
| UM/UIM Coverage | Not Included | Included (Matches BI Limits) | Included (Matches Higher BI Limits) |
| Roadside / Rental Care | Excluded | Optional Add-on | Included Add-on |
Claims Process and Accident Reporting
In the event of an accident, vehicle damage, or bodily injury in New Jersey, prompt and accurate filing is critical to ensure proper claims resolution and PIP processing.
- Vehicle Damage Claim
- Incident Report (App/Phone/Online)
- Adjuster Assessment / Photos
- Shop Estimate / Concierge Service
- Direct Payment to Repair Facility
- PIP Medical Claim
- Medical Treatment Initiation
- PIP Claim Number Assignment
- Decision Point/Pre-Certification
- Provider Bill Settlement
Step-by-Step Claim Filing
- Immediate Scene Safety & Documentation: Ensure safety, contact local law enforcement to obtain a police crash report, exchange driver and insurance information, and photograph vehicle positions, skid marks, damage, and license plates.
- Initial Claim Notice: Submit claim details via Progressive's mobile application, online account dashboard, or by calling the dedicated toll-free claims hotline (1-800-PROGRESSIVE / 1-800-776-4737). Identify Drive New Jersey Insurance Company as your named policy entity when requested.
- Adjuster Assignment & Damage Inspection: A physical or virtual claims adjuster evaluates vehicle damage, reviews photo submissions, reviews the official police report, and prepares a detailed repair estimate.
- Selecting Repair Facilities: You retain the legal right in New Jersey to repair your vehicle at any licensed repair facility. Alternatively, choosing a repair center within Progressive's network provides guaranteed workmanship for as long as you own or lease the vehicle.
- PIP Medical Claims Management: If you or your passengers sustain bodily injuries, a separate PIP claim file is opened. Medical care providers must follow New Jersey's Decision Point Review and pre-certification protocols, submitting proposed treatment plans and medical documentation to the carrier for review before non-emergency procedures, MRI scans, or physical therapy regimens are approved.
Factors Influencing Drive NJ Premium Rates
Automobile insurance premiums calculated by Drive New Jersey Insurance Company rely on risk metrics approved by the New Jersey Department of Banking and Insurance. Factors impacting your final quote include:
- Driving Record & History: Accidents, moving violations, speeding tickets, and points assessed on your NJ driver's license directly elevate policy pricing over a rolling 3-to-5-year calculation window.
- Geographic Risk Tiering: Premium structures vary significantly based on your primary garage zip code. Urban areas with higher population density and traffic congestion (such as Newark, Jersey City, or Paterson) generally incur higher rates than rural communities in Sussex or Salem counties due to statistical collision risks and theft rates.
- Vehicle Characteristics: Year, make, model, original invoice value, safety score ratings, and historical repair costs directly impact collision and comprehensive premium pricing.
- Credit-Based Insurance Scores: New Jersey allows insurance companies to consider credit history as a rating variable when establishing initial risk tiers, provided factors comply with state consumer regulations.
- Coverage Limits and Deductibles: Choosing higher liability coverage limits or selecting lower comprehensive/collision deductibles increases baseline premiums.
- Annual Mileage: Vehicles driven fewer miles annually (e.g., under 7,500 miles) often qualify for reduced rating tiers compared to vehicles used for lengthy daily commutes on major highways like the Garden State Parkway or New Jersey Turnpike.
Progressive Discounts Available to Drive NJ Policyholders
| Program / Feature | Details & Eligibility |
|---|---|
| Snapshot® Telematics | Rates based on actual driving |
| Multi-Policy (Bundling) | Home, renters, condo combo |
| Multi-Vehicle | Multiple cars on one policy |
| Continuous Coverage | No lapses in prior insurance |
| Good Student | Full-time students with B+ avg |
| Paperless & EFT | Auto-pay & digital billing |
- Snapshot® Telematics: A usage-based program tracking real-time driving behaviors—such as hard braking, rapid acceleration, late-night driving, and mobile phone usage while driving—via a plug-in OBD-II device or mobile app. Safe driving habits yield rate reductions, though risky driving behaviors can trigger rate increases.
- Multi-Policy Bundling: Combining your auto coverage with home, renters, condo, or umbrella policies serviced through Progressive or its affiliated network partners unlocks multi-product savings.
- Multi-Car Discounts: Insuring more than one vehicle on the same Drive New Jersey policy provides savings across covered vehicles.
- Paperless and Automatic Payment Discounts: Opting for electronic document delivery (e-delivery) and automatic monthly withdrawals (EFT) lowers processing costs and yields instant billing savings.
Troubleshooting Common Issues and DMV Verification
1. Insurance Verification and NJ MVC Compliance
New Jersey maintains strict digital monitoring systems linking insurance companies directly to the NJ MVC database. Drive New Jersey Insurance Company submits real-time policy updates, inclusions, and cancellations directly to state authorities.
- Lapses in Coverage: If a policy cancels or lapses due to non-payment, Drive NJ notifies the MVC. The state will mail an insurance verification notice requiring proof of replacement coverage. Failure to maintain continuous liability insurance can result in driver's license suspension, registration revocation, court fines, and mandatory restoration fees.
- Insurance ID Cards: Always carry a printed copy or verified electronic version of your Drive New Jersey Insurance card inside the vehicle. The document displays the statutory company code (NAIC number), policy number, effective date, and covered VIN.
- Drive NJ Policy Lapses
- Automatic Electronic Notice to NJ MVC
- MVC Issues Verification Demand Letter
- License Suspension Risk
- Registration Revocation
- Mandatory Court Fines
- MVC Issues Verification Demand Letter
- Automatic Electronic Notice to NJ MVC
2. Disputing Claims Estimates or Deductible Application
If an adjuster’s damage appraisal does not match a repair facility's itemized costs, an official supplemental claim estimate must be submitted. The repair facility works directly with Drive NJ's claims unit to inspect hidden damage discovered during teardown and issue supplemental repair authorizations.
3. Policy Non-Renewals or Underwriting Surcharges
Under New Jersey insurance statutes, an insurer may non-renew a policy or apply underwriting surcharges under specific legal conditions—such as accumulating a set number of driving points, being involved in multiple at-fault accidents within a specified timeframe, or committing insurance fraud. If you receive a notice of non-renewal from Drive New Jersey Insurance Company, you have the right to request a formal review or seek replacement coverage through the voluntary market or the New Jersey Personal Automobile Insurance Plan (NJPAIP) if high-risk status prevents standard market placement.
Frequently Asked Questions
Is Drive New Jersey Insurance Company the same as Progressive?
Yes. Drive New Jersey Insurance Company is an official, state-licensed insurance underwriting subsidiary of The Progressive Corporation. Policies issued under the Drive New Jersey entity are branded, sold, and serviced through Progressive's online platforms, phone centers, and independent agent network.
How do I locate my insurance company code (NAIC) for the NJ DMV?
Your insurance card lists the specific 5-digit National Association of Insurance Commissioners (NAIC) company code assigned to Drive New Jersey Insurance Company. You can find this code printed directly on your physical or digital auto insurance identification card issued by Progressive.
Can I drop Personal Injury Protection (PIP) in New Jersey to save money?
No. Personal Injury Protection (PIP) is a mandatory statutory requirement for all auto policies written in New Jersey. However, you can manage your policy cost by selecting lower medical limit options (such as $15,000 instead of $250,000) or designating your primary personal health insurance as the primary payer for medical claims, where eligible.
What happens if I get into an accident with an uninsured driver in New Jersey?
If you hold a Standard Policy underwritten by Drive New Jersey Insurance Company, your mandatory Uninsured Motorist (UM) coverage will pay for bodily injury and property damage caused by an uninsured or hit-and-run driver, up to your policy's UM limits and subject to applicable deductibles.
How do I file a PIP claim after a car crash in New Jersey?
Contact Progressive directly via telephone or online to report the collision and request the opening of a PIP medical claim file. You will receive a unique PIP claim number to provide to your medical care providers. Your treating physicians must follow New Jersey's Decision Point Review pre-certification procedures for ongoing treatment approvals.
Summary and Next Steps
Drive New Jersey Insurance Company serves as Progressive's operational legal entity for issuing auto policies across New Jersey. Understanding how this entity operates within New Jersey’s auto insurance framework ensures you maintain full legal compliance and appropriate financial protection.
If you currently hold or are evaluating a policy underwritten by Drive New Jersey Insurance Company, consider taking the following actions:
- Review Declarations Pages: Check your current insurance card and policy declarations to verify whether your policy is underwritten by Drive New Jersey Insurance Company.
- Evaluate Tort and PIP Choices: Reassess your Personal Injury Protection (PIP) medical limits and Right to Sue options (Limitation on Lawsuit vs. No Limitation) to ensure your selections match your medical coverage needs and asset risk profile.
- Confirm Legal Liability Limits: Verify that your Bodily Injury and Property Damage liability limits meet or exceed current New Jersey statutory minimums ($35k/$70k/$25k).
- Audit Qualified Discounts: Check your Progressive account dashboard to verify that all applicable discounts—such as continuous coverage, bundling, good student savings, or Snapshot telematics participation—are active.
- Maintain Continuous Proof of Coverage: Ensure your active digital or printed insurance card is stored in your vehicle at all times to prevent registration disputes with the New Jersey Motor Vehicle Commission.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
