
PFCU term life insurance is a financial protection product offered to members of the Philadelphia Federal Credit Union (PFCU), primarily through its partnership with TruStage. It provides a tax-free death benefit to beneficiaries if the policyholder passes away during a specified "term" or time period. Unlike permanent insurance, it is designed for temporary needs, such as covering a mortgage or providing income replacement during child-rearing years.
Life insurance is a cornerstone of a sound financial plan, yet for many members of credit unions, the process of selecting the right coverage can feel overwhelming. When looking at PFCU term life insurance, it is essential to recognize that credit unions operate differently than traditional big-box banks. Their focus on member-owned benefits often extends to the insurance products they vet and offer. As of 2026, term life insurance remains one of the most cost-effective ways to secure a high amount of coverage for a relatively low monthly premium.
This guide explores the intricacies of PFCU term life insurance, detailing how the policies work, the eligibility requirements for members, the application process, and the specific advantages and limitations of choosing a credit union-backed policy over a commercial alternative.
What is PFCU Term Life Insurance?
PFCU term life insurance is a contract between an insured member and an insurance provider—usually TruStage—where the member pays a regular premium in exchange for a guaranteed death benefit. The "term" refers to the length of the policy, which typically ranges from 1, 5, 10, 20, or even 30 years.
If the insured individual passes away while the policy is active, the designated beneficiaries receive a lump-sum payment. This money can be used for any purpose, from funeral expenses and medical bills to long-term needs like college tuition for children or paying off a home loan. If the policyholder survives the term, the coverage simply expires unless it is renewed or converted into a permanent policy.
The primary appeal of term life insurance through PFCU is its simplicity. Because it does not include a "cash value" or investment component—unlike whole life insurance—every dollar of the premium goes toward the cost of the insurance and administrative fees. This makes it significantly more affordable than permanent options, allowing families to purchase larger amounts of coverage when they need it most.
The Role of Philadelphia Federal Credit Union and TruStage
It is a common misconception that the credit union itself acts as the insurance company. In reality, Philadelphia Federal Credit Union (PFCU) partners with the TruStage Insurance Agency, which is underwritten by the CMFG Life Insurance Company.
TruStage has a decades-long history of working exclusively with credit union members. This partnership is designed to offer simplified products that align with the credit union philosophy of "people helping people." For a PFCU member in 2026, this means:
- Affinity Pricing: Members may have access to rates that are competitive because of the collective bargaining power of the credit union membership base.
- Seamless Integration: Often, premiums can be automatically deducted from a PFCU checking or savings account, reducing the risk of a policy lapse due to missed payments.
- Vetted Reliability: PFCU performs due diligence on its partners, ensuring that the insurance companies backing these policies have strong financial strength ratings from agencies like A.M. Best.

Eligibility and Membership Requirements
To access term life insurance through PFCU, the primary requirement is membership within the credit union. In 2026, Philadelphia Federal Credit Union maintains specific eligibility criteria for joining:
- Geographic Connection: Living, working, worshipping, or attending school in various Philadelphia neighborhoods or surrounding areas (such as portions of Montgomery or Delaware counties).
- Employer Affiliation: Employees of hundreds of participating "Select Employee Groups" (SEGs) are eligible to join.
- Family Membership: If an immediate family member is already a PFCU member, you are typically eligible to join regardless of where you live or work.
Once a membership is established with at least a small deposit into a savings account, the member is eligible to apply for the insurance products. It is important to note that the insurance coverage itself is portable; if you leave your job or move away from Philadelphia, you can generally keep your term life policy as long as you continue to pay the premiums.
Key Features of PFCU Term Life Policies
When evaluating a term life policy through PFCU, several features stand out as being particularly relevant to modern consumers in 2026.
Fixed Premiums and Coverage
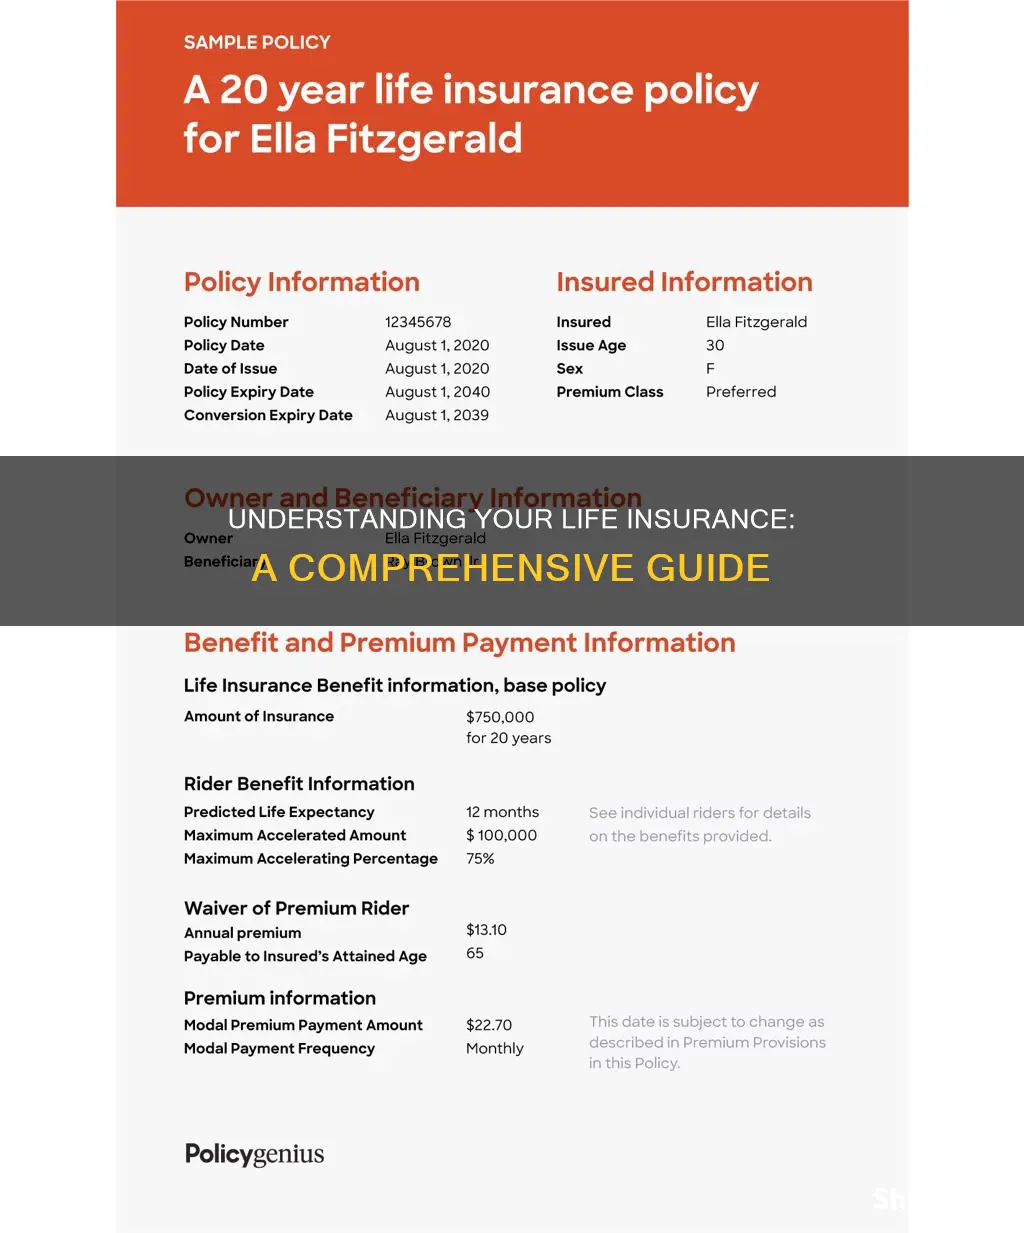
Most term life policies offered through the credit union feature "level premiums." This means that once you are approved for a policy, your monthly or annual cost will not increase for the duration of the term. For example, if you secure a 20-year term at $25 per month, you will pay exactly $25 per month until the 20 years have passed, regardless of changes to your health.
Simplified Issue Options
One of the most popular aspects of TruStage term life insurance through PFCU is the "Simplified Issue" process. In many cases, members can apply for coverage without undergoing a physical medical exam. Instead, the underwriting process relies on a series of health questions on the application and a review of electronic records (such as prescription history databases). This can lead to a policy being issued in a matter of days rather than the weeks or months required for traditional fully underwritten policies.
Renewal and Conversion Rights
Many PFCU term policies include a "renewal" clause, allowing the policyholder to extend coverage on a year-to-year basis after the initial term expires, though often at a significantly higher cost. More importantly, some policies offer a "conversion rider," which allows the member to switch from term life to whole life insurance without having to prove their insurability again. This is a vital safeguard if a member develops a chronic illness near the end of their term.
Comparing Term Life vs. Whole Life Insurance at PFCU
To understand if term insurance is the right choice, it helps to compare it with the whole life options also available to PFCU members.
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Duration | Specific period (e.g., 10, 20, 30 years) | Entire lifetime |
| Cash Value | None | Builds over time |
| Initial Cost | Generally lower | Generally higher |
| Premium Stability | Fixed for the term | Fixed for life |
| Main Goal | Income replacement / Debt protection | Estate planning / Final expenses |
| Complexity | Simple and straightforward | Moderate to high |
In 2026, financial advisors often recommend term life for families who need to protect their mortgage or children's education. Whole life is typically reserved for those who have lifelong dependents (such as a child with special needs) or those who have maximized other tax-advantaged investment vehicles.
The Cost of PFCU Term Life Insurance
The cost of term life insurance is determined by "underwriting," the process of assessing risk. While PFCU members benefit from affinity programs, several individual factors will dictate the final premium:
- Age: This is the most significant factor. Purchasing a policy at age 30 is significantly cheaper than at age 50.
- Health History: Even in simplified issue policies, a history of heart disease, diabetes, or cancer will impact eligibility and pricing.
- Tobacco Use: Smokers or those using nicotine products can expect to pay two to three times more than non-smokers.
- Coverage Amount: A $500,000 policy will naturally cost more than a $100,000 policy, though the cost per thousand dollars of coverage often decreases as the total amount increases.
As of 2026, a healthy 35-year-old non-smoker might find a $250,000 20-year term policy through a credit union partner for approximately $15 to $25 per month, though rates vary by state and specific underwriting guidelines.
How to Apply for PFCU Term Life Insurance
The application process has been streamlined to accommodate the digital preferences of members in 2026.
- Verification of Membership: Ensure your PFCU account is in good standing. You will likely need your member number to begin the application.
- Online Quote: Visit the PFCU website and navigate to the insurance or "Member Benefits" section. This will redirect you to the TruStage portal for PFCU.
- Needs Assessment: Use an online calculator to determine how much coverage you actually need. A common rule of thumb is 10 to 12 times your annual income.
- Complete the Application: Provide personal details, beneficiary information, and answer the health questionnaire.
- Underwriting Review: The insurance company will review your data. If you applied for a simplified issue policy, you might receive an instant decision. If additional information is needed, a representative may contact you.
- Policy Delivery: Once approved, you will receive your policy documents electronically or via mail. Ensure you share the location of these documents with your beneficiaries.
Common Mistakes to Avoid
When securing term life insurance through a credit union, members often fall into a few common traps:
- Underinsuring: Many people choose a round number like $100,000 without realizing that this amount may only cover two or three years of expenses for a grieving family.
- Relying Solely on Employer Coverage: While many PFCU members have life insurance through their jobs, that coverage usually ends if they leave the company. A private policy through PFCU provides continuity.
- Waiting Too Long: Because premiums are based on age, every year you delay the application increases the lifetime cost of the policy.
- Neglecting Beneficiary Updates: Life changes like divorce, marriage, or the birth of a child require updates to the policy's beneficiary designations. Life insurance payouts generally bypass the probate process, but only if the beneficiary information is current and accurate.
Claiming the Death Benefit: The Beneficiary's Path
One of the most critical aspects of "understanding" insurance is knowing how it pays out. For a PFCU term life policy, the process for a beneficiary in 2026 typically involves:
- Notification: The beneficiary contacts TruStage or PFCU to report the death.
- Documentation: The insurer will require a certified copy of the death certificate and a completed claim form.
- Review: The insurer verifies the policy was active and that the cause of death is not excluded (most policies have a two-year "contestability period" regarding suicide or material misrepresentation on the application).
- Payout: Once approved, the funds are typically distributed within 30 days. Many credit unions offer the option to have the funds deposited directly into a PFCU account for immediate access.
FAQ: Frequently Asked Questions
Can I cancel my PFCU term life insurance at any time?
Yes. Term life insurance is a voluntary product. If you decide you no longer need the coverage or find a different policy, you can stop paying the premiums. There are no "surrender charges" for term life insurance because it does not have a cash value. Once payments stop, the coverage simply ceases at the end of the paid period.
Does the premium increase as I get older?
If you have a "Level Term" policy, your premium is locked in for the duration of the term (e.g., 10 or 20 years). If you have an "Annually Renewable Term" policy, the premium will increase each year as you age. Most PFCU members prefer the stability of level term policies to help with long-term budgeting.
Is the death benefit from a PFCU policy taxable?
In most cases, life insurance death benefits are not subject to federal income tax. The beneficiaries receive the full amount specified in the policy. However, if the payout is exceptionally large and becomes part of a very high-value estate, it could be subject to estate taxes, though this affects a very small percentage of policyholders in 2026.
What happens if I move out of Pennsylvania?
Your PFCU membership and your insurance policy are not tied to your residency in Philadelphia once they are established. As long as you maintain your account and continue to pay your insurance premiums, your coverage remains in force regardless of where you move within the United States.
Are there exclusions in the policy?
Most term life policies have very few exclusions. The most common is the "suicide clause," which typically states that if the insured commits suicide within the first two years of the policy, the death benefit will not be paid (though premiums are usually returned). Beyond that, as long as the application was honest, the policy must pay out for almost any cause of death, including illness, accidents, or natural causes.
Final Recommendation for PFCU Members
Understanding PFCU term life insurance is about recognizing that this product is a tool for risk management rather than an investment. For members of the Philadelphia Federal Credit Union, the ease of access through TruStage and the potential for competitive rates make it a strong candidate for primary or supplemental life insurance.
In 2026, the best approach is to start by calculating your "human life value"—the total financial contribution you would make to your family over the next two decades—and then matching that with a term length that covers your longest-running debt. By utilizing the simplified application process available through the PFCU member portal, you can often secure your family's future in less time than it takes to visit a local branch. Always compare the provided quote with at least one other major carrier to ensure you are getting the best value for your specific health profile.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
