Understanding Fairfield Fiesta Auto Insurance: Coverage, Options, and Practical Considerations
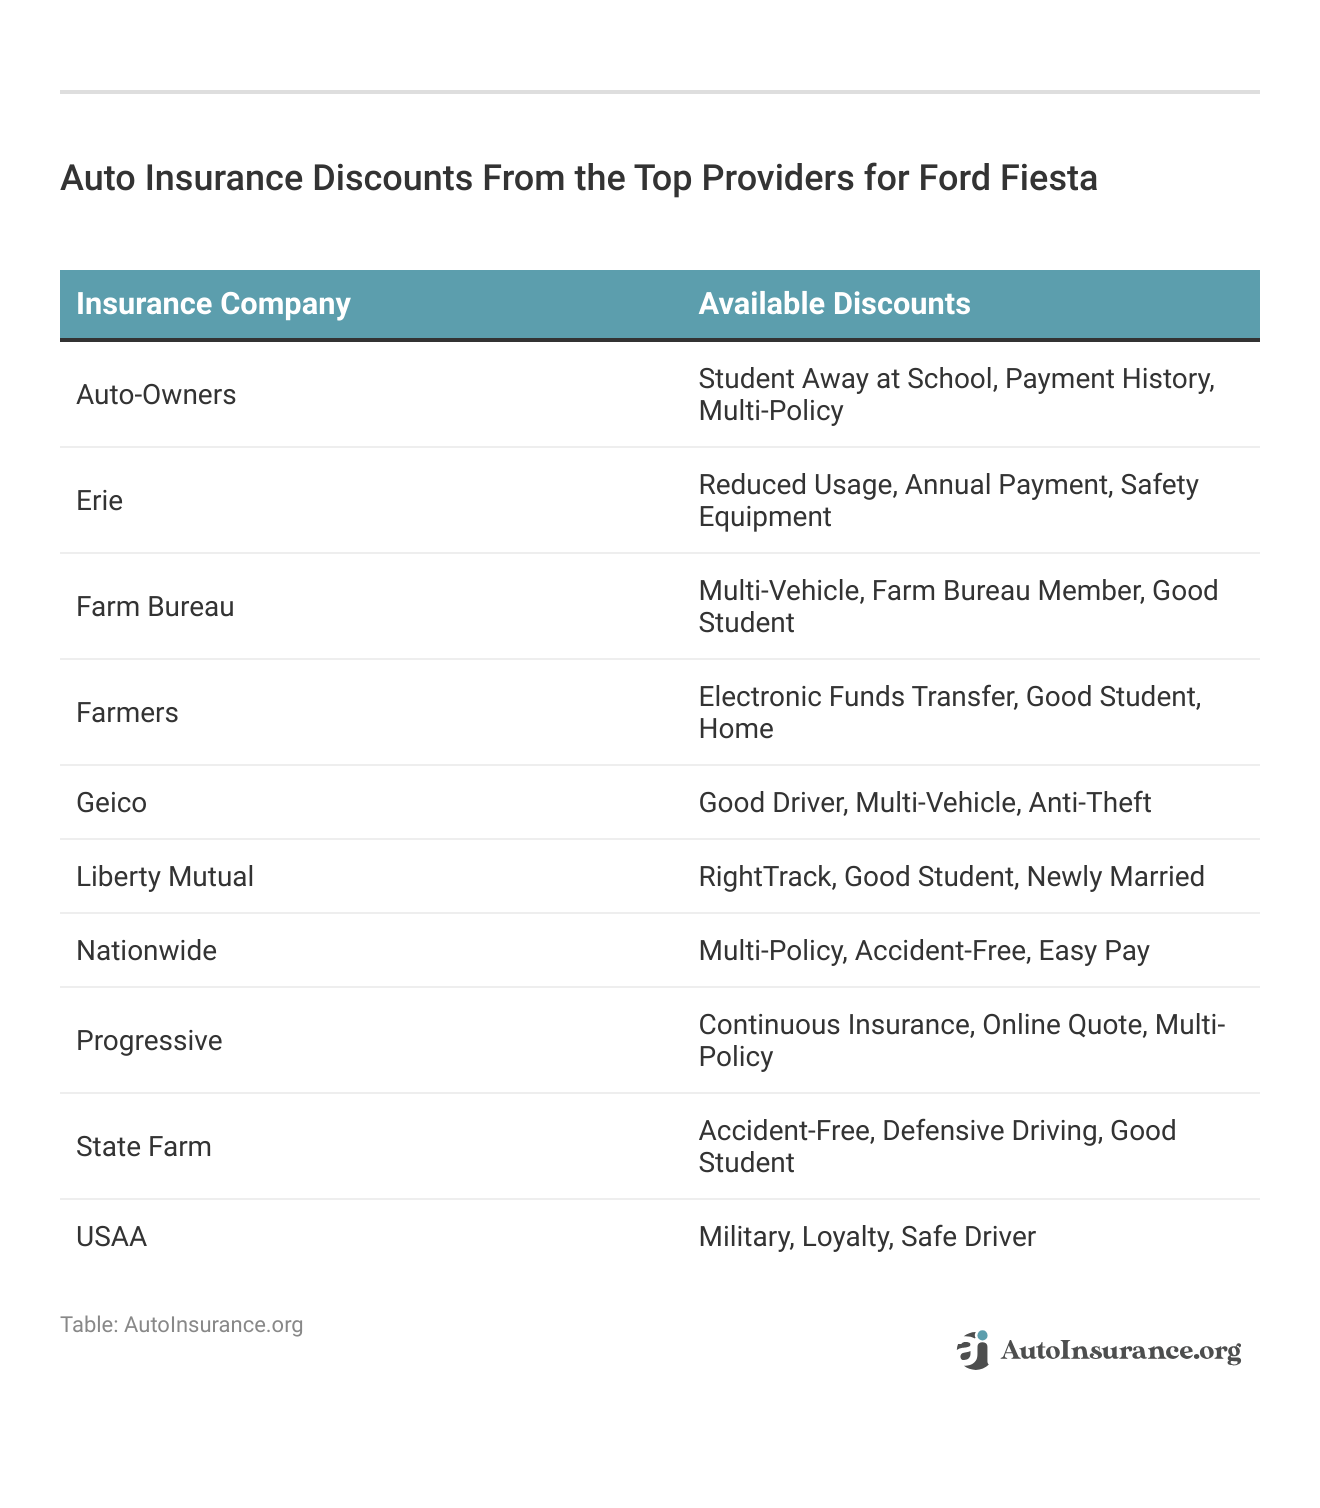
Securing auto insurance in the Fairfield, California, region requires navigating specific state mandates, local environmental risks, and individual vehicle requirements. Fairfield Fiesta auto insurance refers to the insurance landscape for residents of Fairfield, where drivers must balance California’s mandatory minimum liability requirements with the unique logistical challenges of Solano County’s traffic patterns and commute environments.
The Landscape of California Auto Insurance Regulations
To understand auto insurance in Fairfield, one must first recognize the regulatory framework established by the California Department of Insurance (CDI). Unlike many states that rely on a "fault" system for all claims, California operates under a tort system, meaning the person responsible for an accident is liable for the damages.
Under the California Financial Responsibility Law, every driver must maintain proof of financial responsibility. The mandatory minimum liability coverage limits in California as of 2026 are:
- $15,000 for injury or death to one person per accident.
- $30,000 for injury or death to two or more persons per accident.
- $5,000 for property damage per accident.
While these are the legal minimums to operate a vehicle, they are rarely sufficient in the event of a significant collision. Repair costs for modern vehicles and medical expenses frequently exceed these low statutory limits, leaving the driver personally liable for any excess costs. Therefore, most insurance experts in the Fairfield area recommend higher limits—typically 100/300/100—to protect personal assets.
Geographic and Environmental Considerations in Fairfield
Fairfield presents specific variables that insurers use to determine premium rates. Your proximity to major arteries, such as Interstate 80 and State Route 12, influences your "garaging address" risk profile. High-traffic corridors are statistically associated with a higher frequency of minor fender-benders and theft incidents.
Additionally, climate-related factors in Solano County play a role. Seasonal high winds in the Carquinez Strait area and potential debris during storm seasons can lead to comprehensive claims related to glass damage or falling objects. When selecting your policy, evaluate whether your comprehensive deductible is set at an amount you can comfortably pay if such an event occurs.
Understanding Core Coverage Components
When shopping for a policy in Fairfield, you will encounter several distinct coverage tiers. Distinguishing between them is essential for building a robust safety net.
Liability Coverage
This is the mandatory foundation. Bodily Injury Liability covers the costs associated with injuries to others if you are at fault. Property Damage Liability covers the repair costs for the other driver's vehicle or any public property (such as signs or fences) you may damage.
Collision and Comprehensive
These are optional coverages, unless you are financing or leasing your vehicle, in which case your lender will require them.
- Collision: Pays to repair or replace your vehicle after an accident involving another car or an object.
- Comprehensive: Covers non-collision incidents such as fire, theft, vandalism, or weather damage.
Uninsured/Underinsured Motorist (UM/UIM)
Given that a segment of the driving population may be underinsured, UM/UIM coverage is highly recommended. It bridges the gap if you are involved in an accident with a driver who lacks insurance or lacks sufficient limits to cover your medical bills and repair costs.
Comparative Overview of Policy Types
| Coverage Type | Purpose | Recommendation |
|---|---|---|
| Liability Only | Satisfies state law, no vehicle protection. | Only for older vehicles with low market value. |
| Full Coverage | Liability + Collision + Comprehensive. | Recommended for vehicles < 10 years old. |
| Gap Insurance | Covers the difference between loan balance and vehicle value. | Essential for new cars with small down payments. |
| Medical Payments | Covers health costs regardless of fault. | Useful if you have a high-deductible health plan. |
The Role of Personal Factors in Pricing
In California, insurers are heavily regulated by Proposition 103, which dictates the factors companies can use to set premiums. These factors are prioritized as follows:
- Driving Safety Record: Your history of accidents and moving violations is the primary driver of your premium.
- Annual Mileage: The more you drive, the higher the statistical probability of an accident.
- Years of Driving Experience: Less experienced drivers are statistically riskier, leading to higher premiums for younger or newly licensed drivers.
Unlike many other states, California prohibits the use of credit scores to determine auto insurance premiums. This is a critical distinction for consumers. If an insurer attempts to use your credit history as a primary rating factor in California, it is a violation of state regulations.
Steps to Managing Your Auto Insurance
Securing and maintaining the right insurance requires a proactive approach. Follow these steps to ensure you are appropriately covered:
- Assess Vehicle Value: Use reliable valuation tools to determine the current market value of your vehicle. If the annual cost of comprehensive and collision insurance is more than 10% of the car's value, it may be time to consider dropping those specific coverages.
- Review Declarations Page: Once you obtain a policy, review the "Declarations Page." This document summarizes your coverage limits, deductibles, and discounts. Ensure that the listed garaging address is your primary residence in Fairfield.
- Explore Bundling: Many providers offer significant discounts if you bundle your auto policy with home, renters, or umbrella insurance. Ask about these multi-policy discounts during the quoting process.
- Annual Audits: Life circumstances change. If you have moved, purchased a new vehicle, or had a change in your daily commute distance, inform your insurer. These changes can often result in lower premiums.
Common Pitfalls and Troubleshooting
A frequent mistake for new residents or new drivers in Fairfield is choosing the cheapest premium without reviewing the coverage limits. Low premiums often come with high deductibles and minimal liability coverage, which can lead to financial ruin in the event of a catastrophic accident.
If you encounter issues such as an unexpected rate increase, check your annual driving report to ensure there are no clerical errors, such as misreported accidents. If you find discrepancies, contact the insurance carrier's claims department or their consumer ombudsman to request a correction. If the insurer remains unresponsive, the California Department of Insurance provides a consumer complaint process that can act as a mediator.
Frequently Asked Questions
Does my insurance cover me if I rent a car while visiting another part of California? Generally, your existing liability and physical damage coverage will extend to a rental vehicle, provided you are using it for personal, not commercial, reasons. However, verify with your specific carrier to see if they impose restrictions on high-value or specialty rental vehicles.
How do I prove I have insurance in Fairfield if pulled over? California accepts electronic proof of insurance. You can keep a digital copy of your insurance card on your smartphone to present to law enforcement. It is still recommended to keep a physical copy in your glove compartment as a backup for when cellular service or battery levels are unavailable.
Are there specific discounts available for defensive driving courses in California? Many insurance companies offer discounts for completing a DMV-approved defensive driving course. These are particularly valuable for senior drivers or those who have had a recent traffic violation, as they can sometimes mitigate the impact on future premiums.
What happens if I move out of Fairfield to another city in California? Auto insurance rates are location-specific. If you move, your risk profile changes based on the crime rate, accident frequency, and cost of living in your new zip code. You must notify your insurer of any change of address immediately to maintain valid coverage and avoid potential claim denials.
Why did my insurance rate go up despite a clean driving record? Insurance rates are influenced by broader economic factors, including the rising costs of vehicle repair, the price of parts, and the frequency of claims within your specific rating territory. Even without individual claims, broad regional trends can cause universal rate adjustments.
Next Actions
To refine your insurance standing, start by requesting quotes from at least three different carriers—ideally a mix of large national insurers and regional California-based companies. Compare not just the premiums, but the "limits of liability" and the "deductible amounts." If your vehicle is financed, verify that your chosen policy meets the specific minimums set forth by your lienholder to avoid "force-placed" insurance, which is typically more expensive and offers less protection. Finally, document your coverage decisions; keep your policy documents in a secure location and ensure all drivers in your household are listed on the policy to avoid coverage disputes.
Image Gallery
Select an image to open it in a new tab.
Vivian Cho
Executive IT and Emerging Technologies Reporter
