
Finding the right auto insurance in Fairfield, California, requires navigating California’s specific regulatory environment while balancing personal coverage needs against local cost factors. Because California is a "fault" state, the focus is on maintaining high liability limits to protect your assets while leveraging state-mandated consumer protections to ensure transparency and fairness in pricing.
Understanding the Regulatory Landscape in California
California auto insurance is governed by the California Department of Insurance (CDI), which enforces strict rules on how insurance companies determine premiums. Unlike many other states where insurers can adjust rates based on credit scores or gender, California’s Proposition 103 mandates that rates be primarily determined by driving safety record, annual mileage, and years of licensed driving experience.
In Fairfield, your premium is influenced by the Solano County risk profile. Urban density, traffic patterns on Interstate 80, and regional weather conditions play a role in how insurers assess the likelihood of accidents. When shopping for a policy, recognize that you are not just buying a product; you are entering a regulated contract where your driving history is the most powerful tool you have to control costs.
Evaluating Your Coverage Requirements
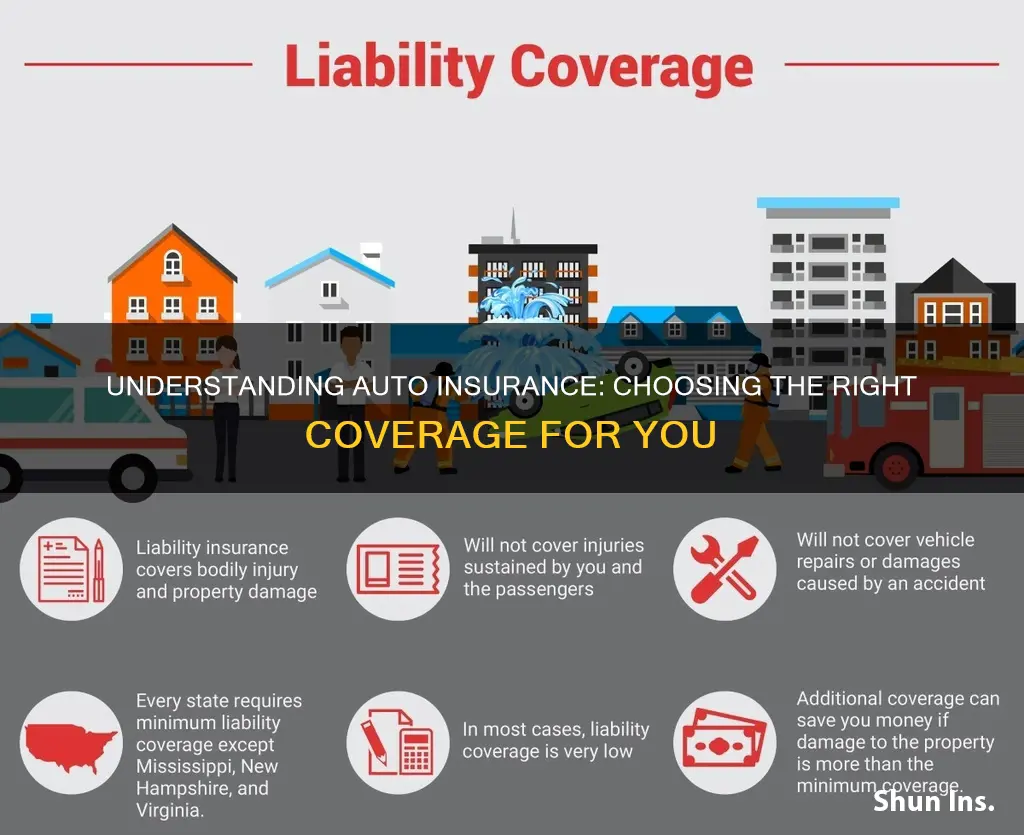
Before comparing providers, you must assess what your "ride" actually requires. In California, the legal minimum liability coverage is 15/30/5—meaning $15,000 for injury/death to one person, $30,000 for injury/death to more than one person, and $5,000 for property damage.
However, experts strongly advise against carrying only these minimums. In 2026, the cost of vehicle repairs and medical care has risen significantly. If you are at fault in an accident involving a luxury vehicle or significant injuries, the state-minimum $5,000 for property damage will be exhausted almost instantly, leaving you personally liable for the remaining balance.
Core Coverage Components
- Bodily Injury Liability: Covers costs related to injuries you cause to others.
- Property Damage Liability: Pays for damage to another person's property, such as their vehicle, fence, or signage.
- Collision Coverage: Covers repairs to your own vehicle after an accident, regardless of fault.
- Comprehensive Coverage: Protects against non-collision events like theft, fire, vandalism, or environmental damage (e.g., falling branches).
- Uninsured/Underinsured Motorist Coverage: Crucial in California to protect yourself if the at-fault driver has no insurance or insufficient limits.
How to Compare Providers in Fairfield
When evaluating insurers, look beyond the premium price. Customer service, claims processing efficiency, and the company’s financial stability are equally critical. Use the California Department of Insurance "Compare Auto Insurance Premiums" tool to see sample quotes for various driver profiles in your specific ZIP code.
Step-by-Step Comparison Strategy
- Gather Documentation: Have your current policy declaration page, VIN, and recent driving history (including any accidents or citations within the last three years) ready.
- Request Multiple Quotes: Obtain at least three quotes from different types of providers: national carriers, regional specialists, and direct-to-consumer insurers.
- Review Financial Strength: Check ratings from organizations like A.M. Best. A company may offer low premiums, but if they lack the capital to process claims quickly, you may face significant delays after a loss.
- Examine Complaint Ratios: The CDI publishes annual reports on insurance company complaint ratios. A company with a high number of consumer complaints relative to its market size should be approached with caution.
Table: Typical Coverage Trade-offs for Fairfield Drivers
| Coverage Type | Priority Level | Benefit | Consideration |
|---|---|---|---|
| Liability (100/300/50) | Essential | High protection for your assets | Significantly safer than state minimums |
| Comprehensive | High | Protects against theft/vandalism | Essential for newer vehicles or those parked outside |
| Collision | High | Repairs your car after an accident | Optional if your car has very low market value |
| Rental Reimbursement | Medium | Covers transport during repairs | Valuable if you rely on your vehicle for work |
| Gap Insurance | Conditional | Pays loan balance if car is totaled | Crucial if you owe more than the car's market value |
Managing Costs Without Sacrificing Protection
Reducing your insurance premium should not mean stripping your policy of necessary protections. Instead, look for ways to lower your risk profile in the eyes of the insurer.
Ask your agent specifically about "California-compliant" discounts. Because California limits the use of certain demographic data, providers often rely on affinity discounts—such as those for members of professional organizations, alumni associations, or even specific employers.
Furthermore, consider increasing your deductible if you have sufficient emergency savings. Moving from a $500 deductible to a $1,000 deductible can often result in a noticeable reduction in your annual premium. However, only do this if you can realistically afford to pay that $1,000 out-of-pocket at a moment's notice.
Addressing Common Pitfalls
One of the most frequent mistakes Fairfield drivers make is allowing a lapse in coverage. Even a single day without active insurance can lead to significantly higher premiums when you attempt to start a new policy. If you are switching providers, ensure the new policy is active before canceling the old one.
Another pitfall is providing inaccurate information during the quote process. Insurers cross-reference data with the DMV. If you omit a moving violation or lie about your primary garaging address, the insurer may retroactively cancel your policy or deny a claim when you need it most. Honesty is the cheapest way to maintain insurance, as it prevents the catastrophic loss of coverage.
Troubleshooting Claims and Disputes
If you find yourself in an accident, your first step is to document everything. Take photos of the scene, exchange insurance information with the other party, and obtain a copy of the police report if law enforcement arrives.
If you feel an insurance company is acting in bad faith—such as unreasonably delaying a payout or denying a valid claim—you have rights. The California Department of Insurance offers a consumer complaint process. Before escalating to the state, however, document your communication with the insurer’s claims adjuster in writing. Email is your best friend during this process, as it creates an immutable paper trail of your efforts to resolve the issue.
Frequently Asked Questions
Does my credit score affect my insurance rates in Fairfield?
No. Under California law, insurers are prohibited from using your credit score to determine your auto insurance rates. They must focus on your driving record, annual mileage, and years of experience.
How often should I re-evaluate my policy?
You should review your policy at least once every 12 months, or whenever you experience a major life change. Examples include moving to a new address in Fairfield, getting married, adding a driver to your household, or purchasing a new vehicle.
Is it better to go with a local broker or a national company?
Local brokers often provide personalized service and can explain the nuances of the local market, while national companies may offer sophisticated mobile apps and digital claims filing. The quality of the insurance depends on the specific carrier's financial stability, not necessarily its size.
What is the advantage of high liability limits?
High liability limits protect your personal assets (savings, home equity, future wages) in the event of a major lawsuit. In a serious accident where you are at fault, minimum limits can be exhausted within minutes, leaving you personally responsible for damages that exceed your policy cap.
Can I get a discount for taking a defensive driving course?
Yes, many California insurers offer a "Good Driver" discount. Check if your provider recognizes specific state-approved defensive driving courses, as completing these can sometimes yield a recurring premium reduction.
Next Steps for Securing Your Policy
To move forward, begin by requesting an updated "Motor Vehicle Report" (MVR) from the California DMV to ensure your driving history is accurate. Once you have confirmed your data, reach out to three reputable companies to request quotes with standardized coverage levels—such as 100/300/50 liability—to compare "apples to apples."
If you are currently mid-policy, don't wait for your renewal date to save money. You can request a policy review or move your coverage at any time. If you decide to switch, ensure your new policy provides a "bind date" that perfectly aligns with the cancellation of your old policy to avoid any gaps. Your financial protection on the road in Fairfield depends on consistent, reliable coverage that reflects the actual risks of modern driving.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
