Alito Health Is a Wellness Program Not an Insurance Plan: Understanding the Distinction

Alito Health functions as a wellness program rather than an insurance plan, meaning it provides access to health-related services, fitness resources, or preventive care support without fulfilling the legal or financial requirements of a regulated insurance policy. Users must recognize that it does not indemnify them against medical expenses, nor does it replace the need for comprehensive health coverage mandated under applicable laws.
Defining the Wellness Program Model
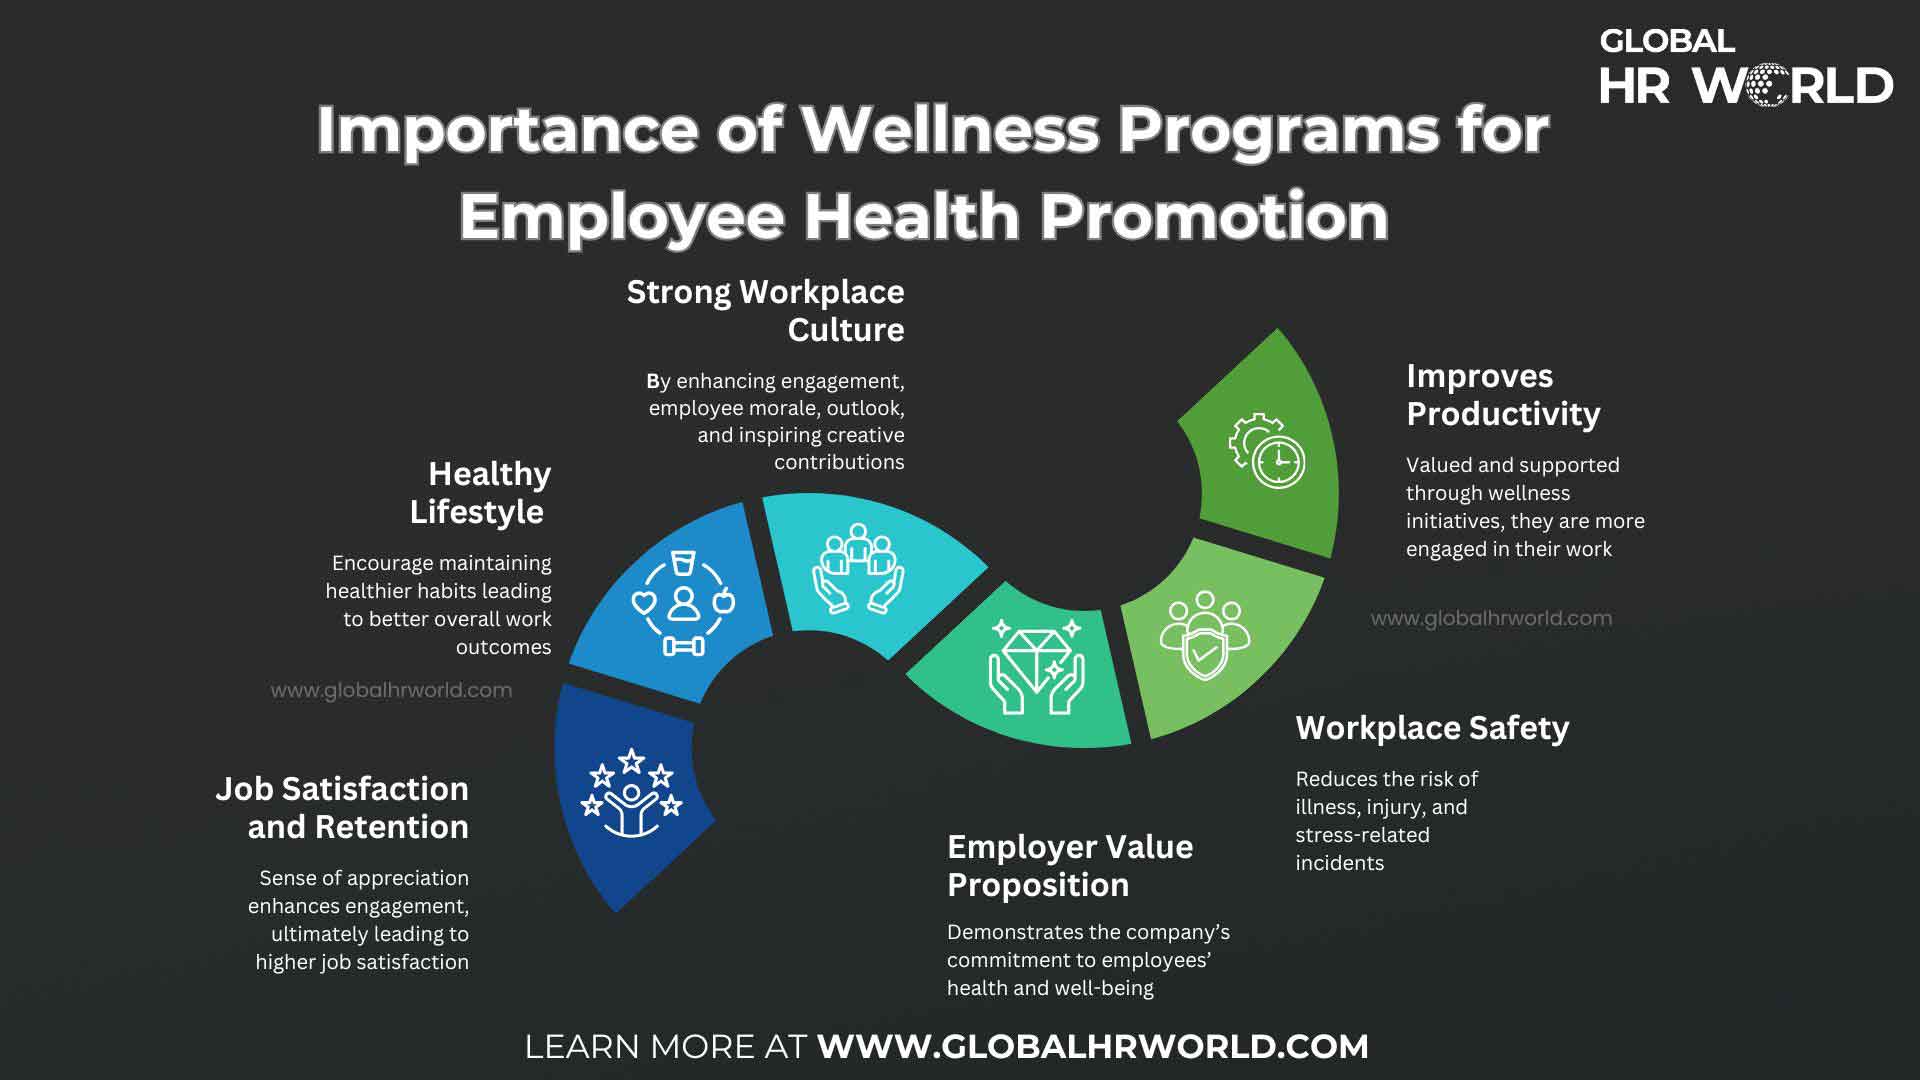
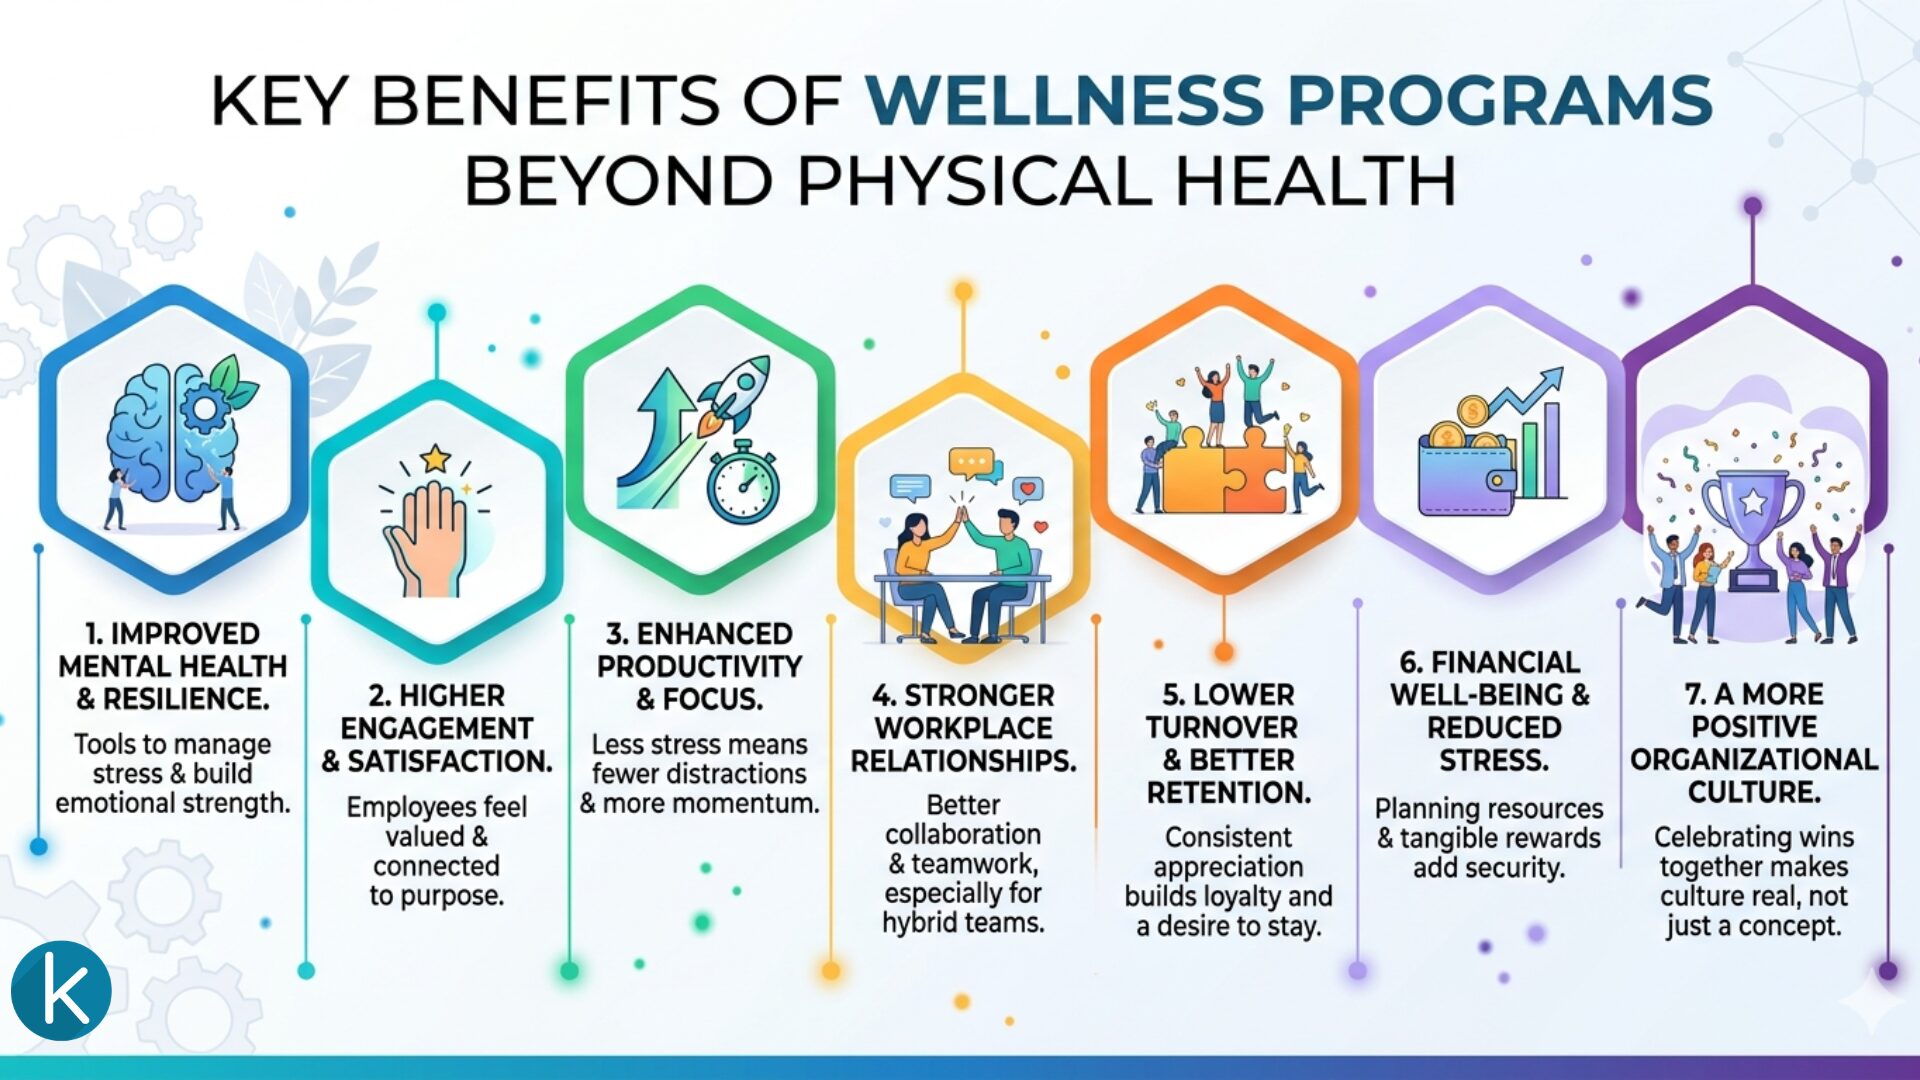
To navigate the landscape of modern healthcare offerings, it is essential to distinguish between a wellness program and a formal insurance plan. A wellness program, such as the one offered by Alito Health, is primarily designed to promote healthy habits, provide nutritional guidance, offer fitness coaching, or facilitate non-clinical health monitoring. These programs are often integrated into corporate benefits packages or sold directly to consumers to enhance overall quality of life.
In contrast, a formal insurance plan is a financial product regulated by state and federal authorities. Its primary function is to share risk, providing protection against catastrophic financial loss resulting from medical emergencies, surgical procedures, or chronic disease management. When a service is labeled as a wellness program, it explicitly lacks the "risk-pooling" mechanism that defines insurance. Understanding this distinction is the most important step for any participant, as it dictates what happens when a significant medical event occurs.
Why the Distinction Matters for Consumers
The legal and financial differences between these two entities are substantial. If a consumer enters a wellness program believing it is insurance, they risk facing significant out-of-pocket costs during a medical crisis.
Financial Liability
Under a traditional insurance plan, the provider is responsible for covering a portion of medical costs based on the policy terms, deductibles, and co-pays. Because a wellness program is not insurance, the provider assumes no financial liability for medical bills. If you receive a service that is not part of the wellness curriculum—such as an emergency room visit—you remain fully responsible for the charges.
Regulatory Protections
Insurance plans are strictly regulated to ensure they maintain adequate reserves to pay claims. They are governed by consumer protection laws, such as the Affordable Care Act (ACA) in the United States, which mandate specific coverage levels and grievance procedures. Wellness programs are generally subject to less stringent oversight. While they must comply with consumer privacy laws and general business regulations, they are not held to the fiduciary standards required of licensed insurers.
Core Features of Alito Health
Alito Health focuses on the proactive side of well-being. By positioning itself as a wellness initiative, the program can bypass the rigid, often complex requirements of medical insurance, allowing for a more flexible, lifestyle-oriented approach.
Typical features found in programs categorized as wellness-only include:
- Educational Resources: Access to webinars, articles, and workshops centered on healthy living and disease prevention.
- Fitness Tracking: Integration with wearable devices or digital platforms to monitor physical activity and sleep patterns.
- Nutritional Guidance: Personalized meal planning, calorie tracking, or consultations with health coaches.
- Preventive Screenings: Basic biometric screenings that provide baseline data on health markers but do not constitute medical diagnosis or treatment.
It is crucial to verify which specific features are included in your agreement with Alito Health. Because these programs are not insurance, the "benefits" are defined entirely by the service agreement or contract between the participant and the company, rather than by statutory mandates.
Comparison: Wellness Programs vs. Insurance Plans
| Feature | Wellness Program (e.g., Alito Health) | Insurance Plan |
|---|---|---|
| Primary Purpose | Health promotion and lifestyle change | Financial risk protection |
| Claim Coverage | Generally none for medical services | Covers specified medical treatments |
| Regulatory Status | Consumer service agreement | Regulated financial product |
| Financial Liability | Participant responsible for all medical bills | Provider covers share of insured costs |
| Eligibility | Often open; no medical underwriting | Dependent on plan type/enrollment |
| Requirement | Voluntary supplement | Often mandatory (ACA compliance) |
Assessing Your Healthcare Needs
Choosing the right coverage requires an honest assessment of your current health status and financial risk tolerance. If you have existing medical conditions or require regular access to clinical care, a wellness program cannot serve as your primary safety net.
When to Rely on a Wellness Program
A wellness program is most effective when used as a secondary, supplemental tool. It is ideal for individuals who are generally healthy and want to optimize their physical fitness, manage weight, or participate in preventative habits that might reduce their long-term reliance on clinical medicine.
When Insurance is Mandatory
For any individual with chronic health needs, a family, or anyone wanting protection from the financial ruin of an unexpected accident or illness, a licensed insurance plan is essential. In 2026, the reliance on wellness programs as a substitute for insurance remains a significant risk. If you are currently relying solely on a wellness program for medical coverage, you are likely uninsured in the eyes of the law and vulnerable to significant debt.
Verifying the Status of Your Plan
If you are uncertain whether your current coverage is a wellness program or an insurance plan, review your documentation using the following checklist:
- Check for "Summary of Benefits and Coverage" (SBC): Licensed insurance plans are required to provide an SBC document. If you do not have one, you are likely enrolled in a non-insurance product.
- Review the Provider Network: Insurance plans have extensive networks of doctors and hospitals. Wellness programs often utilize a limited network of coaches or personal trainers rather than medical facilities.
- Analyze the Financial Contract: Look for terms like "indemnity," "premium," "deductible," or "coinsurance." If the documentation uses terms like "membership fee," "service fee," or "program access," you are almost certainly looking at a wellness product.
- Regulatory Inquiries: If you are still unsure, contact your state department of insurance. They maintain records of all licensed insurance carriers and can clarify if a specific company is legally authorized to offer insurance in your jurisdiction.
Common Misconceptions and Risks
The most dangerous misconception regarding programs like Alito Health is that they provide the same protection as comprehensive major medical insurance. This confusion often arises from marketing that emphasizes "health" and "access to doctors."
Even when a wellness program offers access to telehealth services, it is critical to determine if those services are providing medical advice or simple health coaching. Medical advice involves diagnosis and treatment—the domain of insurance-backed clinical practice—whereas health coaching involves behavioral guidance. Misinterpreting one for the other can lead to delayed medical treatment during emergencies, as patients may mistakenly believe their wellness program will handle the situation.
Furthermore, wellness programs do not count as "minimum essential coverage" for tax purposes in many jurisdictions. Depending on your tax situation, failing to maintain actual insurance could have financial implications. Always consult with a licensed tax professional or a healthcare navigator to ensure your coverage meets the necessary legal standards for your specific location and household status.
Practical Next Actions
If you have discovered that your current coverage through Alito Health is a wellness program rather than an insurance plan, follow these steps to secure your financial and physical well-being:
- Obtain Major Medical Coverage: Prioritize enrolling in a government-subsidized health exchange, an employer-sponsored plan, or an individual private plan that offers comprehensive coverage.
- Maintain Wellness as a Supplement: Keep your Alito Health program if you find the wellness tools and fitness resources valuable. Simply reframe your relationship with the company: it is a tool for self-improvement, not a safety net for medical emergencies.
- Document Your Coverage: Create a folder containing your actual insurance card, contact information for your insurer, and your policy documents. Keep this separate from your wellness program materials.
- Update Emergency Information: Ensure that any medical records or emergency contacts you carry reflect your actual insurance coverage, as hospitals will require this information to authorize care during an emergency.
While wellness programs offer meaningful value in the modern health landscape, they are not a substitute for the protection provided by institutional insurance. By separating the two, you can enjoy the benefits of fitness and lifestyle coaching while ensuring that you are fully protected against the unpredictable realities of medical expenses.
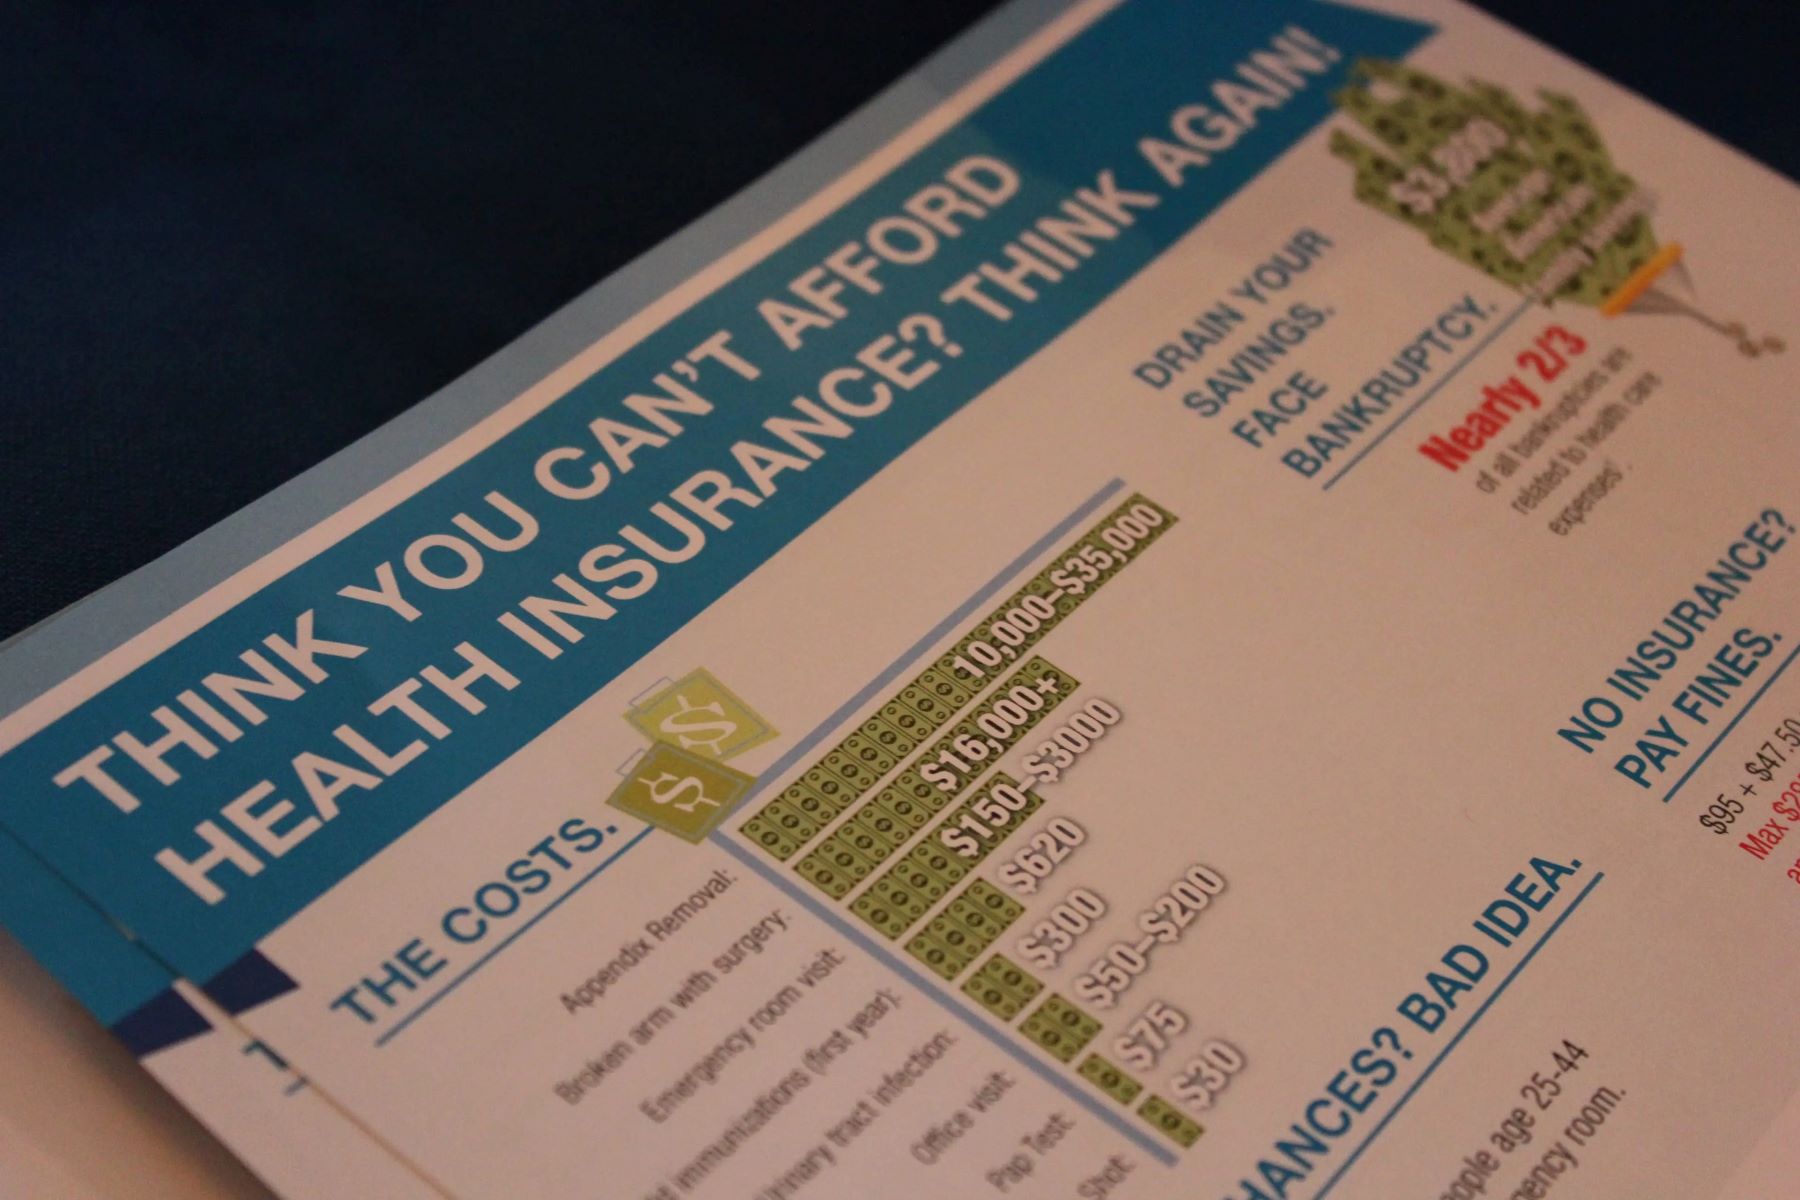
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
