Filing a whole life insurance claim with AIG involves notifying the company of the policyholder’s passing, submitting a certified death certificate, and completing the claimant statement form. Once these documents are received and verified by the claims department, AIG reviews the policy status to determine eligibility and disburses the death benefit to the designated beneficiaries according to the policy terms.
Understanding Whole Life Insurance Claims
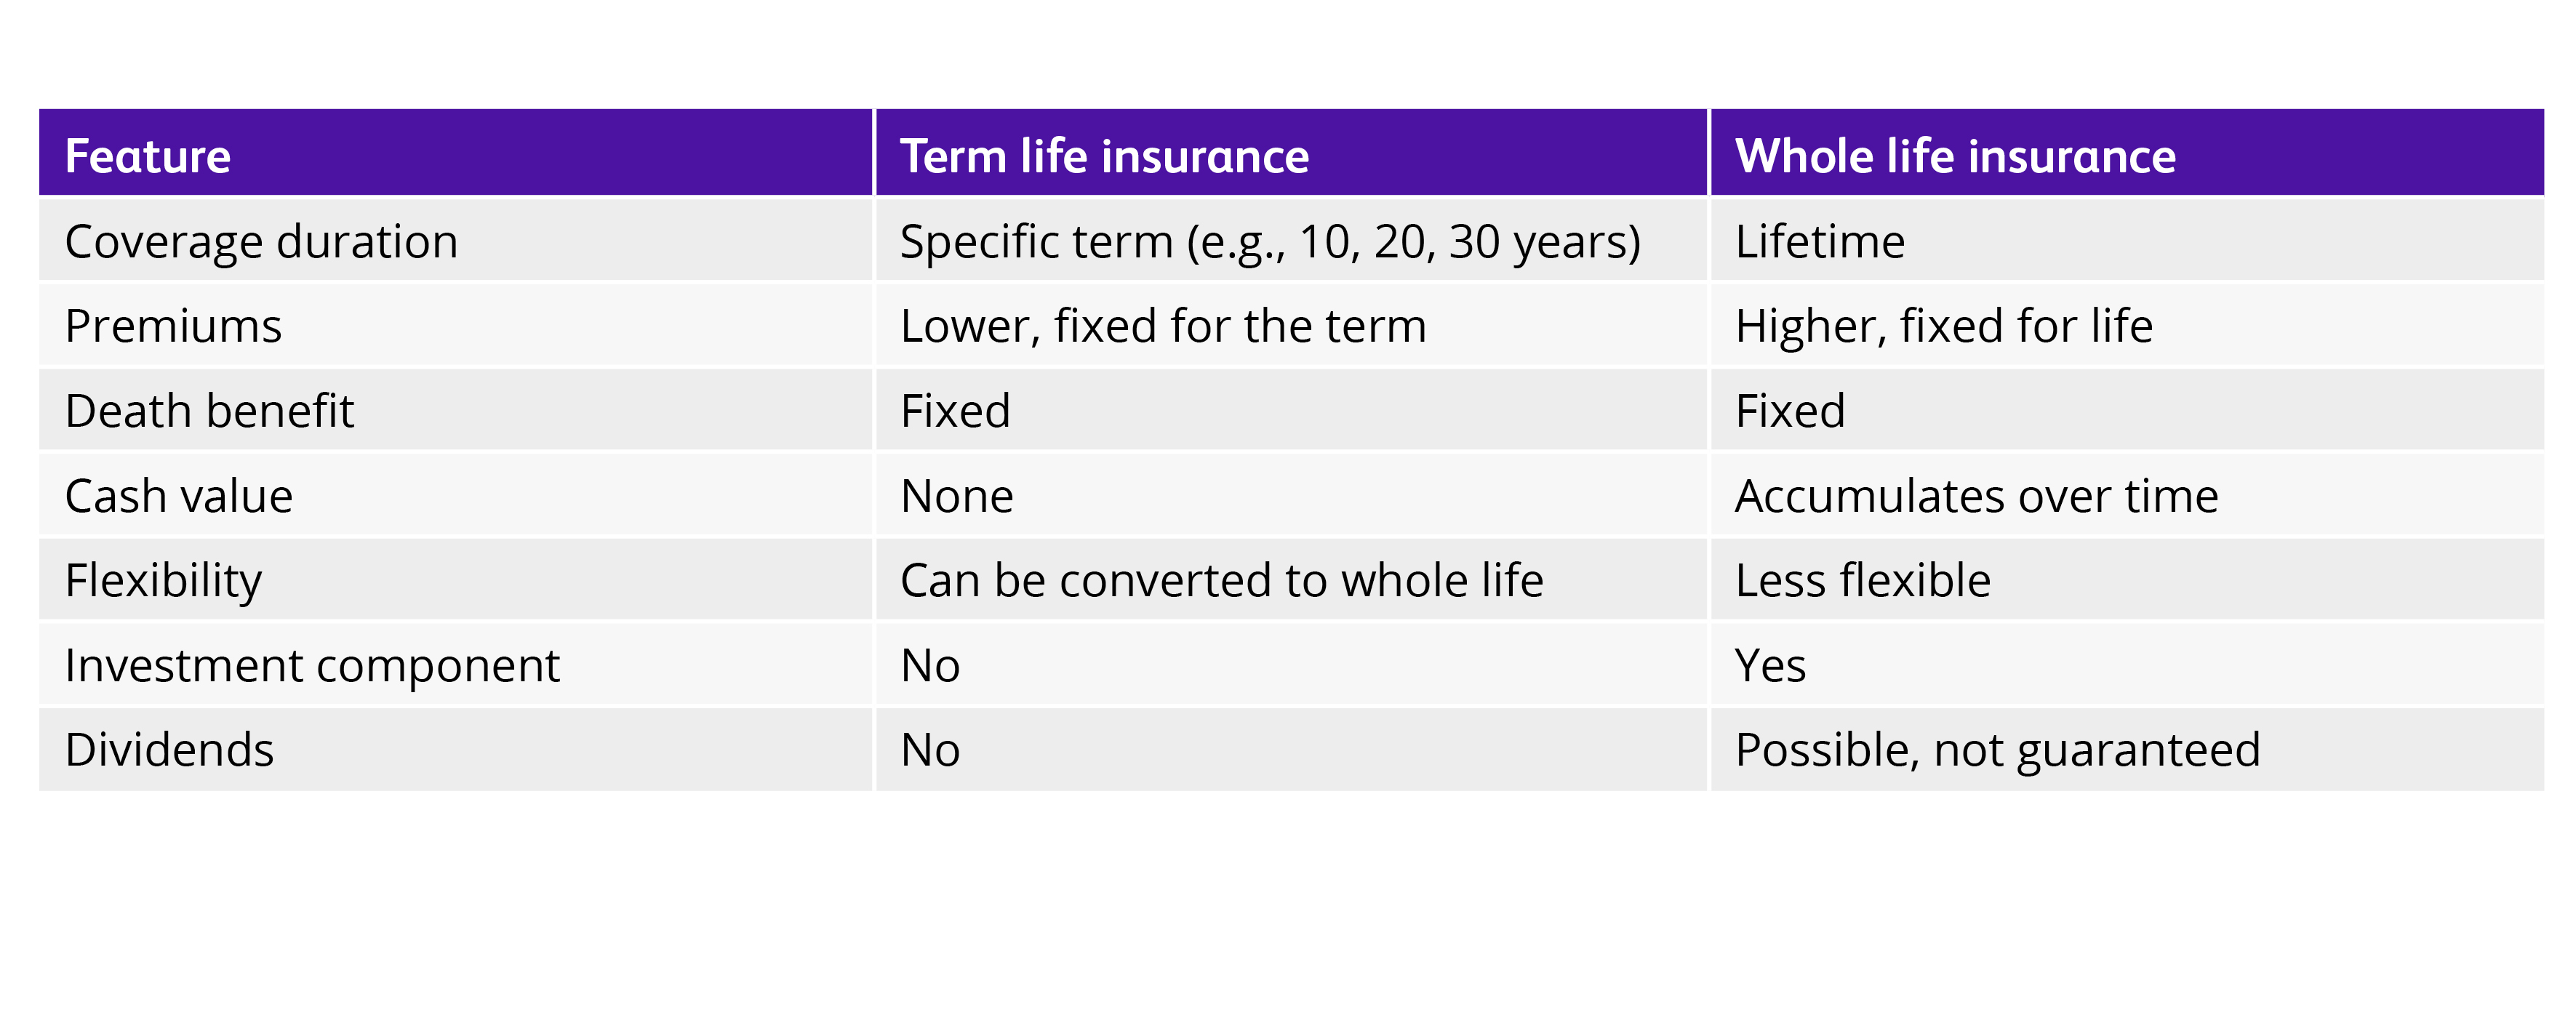
A whole life insurance policy is a permanent insurance product that remains in effect for the insured’s entire life, provided that premiums are paid. Unlike term life insurance, which expires after a set period, whole life policies often include a cash value component that accumulates over time. When a policyholder passes away, the claim process is the mechanism by which the death benefit is transferred to the beneficiaries.
Because whole life insurance is often held for decades, the records associated with these policies may be older or less accessible than those of modern, digitized products. AIG, as a large, multinational insurer, maintains standardized procedures to handle these claims across various jurisdictions. Understanding these procedures is essential for ensuring a smooth, timely disbursement of funds during a period that is often difficult for family members and executors.
The Initial Notification Process
The first step in the claims process is providing formal notification of the death to AIG. This notification triggers the internal administrative process, allowing the insurer to flag the policy, suspend premium requirements, and prevent accidental lapses while the claim is being processed.
To initiate this notification, you will need specific information regarding the policyholder. Attempting to report a death without these details may lead to delays in identifying the correct account:
- Full legal name of the deceased.
- Policy number (if available). If the policy number is unknown, the Social Security number and date of birth of the insured are required to conduct a search.
- Date and location of death.
- Contact information for the person filing the claim, typically the executor or the primary beneficiary.
You do not need an original death certificate at the exact moment of initial notification, but you should prepare to obtain one, as it is a mandatory document for the final approval phase.
Required Documentation for Claim Processing
AIG requires verifiable evidence to process a death claim. Because life insurance contracts are legally binding financial agreements, the company must confirm the death with absolute certainty to comply with state insurance regulations.
- Certified Death Certificate: You must provide a certified copy of the death certificate. This document must be issued by the relevant government authority in the jurisdiction where the death occurred. AIG generally does not accept photocopies or digital scans that have not been certified with an official seal.
- Claimant Statement: This is the primary form the beneficiary must complete. It requires the beneficiary to verify their identity and provide instructions on how they wish to receive the death benefit funds.
- Policy Documents: If you have the original paper policy document, include it with your submission. While the absence of the paper policy does not usually invalidate a claim, having it can expedite the verification of policy riders, loans against the cash value, or specific beneficiary designations.
- Proof of Relationship/Authority: If the claimant is an executor or a trustee representing an estate, AIG may require legal documentation, such as Letters Testamentary or a Certification of Trust, to prove the authority to act on behalf of the deceased.
Evaluation and Verification Procedures
Once the claims department receives the documentation, they perform a due diligence review. This process is not intended to create hurdles but to ensure that the funds are paid to the correct, legally entitled recipient.
The claims examiners will verify:
- Policy Status: Ensuring the policy was in force at the time of death. This involves checking if there were any outstanding premium payments or if the policy had been surrendered previously.
- Beneficiary Verification: Confirming the identity of the beneficiaries. If there have been changes in marital status or if a primary beneficiary predeceased the insured, the insurer will look for secondary (contingent) beneficiaries.
- Contestability Period: For older policies, this is rarely an issue. However, if a policy is relatively new, the insurer may review the original application to ensure all medical and personal history was disclosed accurately.
- Policy Loans or Liens: If the policyholder took out a loan against the cash value of the whole life policy, that amount, plus any accrued interest, will be deducted from the death benefit before the final payout.
Table 1: Comparison of Common Claim Outcomes
| Scenario | Impact on Death Benefit |
|---|---|
| No Outstanding Loans | The full face amount of the policy is paid to the beneficiary. |
| Outstanding Policy Loan | The death benefit is reduced by the loan balance and unpaid interest. |
| Accidental Death Rider | An additional amount is paid if death resulted from a covered accident. |
| Lapsed Policy | Generally no death benefit paid, though some policies offer non-forfeiture options. |
| Contested Claim | Payment is paused pending investigation into application accuracy. |
Disbursement Options for Beneficiaries
AIG provides several ways for beneficiaries to receive the death benefit. It is important to review these options carefully during the claim process, as they have different tax and financial implications.
- Lump Sum Payment: The most common method, where the entire benefit is paid as a single payment, typically via check or wire transfer. This offers immediate liquidity for the beneficiary.
- Retained Asset Account: AIG may offer to hold the funds in an interest-bearing account. The beneficiary can access these funds by writing drafts (checks) against the balance. This allows the beneficiary time to decide how to invest or use the money.
- Installment Payments: Some policies or beneficiary selections allow for the death benefit to be paid out over a fixed period or as a life annuity, providing a steady stream of income rather than a large immediate sum.
Troubleshooting and Common Obstacles
If a claim is delayed, it is often due to missing information or discrepancies in the paperwork. Below are common issues and how to resolve them:
1. Beneficiary Cannot Be Located If a beneficiary is deceased, cannot be found, or is a minor, the claim may be delayed. If a minor is the named beneficiary, AIG usually requires a court-appointed legal guardian to receive the funds on the minor's behalf.
2. Discrepancies in Name or Information If the name on the death certificate does not match the name on the policy exactly (e.g., due to a marriage or a nickname), AIG may require an affidavit of identity to confirm that both documents refer to the same person.
3. Unclaimed Benefits If you believe you are a beneficiary of an old policy but cannot find the paperwork, search the National Association of Insurance Commissioners (NAIC) Life Insurance Policy Locator service. This helps connect beneficiaries with lost or forgotten policies.
Frequently Asked Questions
How long does the AIG claims process typically take? Once a complete and accurate claim package is received, most claims are processed within a few weeks. However, if additional documentation is required or if the policy is complex (such as one involving a trust or estate), it may take longer.
Are life insurance death benefits taxable? Generally, the death benefit from a life insurance policy is paid to the beneficiary income-tax-free under federal law. However, if the death benefit is held in an interest-bearing account, the interest earned on those funds is typically taxable. You should consult a tax professional for guidance based on your specific situation.
What happens if the policyholder had a loan against the cash value? Whole life insurance allows policyholders to borrow against their cash value. If a loan remains unpaid at the time of death, the outstanding balance—including any interest due—is subtracted from the death benefit paid to the beneficiaries.
Can I file the claim online? AIG provides specific portals for policy management. Check the official AIG or relevant insurance subsidiary website to see if an online notification tool is available for your specific region or policy type. Even if the notification is online, you will likely still need to mail or securely upload the certified death certificate.
What if the policy was purchased many years ago? AIG maintains records for long-standing policies. Even if you do not have the physical policy document, do not assume the policy is lost or invalid. Contact AIG’s customer service department with the deceased's Social Security number and legal name to perform a thorough search of their records.
Next Steps for Claimants
The most effective way to begin is to gather the necessary documents before reaching out to the insurer. Start by locating the original policy document or any premium notices, which serve as proof of the contract. Secure at least three to five certified copies of the death certificate, as you will likely need them for other estate matters beyond the insurance claim, such as closing bank accounts or handling real estate.
Once you have your documentation, contact the AIG life insurance claims department directly. Ensure you maintain a log of every conversation, including the name of the representative, the date, and a summary of what was discussed. If you encounter significant delays or difficulties, request to speak with a claims supervisor to clarify exactly what is preventing the final disbursement of the benefit.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
