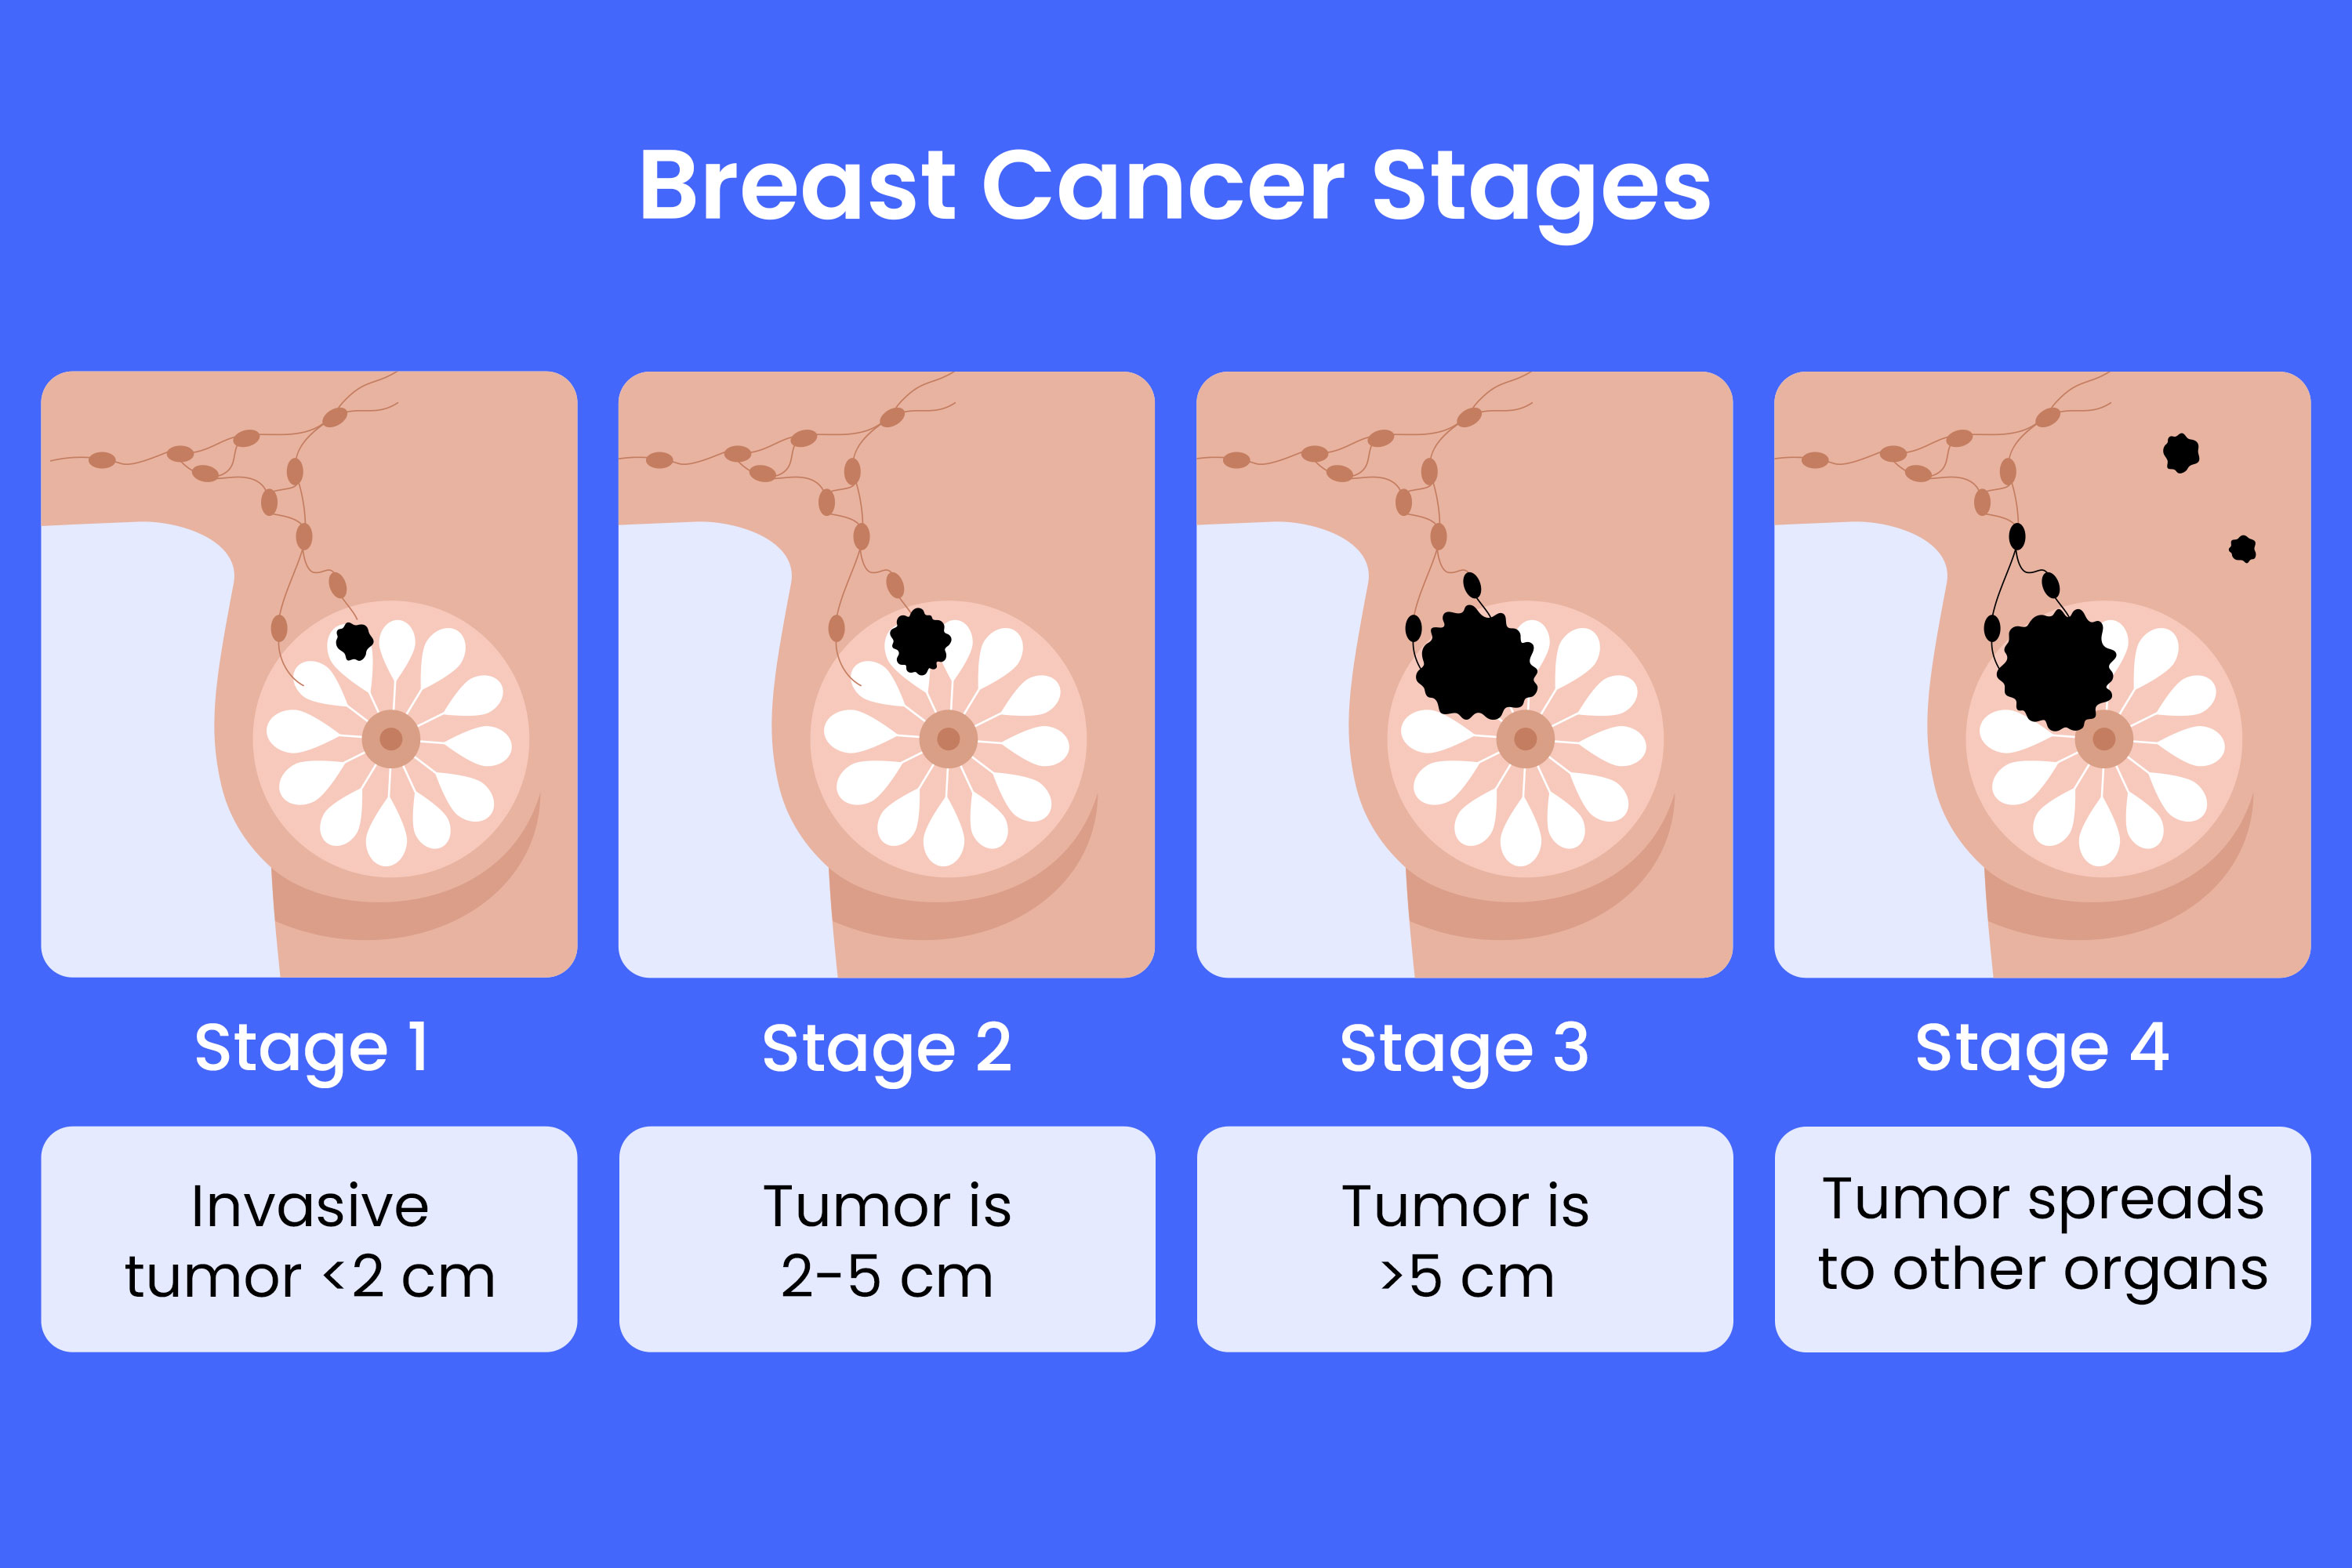
Securing traditional life insurance with a stage 4 cancer diagnosis is exceptionally difficult due to underwriting standards that prioritize longevity. While standard term and whole life policies often decline coverage at this stage, individuals may explore guaranteed issue life insurance, employer-sponsored group plans, or specialized high-risk products as potential pathways for final expense planning.
Understanding the Underwriting Process
Life insurance underwriting is the mechanism by which an insurance company assesses risk. When you apply for a policy, the insurer examines your medical history, current health status, and life expectancy to determine if you qualify and what your premiums will be. In the case of a stage 4 cancer diagnosis, the primary hurdle is the "mortality risk" assessment.
Insurance companies operate on actuarial tables. These statistical models estimate how long a person within a specific health bracket is likely to live. Stage 4 cancer, which indicates the disease has metastasized or spread to other parts of the body, creates an underwriting profile that most traditional insurers deem "uninsurable." Consequently, if you disclose your diagnosis during the medical exam or through the Medical Information Bureau (MIB) report, an automatic decline is the standard outcome for individual underwritten policies.
It is important to understand that there is no "tricking" the system. Life insurance applications ask specific questions about your health, and providing false information constitutes insurance fraud. If a policy were issued under false pretenses and a claim was later filed, the insurance company would likely conduct a contestability investigation, uncover the medical history, and deny the death benefit, leaving your beneficiaries without the expected financial support.
Evaluating Guaranteed Issue Life Insurance
For those who cannot pass a medical exam, "guaranteed issue" life insurance (often marketed as final expense or burial insurance) is frequently the only remaining viable option. As the name suggests, these policies do not require medical exams or invasive health questionnaires.
However, these policies come with significant constraints that are critical to understand:
- Graded Death Benefits: Most guaranteed issue policies feature a "graded benefit" clause. This means that if the insured person dies from natural causes within the first two or three years of the policy, the insurer does not pay the full face value. Instead, they typically refund the premiums paid plus a small percentage of interest.
- Lower Coverage Limits: You will not find million-dollar policies in this category. Coverage amounts are typically capped at $25,000 to $40,000, intended primarily to cover funeral costs, medical bills, or small debts.
- Higher Costs: Because the insurer accepts the risk of covering someone with a known terminal illness without verifying their health, the premiums are significantly higher per dollar of coverage compared to standard policies.
The Role of Group Life Insurance
If you are currently employed, your workplace may offer group life insurance. This is one of the few scenarios where you might obtain coverage without a medical examination, even with a pre-existing condition.
Many companies offer "basic" group life insurance as a fringe benefit, which often requires no health questions for enrollment during the initial hiring period or during specific open enrollment windows. If you are already employed and have not yet opted into your employer's group policy, check your HR documentation to see if there is a "guaranteed issue" amount available to new enrollees.
The downside is that group life insurance is often tied to your employment. If you are unable to continue working due to your health, you may lose the coverage or be forced to pay significantly higher premiums to convert it into an individual policy—if conversion is even an option.
Comparison of Insurance Pathways
| Policy Type | Medical Exam | Coverage Amount | Premium Cost | Eligibility |
|---|---|---|---|---|
| Traditional Term | Required | High | Low | Rarely eligible |
| Whole Life | Required | High | Moderate | Rarely eligible |
| Group Life | Not Required | Moderate | Low | Employer dependent |
| Guaranteed Issue | Not Required | Very Low | High | Almost anyone |
Managing Financial Expectations
When dealing with a terminal diagnosis, financial planning shifts from long-term wealth protection to immediate liquidity and expense management. If you have existing life insurance policies, examine them closely before assuming they are useless or looking for new ones.
Check for "Accelerated Death Benefit" riders. Many permanent and some term life insurance policies include this feature. It allows the policyholder to receive a portion of the death benefit while they are still alive if they are diagnosed with a terminal illness. This can provide essential funds to pay for medical treatments, home care, or final expenses. The payout is usually deducted from the ultimate death benefit that your beneficiaries receive.
Common Mistakes to Avoid
When navigating the insurance landscape during a health crisis, emotions and urgency can lead to poor decisions. Avoid these common pitfalls:
- Falling for "No Exam" Scams: Scammers prey on people who know they have been declined by major carriers. Be wary of any company promising high coverage amounts ($100k+) for very low premiums with no medical questions. If a deal looks too good to be true, it is likely fraudulent.
- Over-insuring: Do not attempt to stack multiple guaranteed issue policies to create a large nest egg. The premiums for these policies are inefficient. Use your resources to pay off high-interest debt or save for immediate needs rather than funneling money into high-cost insurance premiums that may have long waiting periods before the full death benefit is active.
- Ignoring Legal Estate Planning: Life insurance is just one tool. Often, re-evaluating your will, establishing a power of attorney, and organizing existing assets provides more financial security for your family than trying to secure a new, expensive insurance policy.
Engaging Professionals
Working with an independent insurance broker can save time and reduce frustration. Unlike a "captive" agent who only works for one insurance company, an independent broker has access to multiple carriers. They can anonymously run your medical details by underwriters at various companies to see if any firm has niche products for specific cancer types or stages.
Be honest with your broker. Providing them with a full, accurate picture of your diagnosis and medical history allows them to narrow down the companies that might be a fit, saving you the effort of filing applications that are guaranteed to be declined.
Frequently Asked Questions
Can I hide my diagnosis to get a cheaper policy? No. Insurance companies have access to the Medical Information Bureau and your prescription records. Misrepresenting your health is considered fraud and will result in the policy being voided when a claim is filed.
What happens if I die during the waiting period of a guaranteed issue policy? If you pass away during the graded benefit period, the insurance company will typically return all the premiums you have paid to your beneficiaries, usually along with an additional percentage (often 10%) as interest, but they will not pay the full death benefit.
Is it worth applying for traditional life insurance if I am in remission? It depends on how long you have been in remission. Most insurance companies require a specific number of years to pass—often 5 to 10 years—without any signs of cancer before they will consider a standard application.
Can I get life insurance through my spouse’s plan? Possibly. Many employer-sponsored plans offer "spouse life insurance." Depending on the plan design, you might be able to join as a dependent without a medical exam if you enroll during the initial window.
Should I use a life settlement to fund end-of-life care? If you already own a significant permanent life insurance policy, you might consider a life settlement, which is the sale of your policy to a third party. While this provides immediate cash, it is a complex process and should only be discussed with a certified financial planner.
Next Steps for Financial Protection
Your first priority should be to review your current financial landscape. Contact your current insurance provider to inquire about "Accelerated Death Benefits" or "Terminal Illness Riders." If you are employed, speak with your Human Resources department to understand the specifics of your group life insurance and whether you are eligible for any guaranteed increases in coverage.
If you decide to pursue a guaranteed issue policy to cover funeral expenses, verify that the company is licensed in your state and carries a strong financial strength rating (such as an A- or better from A.M. Best). Do not sign a contract until you fully understand the "graded benefit" terms and the exact premium you will be paying. Focus your energy on strategies that provide the most immediate and secure benefit to your survivors, ensuring your resources are directed where they are most needed.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
