
Processing credit card payments on an iPad transforms a standard tablet into a sophisticated point-of-sale (POS) terminal. By leveraging the iPad’s processing power and touchscreen interface, businesses can accept various payment methods—including contactless chips, mobile wallets, and magnetic stripes—by integrating a dedicated payment gateway with external hardware peripherals or software-based solutions.
The Mechanism of iPad-Based Payment Processing
The iPad itself does not contain a built-in magnetic stripe reader or an EMV (Europay, Mastercard, and Visa) chip sensor. Instead, the iPad acts as the central intelligence for a payment ecosystem. When a customer initiates a transaction, the iPad runs a POS application that communicates with a payment processor.
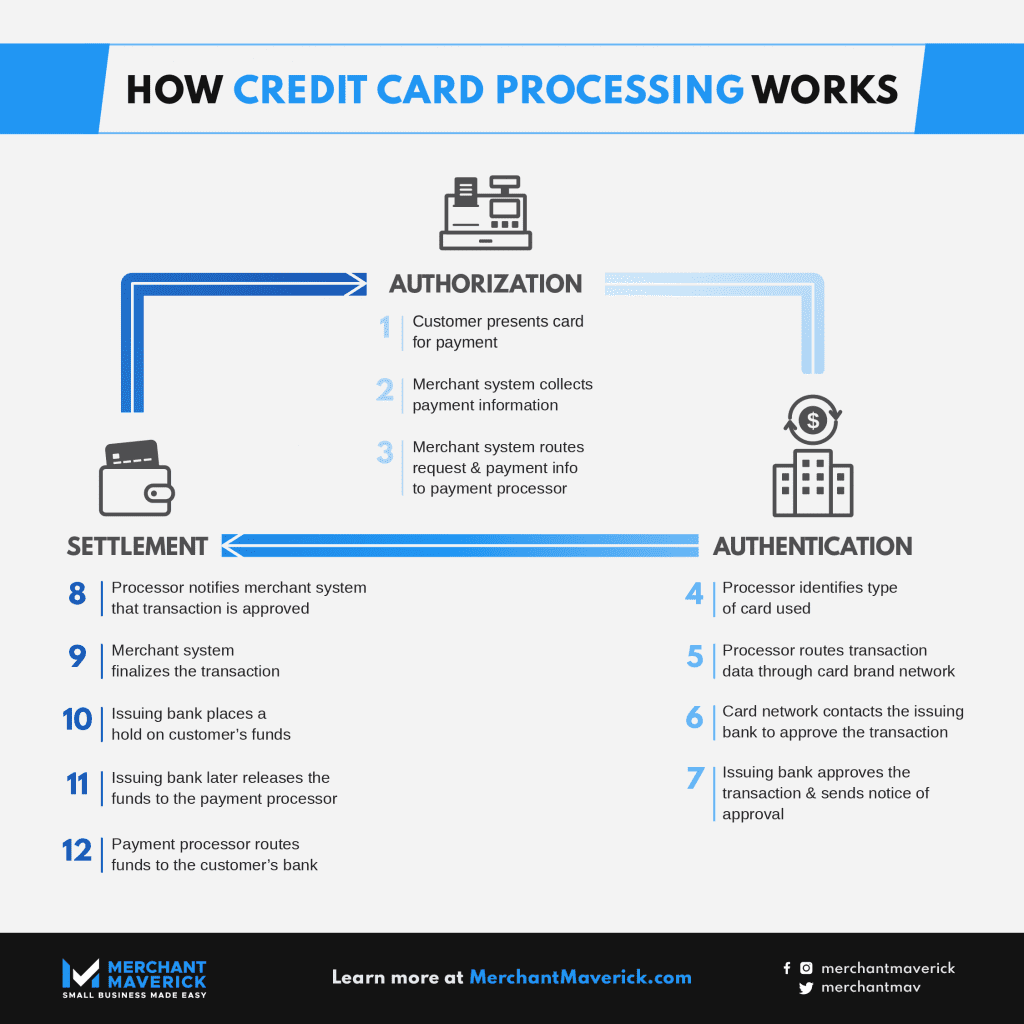
The process follows a standard sequence:
- Data Entry: The merchant enters the transaction amount into the POS app on the iPad.
- Card Interaction: The customer interacts with the card reader (either wirelessly via Bluetooth or via a wired connection).
- Encryption: The payment hardware captures the card’s data and immediately encrypts it. This ensures the iPad never handles raw card data, which is a critical security requirement.
- Transmission: The encrypted data travels through the iPad’s internet connection (Wi-Fi or cellular) to the payment processor’s gateway.
- Authorization: The processor contacts the card-issuing bank to verify funds.
- Approval/Decline: A signal is sent back to the iPad, and the POS app displays the status of the transaction.
Prerequisites for iPad Payment Acceptance
Before a business can begin taking credit card payments, several prerequisites must be met to ensure security and functionality.
- Payment Processor Account: You must have a merchant account with a provider (e.g., Square, Stripe, Shopify, or Toast). This account acts as the bridge between your sales and your business bank account.
- POS Application: A software application is required to manage the inventory, tax calculations, and the payment interface. These apps are downloaded directly from the Apple App Store.
- Hardware Peripherals: Most businesses use a specialized card reader. These range from simple "dongles" that plug into the iPad’s USB-C port to professional-grade countertop terminals that connect via Bluetooth or Wi-Fi.
- Stable Internet Connection: Because authorization happens in real-time, the iPad requires a reliable internet connection. If the connection is lost, many modern apps offer "offline mode," allowing you to swipe cards now and process them once the internet is restored, though this carries a higher risk of chargebacks.
Choosing the Right Hardware Interface
The type of hardware you choose depends on your volume and environment. In 2026, the industry has shifted toward two primary connection methods for iPads.
Bluetooth-Enabled Terminals
These are the most common in modern retail. The reader is a standalone device that pairs with the iPad via Bluetooth. This provides mobility, allowing the merchant to walk around the store or restaurant to collect payment at a table. These readers are generally battery-operated and require regular charging.
Wired USB-C Connections
With the standardization of the USB-C port across current iPad models, some high-volume merchants prefer wired connections. A hub or a direct USB-C connection offers a more stable "always-on" experience, eliminating the need to re-pair Bluetooth devices if the connection drops.
Comparison of Payment Acceptance Methods
| Method | Technology | Primary Benefit | Best For |
|---|---|---|---|
| Contactless (NFC) | Near Field Communication | Extremely fast; hygienic | High-traffic retail, cafes |
| EMV Chip | Integrated Circuit Card | High security; reduces fraud | General retail, services |
| Mobile Wallet | Apple/Google Pay | Consumer convenience | Tech-savvy demographics |
| Manual Entry | Keyed-in numbers | No hardware required | Remote sales, phone orders |
Security Standards and PCI Compliance
Security is the most vital aspect of accepting payments on a mobile device. Because iPads are consumer electronics, they are not inherently PCI-DSS (Payment Card Industry Data Security Standard) compliant on their own. Compliance is achieved by ensuring that the actual handling of sensitive card data is delegated to the hardware reader.
When you use an iPad for payments, the POS app and the card reader use "Point-to-Point Encryption" (P2PE). This means that from the moment the card touches the reader, the data is turned into an unreadable string of characters (a token). Even if the iPad were compromised by malware, the attacker would only ever see the encrypted token, not the actual credit card number. As a merchant, you must ensure your chosen POS app is certified and that your iPad OS is updated to the latest version to maintain these security patches.
Common Operational Challenges and Troubleshooting
Even with robust technology, issues can arise during the payment process. Understanding how to address these quickly is essential for maintaining customer trust.
Connection Failures
If the iPad loses its connection to the card reader, the first step is to verify the Bluetooth or network status in the POS app settings. If using a Bluetooth device, perform a "power cycle"—turn the reader off and back on. Ensure the iPad and the reader are within 30 feet of each other to maintain a stable signal.
Software Glitches
Occasional software freezes are usually tied to an outdated POS app or a full system cache. Ensure you have enabled "Automatic Updates" for your POS app in the App Store settings. If the app becomes unresponsive, performing a "force quit" by swiping up from the bottom of the iPad screen is the standard procedure.
Battery Depletion
For mobile operations, battery management is critical. A merchant should never rely on the iPad’s battery alone for a full day of sales. Using a dedicated POS stand that includes integrated charging ports for both the iPad and the card reader is a best practice.
Frequently Asked Questions
Can I accept credit cards on my iPad without a card reader? Yes, most POS apps allow for "manual entry" or "virtual terminal" processing, where you type the card number, expiration date, and CVV directly into the screen. However, this is significantly more expensive in terms of transaction fees and carries a higher risk of fraud.
Are payments processed on an iPad as secure as traditional registers? Yes. When using a validated hardware reader, the payment is arguably more secure than traditional legacy systems because the data is encrypted at the point of entry and the iPad never stores actual card numbers in its memory.
Do I need a separate data plan for my iPad to take payments? You do not strictly need a cellular data plan; Wi-Fi is sufficient. However, if your Wi-Fi network is unstable, having an iPad with cellular capabilities (LTE or 5G) provides a critical backup, ensuring you can still process transactions if your local internet service provider experiences an outage.
What happens if the power goes out? If your iPad is charged and has a cellular data connection, you can continue to process payments. If your card reader is also battery-powered, your setup remains fully operational during a local power failure.
Is there a limit to how many payments I can take at once? There is no hardware limit on the number of transactions, but your payment processor may have daily volume caps based on your business history. If you anticipate a sudden spike in sales, contact your provider to avoid a temporary hold on your account.
Professional Advice and Next Actions
For businesses transitioning to an iPad-based system, the most important step is selecting an ecosystem that grows with you. Begin by evaluating your monthly transaction volume and your need for mobility. If you are a mobile vendor (like a food truck), prioritize a battery-operated, Bluetooth-enabled reader. If you run a fixed-location storefront, opt for a permanent mounting stand with wired connectivity for reliability.
Before finalizing your setup, audit your business’s cybersecurity policies. Ensure your staff knows never to enter card data into non-authorized note-taking apps on the iPad. Finally, conduct a "dry run" transaction with a personal card to verify that the receipts, tax calculations, and cloud-syncing features are working correctly before your first official business day.

Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
