Navigating auto insurance requirements in ZIP code 48340, which encompasses parts of West Bloomfield, Michigan and surrounding Oakland County communities, requires a clear understanding of Michigan's unique no-fault auto insurance system. Drivers in this region must balance state-mandated minimum coverages—including personal injury protection, residual liability, and property protection—with optional coverages like collision, comprehensive, and higher liability limits to ensure complete financial protection on the road.
Understanding the Geographic and Regulatory Context of ZIP Code 48340
ZIP code 48340 is located in Oakland County, Michigan, an area characterized by dense suburban traffic, highly traveled thoroughfares, and variable weather conditions ranging from heavy winter snowstorms to severe spring thunderstorms. Because auto insurance is heavily regulated at the state level rather than the ZIP code level, motorists registering vehicles in 48340 are subject to Michigan’s unique insurance statutes.
Unlike tort-liability states where accident victims must prove fault to recover damages from another driver, Michigan operates under a mandatory no-fault insurance framework. This system requires every vehicle owner to carry specific insurance coverages before a vehicle can be registered and legally driven on public roads. Understanding how these coverages interact within Oakland County's driving environment is essential for selecting an appropriate policy. Insurance carriers evaluate regional factors such as local vehicle repair costs, regional claim frequencies, and medical costs when establishing premiums for this specific geographic area.
Mandatory Minimum Auto Insurance Coverage Requirements in Michigan
Before examining optional upgrades, every driver in ZIP code 48340 must purchase the state-mandated baseline coverages. Operating a motor vehicle without these components violates Michigan law and can result in severe penalties, including license suspension, fines, and the loss of vehicle registration.
Personal Injury Protection (PIP)
Personal Injury Protection is designed to cover allowable expenses arising from injuries sustained in an automobile accident, regardless of who caused the crash. PIP covers medical treatments, rehabilitation services, attendant care, and a portion of lost wages if an injury prevents the policyholder from working.
Under Michigan insurance reforms, drivers select from several PIP medical coverage levels:
- Unlimited Coverage: Pays for all allowable, reasonably necessary medical expenses for life.
- $250,000 Limit: Caps medical benefits at $250,000 per person per accident.
- $50,000 Limit: Available only to drivers enrolled in Medicaid, with specific restrictions for household members.
- Opt-Out Provision: Available to drivers who have qualified health coverage, such as Medicare Parts A and B, that explicitly covers auto accident injuries.
Residual Liability Insurance
Residual liability insurance protects drivers if they are at fault in an accident that causes severe bodily injury, death, or damage to another person's property outside of Michigan, or under specific tort exceptions within the state. The state-mandated minimum limits are:
- $50,000 for bodily injury or death per person in a single accident.
- $100,000 for total bodily injury or death when multiple people are injured in an accident.
- $10,000 for property damage caused in other states.
While these are the legal minimums, experts frequently recommend higher limits—such as $250,000/$500,000—to protect personal assets from lawsuits resulting from major collisions.
Property Protection Insurance (PPI)
Property Protection Insurance pays up to $1 million for damage your vehicle causes to other people's property, such as buildings, utility poles, fences, or parked vehicles within Michigan. PPI does not cover damage to other moving vehicles unless they are properly parked, nor does it cover damage to your own vehicle.
Optional Auto Insurance Coverage Options Explained
While mandatory coverages satisfy legal requirements, they leave vehicle owners financially vulnerable to vehicle theft, weather damage, or single-vehicle collisions. To bridge these gaps, drivers in 48340 frequently select several optional coverages.
Collision Coverage
Collision coverage pays for repairs to your own vehicle if it is damaged in a crash with another vehicle or an object, such as a guardrail, tree, or building, regardless of who is at fault. If you finance or lease your vehicle, the lender will almost certainly require you to maintain collision coverage.
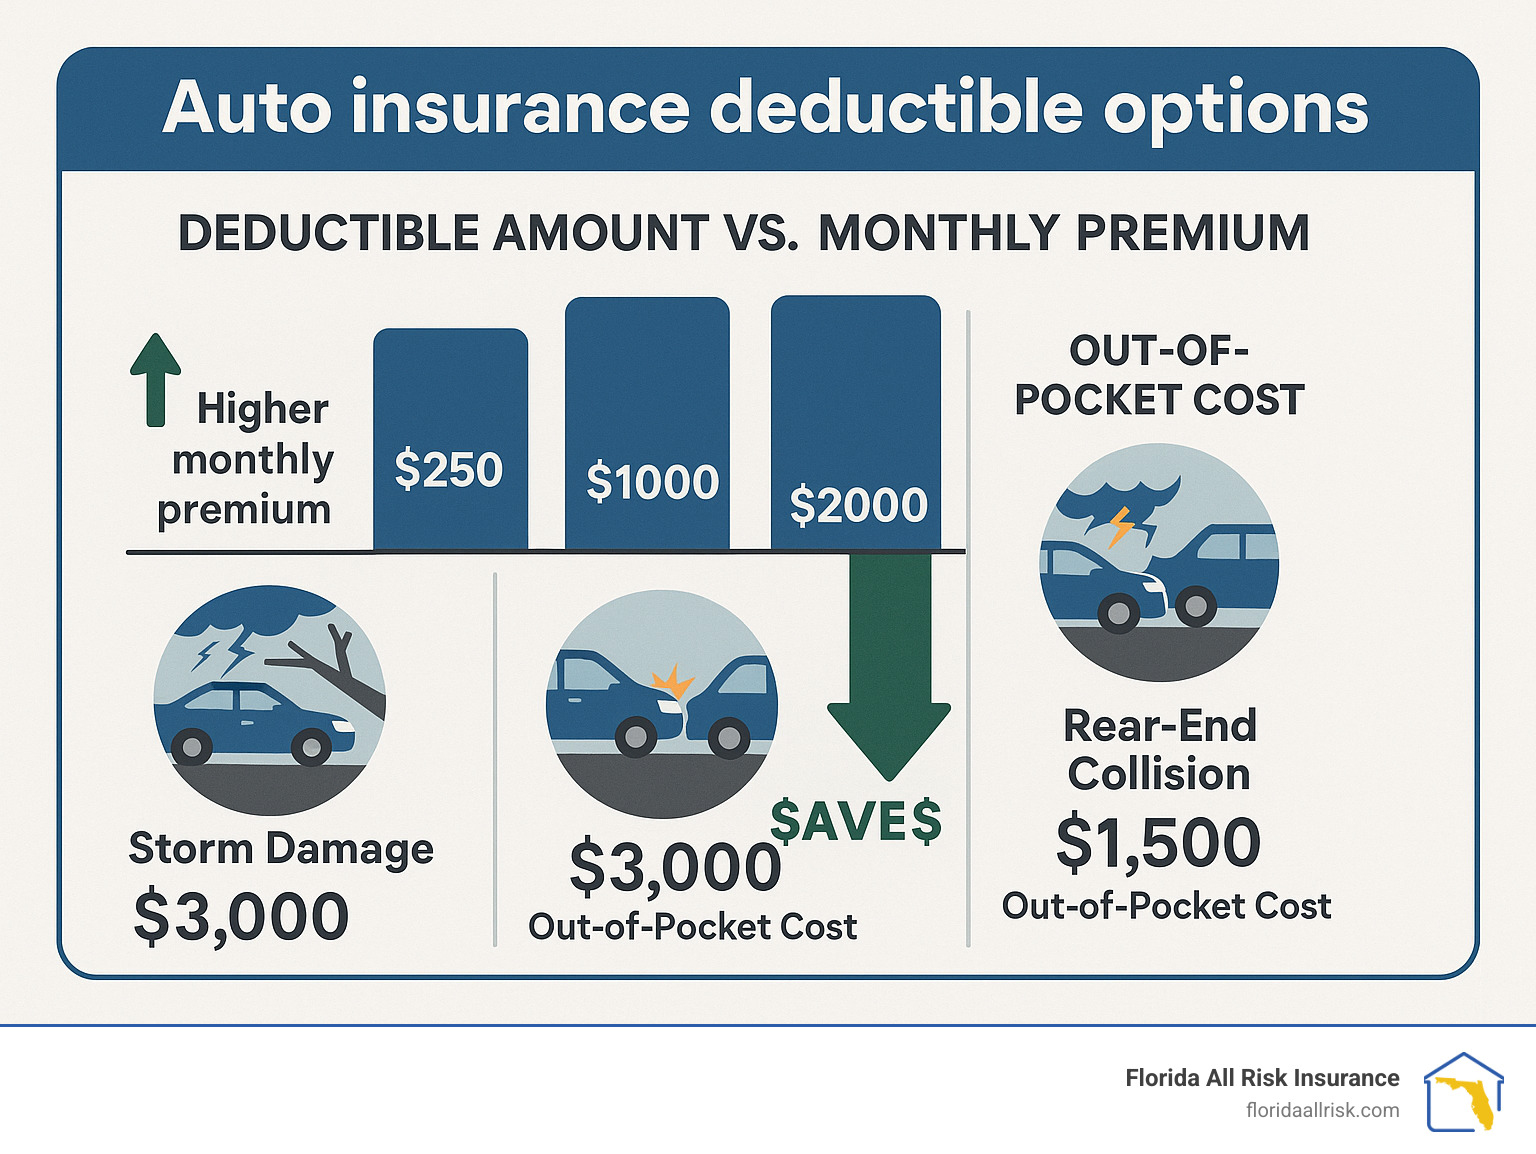
When selecting collision coverage, policyholders must choose a deductible—the amount paid out-of-pocket before insurance funds kick in. Common deductible options range from $250 to $1,000. Selecting a higher deductible lowers the monthly premium, but increases out-of-pocket costs in the event of a claim.
Comprehensive Coverage
Often referred to as "other than collision" coverage, comprehensive insurance protects your vehicle against damage caused by incidents outside of driver control. In the West Bloomfield and Oakland County area, comprehensive coverage is vital for mitigating risks such as:
- Animal strikes, particularly deer collisions common on suburban wooded roads.
- Windshield and glass damage from flying gravel on regional highways.
- Severe weather events, including hail, high winds, and falling tree limbs.
- Vehicle theft and vandalism.
Like collision coverage, comprehensive insurance operates with a deductible and is typically required by auto lenders until the loan is fully paid off.
Uninsured and Underinsured Motorist (UM/UIM) Coverage
Although Michigan law mandates insurance, a percentage of motorists drive without valid coverage. If an uninsured driver hits you, standard no-fault rules apply to medical expenses, but recovering damages for vehicle repairs or pain and suffering can be difficult. Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverages step in to pay for your damages when the at-fault driver lacks adequate insurance or flees the scene in a hit-and-run accident.
Comprehensive Auto Insurance Comparison Table
| Coverage Type | What It Protects | Mandatory or Optional | Key Financial Considerations |
|---|---|---|---|
| Personal Injury Protection (PIP) | Medical bills, rehab, and lost wages from accidents. | Mandatory | Levels range from opt-out to unlimited; dictates medical priority. |
| Residual Liability | Injuries and property damage caused to others. | Mandatory | State minimums are low; higher limits protect personal assets. |
| Property Protection (PPI) | Damage your car causes to stationary property up to $1M. | Mandatory | Fixed limit under state statute; no deductible applies. |
| Collision Coverage | Physical damage to your vehicle from crashes or objects. | Optional (Required by Lenders) | Subject to a deductible; protects vehicle asset value. |
| Comprehensive Coverage | Theft, weather, fire, and animal strikes (e.g., deer). | Optional (Required by Lenders) | Essential for non-collision risks common in suburban areas. |
| Uninsured Motorist (UM) | Injuries caused by drivers with no insurance. | Optional | Provides crucial protection against financially exposed motorists. |
Factors Influencing Auto Insurance Rates in ZIP Code 48340
Auto insurance premiums are not uniform; insurers analyze numerous rating factors to assess risk. Understanding these variables helps policyholders manage costs effectively.
Driving Record and Claims History
An individual's motor vehicle record is one of the most significant pricing components. Speeding tickets, at-fault accidents, and driving under the influence convictions signal higher risk to underwriters, leading to elevated premiums. Conversely, maintaining a clean driving record for three to five years generally qualifies drivers for preferred rates and safe-driver discounts.
Vehicle Make, Model, and Safety Features
The type of vehicle insured directly impacts the cost of coverage. Luxury vehicles, sports cars, and models with expensive electronic sensors embedded in windshields or bumpers cost more to repair, driving up comprehensive and collision premiums. Conversely, vehicles equipped with advanced safety ratings, anti-lock brakes, electronic stability control, and factory-installed anti-theft devices often qualify for specific discounts.
Credit-Based Insurance Scores
In Michigan, insurance companies are permitted to use credit history as a rating factor to help determine insurance premiums. Statistically, insurance companies have found correlations between credit characteristics and the likelihood of filing claims. Maintaining a strong credit history can significantly reduce annual premium costs.
Coverage Selections and Deductibles
The specific policy structure chosen by the consumer directly dictates the price. Opting for unlimited PIP medical benefits, zero deductibles, and high liability limits increases the cost of the policy. Conversely, adjusting PIP limits (if eligible), raising collision and comprehensive deductibles, and dropping unnecessary coverage on older vehicles reduces the overall premium.
Steps to Choose the Right Coverage Mix
Selecting the appropriate auto insurance policy requires an objective assessment of financial exposure, risk tolerance, and asset protection needs.
- Audit Existing Health Coverage: Review employer-sponsored health insurance or Medicare policies to determine whether they cover auto accident injuries fully. If they do, evaluate whether selecting a lower PIP medical limit or opting out is appropriate.
- Evaluate Vehicle Value: Compare the current market value of your vehicle against the cost of collision and comprehensive coverage plus deductibles. If you drive an older vehicle worth less than a few thousand dollars, paying for physical damage coverage may exceed the vehicle's actual cash value.
- Assess Personal Net Worth and Assets: High earners and property owners face greater exposure in liability lawsuits. Purchasing higher residual liability limits and adding a personal umbrella policy provides an essential financial safety net.
- Shop and Compare Quotes: Insurance rates vary significantly between carriers for the exact same coverage profile. Request quotes from multiple licensed insurance providers operating in Michigan to identify the most competitive rate.
- Inquire About Available Discounts: Ask insurance agents about bundling home and auto policies, paperless billing discounts, defensive driving course completions, and multi-car discounts.
Common Auto Insurance Mistakes to Avoid
Navigating Michigan's complex insurance landscape often leads to costly missteps. Avoid these frequent pitfalls:
- Lapses in Coverage: Allowing an auto insurance policy to lapse, even for a few days, can result in the cancellation of vehicle registration by the Michigan Secretary of State, heavy reinstatement fees, and higher future insurance rates.
- Undervaluing Liability Limits: Selecting only the state minimum liability limits to save money leaves personal savings, homes, and future earnings vulnerable if an at-fault accident results in catastrophic injuries.
- Failing to Update Driver Information: Forgetting to notify your insurer about household changes, such as a newly licensed teen driver or a change of address, can lead to denied claims or policy cancellation.
- Ignoring Policy Renewal Notices: Rates frequently fluctuate due to market conditions. Failing to review annual renewal statements can result in paying higher rates without exploring alternative carrier options.
Frequently Asked Questions
What happens if I drive in ZIP code 48340 without auto insurance?
Driving without insurance in Michigan is a misdemeanor punishable by fines up to $500, up to one year in jail, or both. Additionally, the state will suspend your vehicle registration and driver's license, and you will personally forfeit the right to collect no-fault benefits if you are injured in an accident, regardless of who caused it.
Do I need collision coverage if my car is fully paid off?
Collision coverage is optional once a vehicle is fully paid off and no longer tied to a lender. However, you should evaluate whether you can afford to repair or replace the vehicle out-of-pocket if it is totaled in an accident. If losing the vehicle would cause severe financial hardship, maintaining collision coverage remains a prudent choice.
How does Michigan's no-fault medical choice affect my health insurance?
If you choose a capped PIP medical limit (such as $250,000) or opt out entirely using qualified health coverage, your health insurance plan becomes the primary payer for auto accident injuries. It is vital to confirm with your health insurance provider that they do not exclude motor vehicle accidents from coverage before changing your auto policy settings.
Are deer collisions covered by standard auto insurance?
Yes, damage caused by striking an animal—such as a deer commonly encountered in suburban Oakland County—is covered under comprehensive insurance, not collision insurance. Comprehensive coverage is optional unless required by a lienholder, so drivers without this option must pay for animal strike repairs entirely out of pocket.
Can insurance companies in Michigan use my credit score to set rates?
Yes, Michigan law permits insurers to use credit-based insurance scores as one of several rating factors when determining premiums. Maintaining a solid credit history helps secure lower rates, while poor credit can result in higher insurance quotes.
Practical Next Steps for Drivers
Review your current declarations page to verify your PIP selection, liability limits, and deductibles against your actual financial needs. If your policy is up for renewal or your life circumstances have changed—such as paying off a car loan or adding a driver—reach out to licensed independent insurance agents or direct carriers to compare competing quotes across the Michigan market. Taking a proactive approach ensures you remain legally compliant while maintaining robust financial protection on the road.
Image Gallery
Select an image to open it in a new tab.
Vivian Cho
Executive IT and Emerging Technologies Reporter
