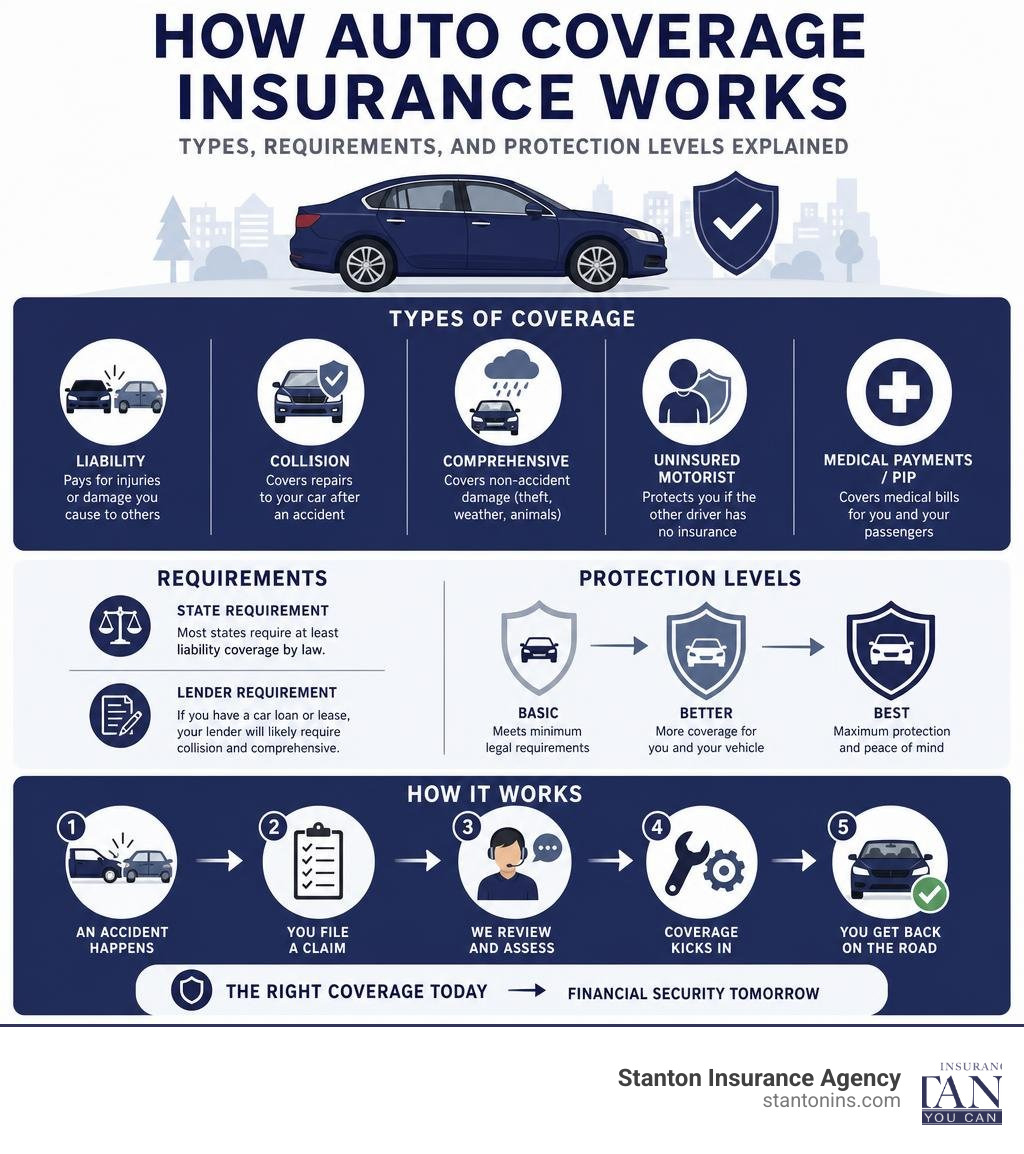
In zip code 29926, which encompasses Beaufort, Lady’s Island, and Port Royal, South Carolina, auto insurance is defined by state-mandated liability minimums of 25/50/25 and required Uninsured Motorist coverage. As of 2026, residents must supplement these basics with comprehensive and collision coverage to protect against specific Lowcountry risks such as coastal flooding and hurricane-related damage.
Understanding the Legal Requirements in South Carolina
Operating a motor vehicle in the 29926 area requires strict adherence to South Carolina’s financial responsibility laws. The state utilizes a tort system, meaning the driver found at fault in an accident is responsible for the damages. To ensure drivers can meet this obligation, the South Carolina Department of Insurance (SCDOI) mandates specific minimum coverage levels that every policy must include.
The standard shorthand for South Carolina’s minimum liability is 25/50/25. These figures represent the maximum amount an insurance company will pay for a single accident:
- $25,000 for Bodily Injury per person: This covers medical expenses, lost wages, and pain and suffering for a single individual injured in an accident you cause.
- $50,000 for Bodily Injury per accident: This is the total cap for all individuals injured in a single incident. If three people are injured and each has $20,000 in medical bills, the $50,000 limit will fall short of the $60,000 total, leaving the policyholder personally liable for the remaining $10,000.
- $25,000 for Property Damage: This covers repairs to the other driver’s vehicle or any property (fences, buildings, signs) damaged in the collision.
Unlike many other states, South Carolina also requires Uninsured Motorist (UM) coverage at these same 25/50/25 levels. This protection is vital in the 29926 region, as it steps in if you are hit by a driver who lacks insurance or if you are the victim of a hit-and-run. While Underinsured Motorist (UIM) coverage is optional, it is frequently recommended for Beaufort residents due to the high cost of modern vehicle repairs and medical care in 2026.
Local Risk Factors Influencing Rates in Beaufort and 29926
The 29926 zip code presents a unique set of environmental and demographic variables that insurers use to calculate premiums. Being a coastal community, Beaufort is subject to geographical risks that differ significantly from inland South Carolina cities like Columbia or Greenville.
Coastal Weather and Flood Risks
The Lowcountry is prone to tropical storms and hurricanes. In 2026, climate-related risks remain a primary driver for Comprehensive Coverage pricing in this area. While liability insurance covers damage to others, only comprehensive insurance protects your vehicle against non-collision events like storm surges, tidal flooding, and falling tree limbs. Residents living on Lady’s Island or near the Beaufort River often find that comprehensive coverage is not just an option but a necessity for financial survival after a major weather event.
Traffic Patterns and Parris Island Proximity
Zip code 29926 includes the Marine Corps Recruit Depot Parris Island and the Beaufort Marine Corps Air Station. This creates a high volume of traffic involving military personnel, many of whom may be temporary residents or young drivers. Insurers account for the higher traffic density on Highway 21 and the frequent influx of visitors for graduation ceremonies. Higher traffic density statistically correlates with a higher frequency of "fender benders" and merging accidents, which can slightly elevate the base premium for the area compared to more rural parts of Beaufort County.
Wildlife and Rural Roadways
Outside the historic district and the main commercial corridors of Port Royal, zip code 29926 transitions into areas with significant wildlife populations. Deer-vehicle collisions are a common occurrence on the shaded, two-lane roads characteristic of the Lowcountry. These incidents are filed under comprehensive claims, making this coverage even more critical for those commuting during dawn or dusk.
Core Coverage Components for 2026
To build a robust policy in 29926, residents must look beyond the state minimums. A "full coverage" policy generally refers to a combination of several different types of protection tailored to the driver’s specific assets and risk tolerance.
Collision Coverage
Collision insurance pays for damage to your own vehicle resulting from an accident, regardless of who is at fault. In 2026, the cost of vehicle repairs has risen significantly due to the integration of Advanced Driver Assistance Systems (ADAS). A simple bumper replacement on a modern electric or hybrid vehicle now often requires recalibrating sensors and cameras, driving up the "severity" of claims in the Beaufort area.
Comprehensive Coverage
As noted, this is the "weather and theft" portion of your policy. For 29926 residents, this covers damage from hurricanes, hail, floods, fire, and theft. It also covers cracked windshields. South Carolina law (S.C. Code § 38-77-280) provides for "full glass" coverage, meaning if you have comprehensive insurance, your insurer must replace or repair your safety glass (windshields) with no deductible. This is a significant benefit in an area where gravel from construction and coastal debris can frequently cause glass damage.
Medical Payments (MedPay)
MedPay is an optional addition in South Carolina that covers medical and funeral expenses for you and your passengers after an accident, regardless of fault. This is often preferred in 29926 because it provides immediate liquidity for health insurance deductibles or emergency room co-pays while waiting for a liability settlement from an at-fault party.
| Coverage Type | SC Requirement | Recommended for 29926 | Why? |
|---|---|---|---|
| Bodily Injury | $25k/$50k | $100k/$300k | Protects personal assets from lawsuits in severe accidents. |
| Property Damage | $25,000 | $100,000 | Modern SUVs and EVs in Beaufort often exceed $25k in value. |
| Uninsured Motorist | Required | Match Liability | High protection against non-compliant drivers. |
| Comprehensive | Optional | Essential | High risk of flood, hurricane, and deer strikes. |
| Collision | Optional | Recommended | Vital if the vehicle is financed or has high resale value. |
| Full Glass | Included in Comp | Yes | SC law waives deductible for windshields if Comp is held. |
Factors That Determine Your Premium
Insurance companies use complex algorithms to determine what a resident in 29926 will pay. While the zip code sets the "base rate," individual factors can cause wide variances in pricing.
- Credit History: In South Carolina, insurers are permitted to use your credit-based insurance score as a factor. Drivers with "Excellent" credit in Beaufort can pay up to 40% less than those with "Poor" credit, as actuarial data suggests a correlation between credit management and driving risk.
- Driving Record: In 2026, telematics (tracking apps) have become the standard for earning the best rates. Drivers in 29926 who allow insurers to monitor their braking, speed, and phone usage via smartphone apps can often see substantial discounts, provided they avoid the heavy traffic congestion around the Broad River Bridge during peak hours.
- Vehicle Type: High-performance vehicles or those with high theft rates will cost more to insure. Conversely, vehicles with high safety ratings and anti-theft devices may qualify for discounts.
- Deductible Levels: Choosing a higher deductible (e.g., $1,000 instead of $500) will lower your monthly premium. However, in a flood-prone area like Beaufort, you must ensure you have the $1,000 readily available in the event of a sudden storm-related claim.
Navigating the Claims Process in Beaufort
If an accident occurs within the 29926 zip code, the actions taken in the immediate aftermath are critical for a successful insurance claim. South Carolina follows a Modified Comparative Negligence rule (the 51% rule). This means you can recover damages as long as you are 50% or less at fault for the accident. If you are found to be 51% or more at fault, you cannot recover any damages from the other party.
Immediate Steps After a Loss
- Report the Accident: Contact the Beaufort Police Department or the Beaufort County Sheriff's Office. A formal police report is the most important piece of evidence in a South Carolina insurance claim.
- Document the Scene: Given the coastal humidity and weather changes in 29926, take clear photos of the damage immediately. Note the street names and any environmental factors (e.g., standing water, obscured signs).
- Exchange Information: Get the name, insurance policy number, and driver's license number of the other party.
- Notify Your Carrier: Most insurers in 2026 offer mobile apps for instant claim filing. Prompt notification is required under the "cooperation clause" of your policy.
The South Carolina Department of Insurance serves as the regulatory body. If you feel a claim is being handled unfairly by a carrier operating in Beaufort, you can file a formal complaint through their Office of Consumer Services.
Strategies for Reducing Insurance Costs
While rates in 29926 are influenced by coastal geography, there are several ways for residents to mitigate high premiums.
- Multi-Policy Bundling: Most major carriers offer a 10% to 25% discount if you bundle your auto insurance with homeowners or renters insurance. This is particularly effective in Beaufort, where homeowners insurance can be expensive due to wind and hail deductibles.
- Affiliation Discounts: Given the military presence in the area, many insurers offer discounts for active duty members, veterans, and their families. This is a primary reason why companies like USAA and GEICO have a strong footprint in the 29926 area.
- Defensive Driving Courses: Drivers over the age of 55 in South Carolina can often receive a mandatory discount by completing an approved accident prevention course.
- Student Discounts: Families with students at Beaufort High School or the University of South Carolina Beaufort (USCB) can benefit from "Good Student" discounts, typically requiring a B average or higher.
Common Mistakes to Avoid
A common error for new residents moving into the 29926 area is maintaining coverage limits from a previous state. For example, if moving from a "No-Fault" state like Florida, the transition to South Carolina’s tort-based system requires a complete re-evaluation of how much liability you carry.
Another mistake is failing to account for the actual cash value (ACV) vs. replacement cost. Most standard auto policies in Beaufort only pay the ACV (depreciated value) of your car. If you have a loan on a vehicle that is totaled in a flood, the insurance check might be less than what you owe the bank. In this scenario, "Gap Insurance" is a vital addition to your 29926 policy.
Frequently Asked Questions
Does my auto insurance cover my car if it's flooded during a hurricane in Beaufort? Only if you have Comprehensive Coverage. Standard liability insurance does not cover any damage to your own vehicle. Because 29926 is a coastal zip code, comprehensive coverage is the only way to protect against rising tides, storm surges, or falling debris during Lowcountry storms.
Are South Carolina insurance requirements different for military personnel at Parris Island? The legal requirements for liability are the same for everyone driving on South Carolina roads. However, military members may have access to specialized insurers and flexible payment plans that account for deployments. It is important to notify your insurer if the vehicle will be stored for an extended period while you are away from the 29926 area.
What happens if I hit a deer on Lady's Island? Hitting an animal is considered a "non-collision" event and is covered under your Comprehensive insurance. In South Carolina, these claims generally do not result in a significant premium increase because they are classified as "not-at-fault" accidents, though frequency can eventually impact your risk tier.
Can I drive in 29926 without insurance if my car is registered in another state? No. If you are living in Beaufort for more than 90 days, South Carolina law generally requires you to register your vehicle and obtain a South Carolina insurance policy. Driving with out-of-state insurance that does not meet SC minimums can result in fines and the suspension of your driving privileges.
Does South Carolina require Personal Injury Protection (PIP)? No, PIP is not mandatory in South Carolina. However, insurers are required to offer you the option to purchase it or MedPay. Most experts recommend Beaufort residents carry at least $5,000 in MedPay to cover immediate medical needs following a collision.
Final Recommendation for 29926 Residents
For those living in the 29926 zip code, the safest path to financial security is to carry insurance limits that exceed the state-mandated minimums. Given the rising costs of medical care and vehicle technology in 2026, a 100/300/100 policy is considered the modern standard for adequate protection. Residents should prioritize adding Comprehensive coverage with a manageable deductible to protect against the specific coastal hazards of the Lowcountry. To ensure the best rates, utilize telematics programs and inquire about military or bundling discounts that are prevalent in the Beaufort and Port Royal markets.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
