Understanding 93906 Auto Insurance Options: A Comprehensive Guide for Salinas Residents

Securing auto insurance in the 93906 zip code requires balancing California’s mandatory minimum liability requirements with the specific risk factors inherent to the Salinas area. To navigate these options effectively, drivers must evaluate their vehicle’s value, their personal financial exposure, and the specific geographic risks of Monterey County, ensuring they maintain compliance with state law while protecting their personal assets.
The Regulatory Landscape: California Mandatory Insurance
In California, auto insurance is not optional; it is a financial and legal necessity regulated by the California Department of Insurance (CDI). Every driver operating a vehicle in the 93906 area must adhere to the state’s minimum financial responsibility laws. These laws are designed to ensure that if you are at fault in an accident, there is a mechanism to compensate the other party for bodily injury or property damage.
The minimum requirements in California are often referred to as "15/30/5" coverage:
- $15,000 for injury or death to one person.
- $30,000 for total injury or death to multiple people in a single accident.
- $5,000 for property damage.
While these minimums fulfill your legal obligation to the state, they are rarely sufficient for modern driving scenarios. Given the high cost of medical care and the value of newer vehicles on the road in 2026, relying solely on state minimums can leave you personally liable for thousands of dollars if you are involved in a significant collision.
Analyzing Geographic Risk in the 93906 Zip Code
The 93906 zip code encompasses parts of Salinas, a region characterized by a mix of dense residential neighborhoods, commercial hubs, and proximity to major agricultural transportation routes. Understanding your local risk profile is essential for selecting the right coverage.
Traffic Density and Commuter Patterns
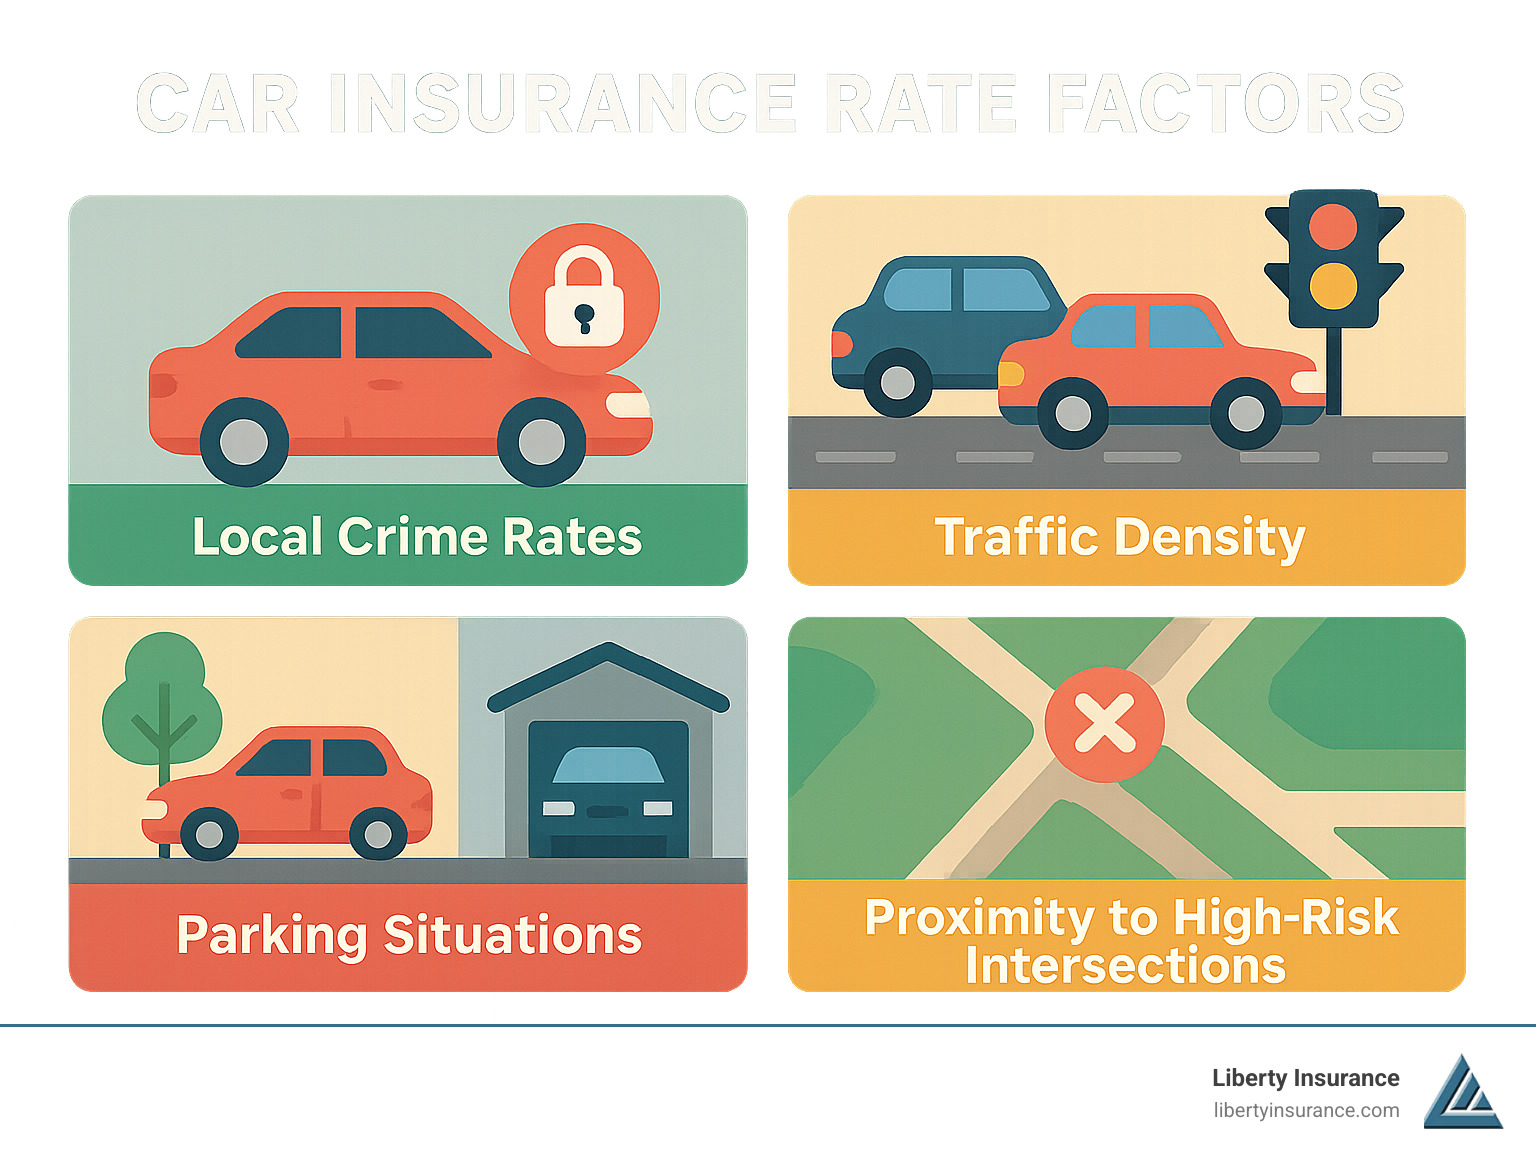
Salinas serves as a central hub for Monterey County, with significant commuter traffic moving toward the Monterey Peninsula or up toward the San Francisco Bay Area via Highway 101. Higher traffic density increases the probability of "fender bender" accidents, making collision coverage a vital consideration. Furthermore, the prevalence of agricultural transit involves heavy trucks and commercial machinery, which adds a unique layer of risk that may not be present in quieter suburban zip codes.
Environmental Factors
While the 93906 area is not typically prone to extreme weather, the California climate does present risks such as seasonal fog affecting visibility on local roads and the potential for wildfire-related air quality issues that can affect vehicle performance and safety. Insurance providers often calculate premiums based on localized data, and being aware of how your specific neighborhood factors into these actuarial models can help you better understand your quoted premiums.

Beyond the Basics: Essential Coverage Types
For most drivers in Salinas, the "mandatory" coverage is merely a starting point. To truly secure your financial future, you should consider a broader spectrum of insurance products.
Liability Insurance (Bodily Injury and Property Damage)
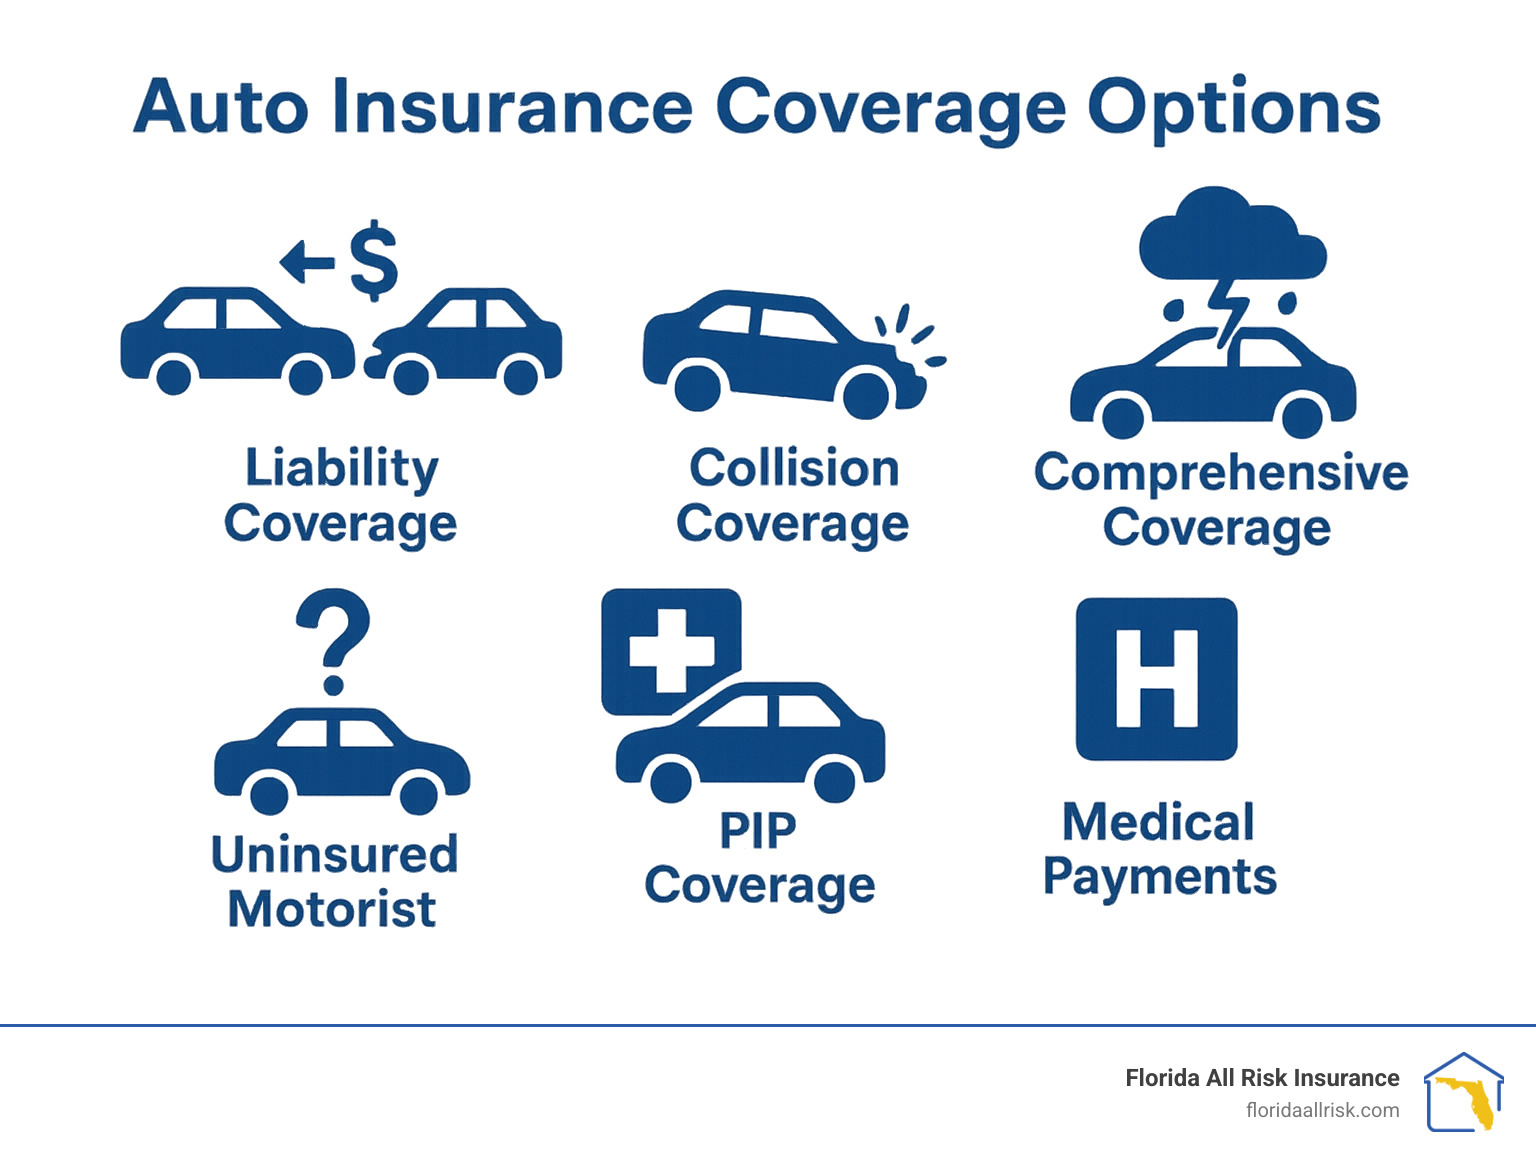
Liability coverage is the bedrock of your policy. If you are found at fault, this coverage pays for the medical bills, lost wages, and repair costs of the other party. In 2026, many experts recommend increasing your liability limits far beyond the state minimum to protect your personal savings, home equity, and future earnings from potential lawsuits.
Collision and Comprehensive Coverage
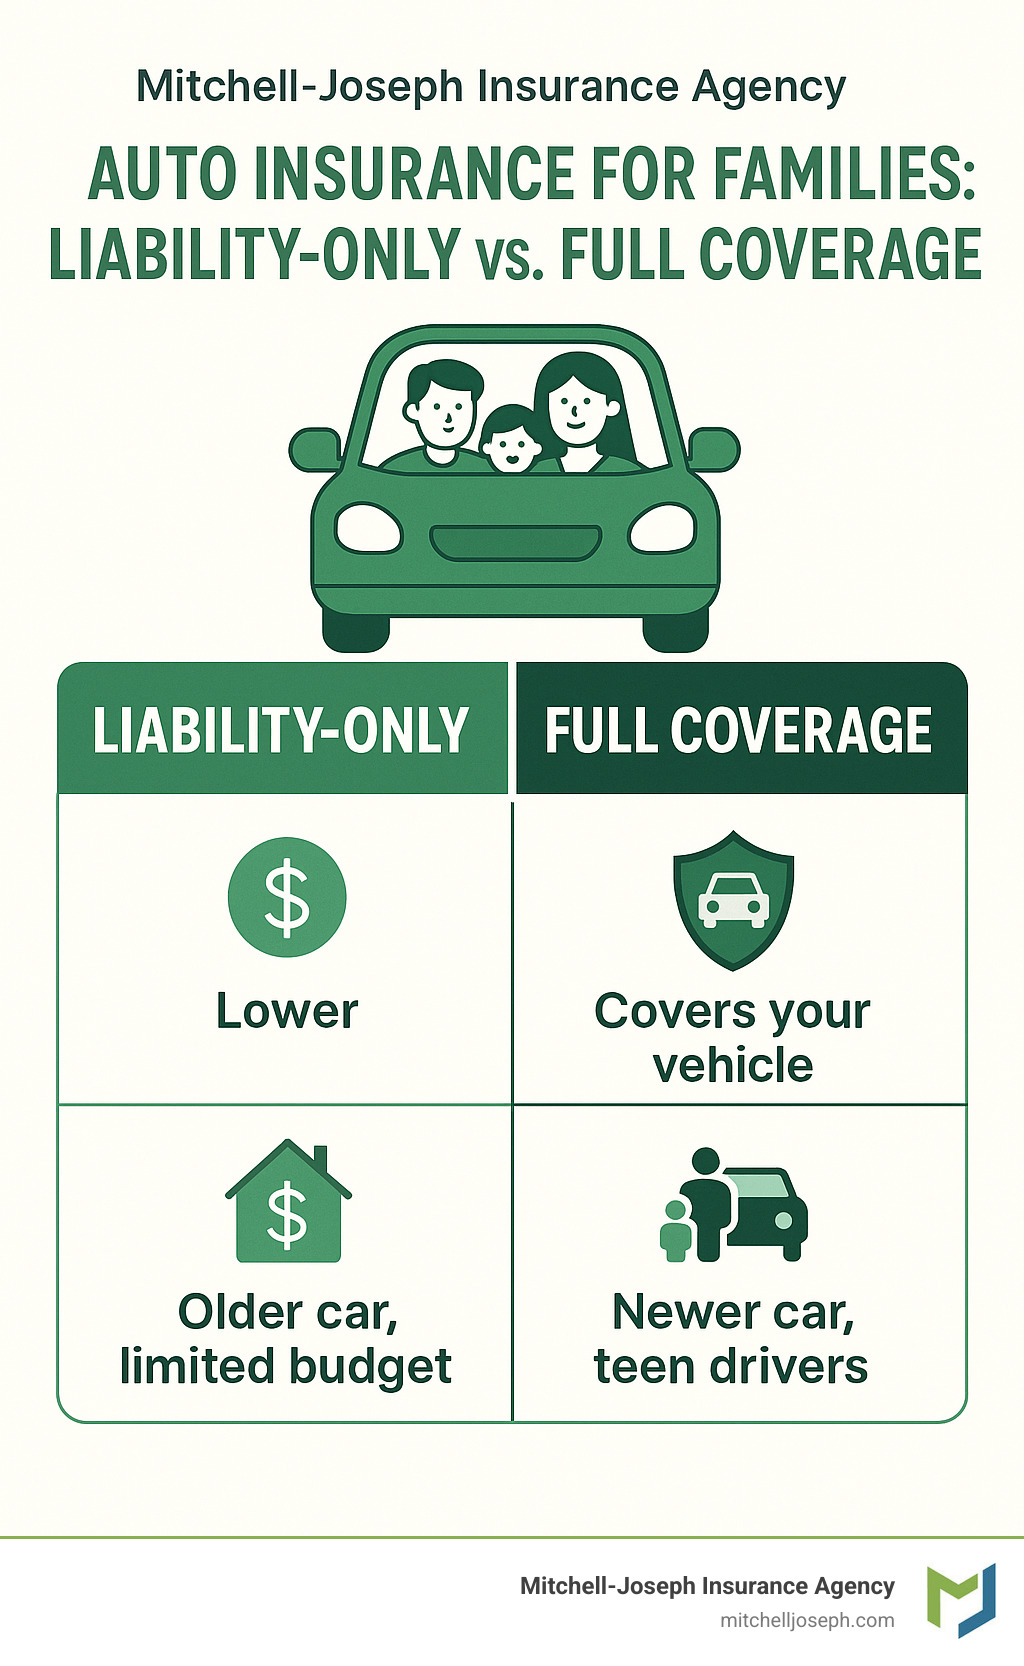
These two components, often bundled together, cover your own vehicle:
- Collision: This pays to repair or replace your vehicle if you hit another car, a pole, or a fence, regardless of who is at fault.
- Comprehensive: This covers "non-collision" events, such as theft, vandalism, fire, or damage caused by falling objects.
If you are financing your vehicle, your lender will almost certainly require these two types of coverage until the loan is fully satisfied.
Uninsured/Underinsured Motorist (UM/UIM)
Given that some drivers may choose to ignore state mandates, UM/UIM coverage is highly recommended. If you are struck by a driver who lacks insurance—or does not have enough coverage to pay for your damages—this policy kicks in to cover your medical bills and vehicle repairs. In high-traffic corridors like those found in the 93906 area, the likelihood of an encounter with an underinsured driver is a tangible risk.
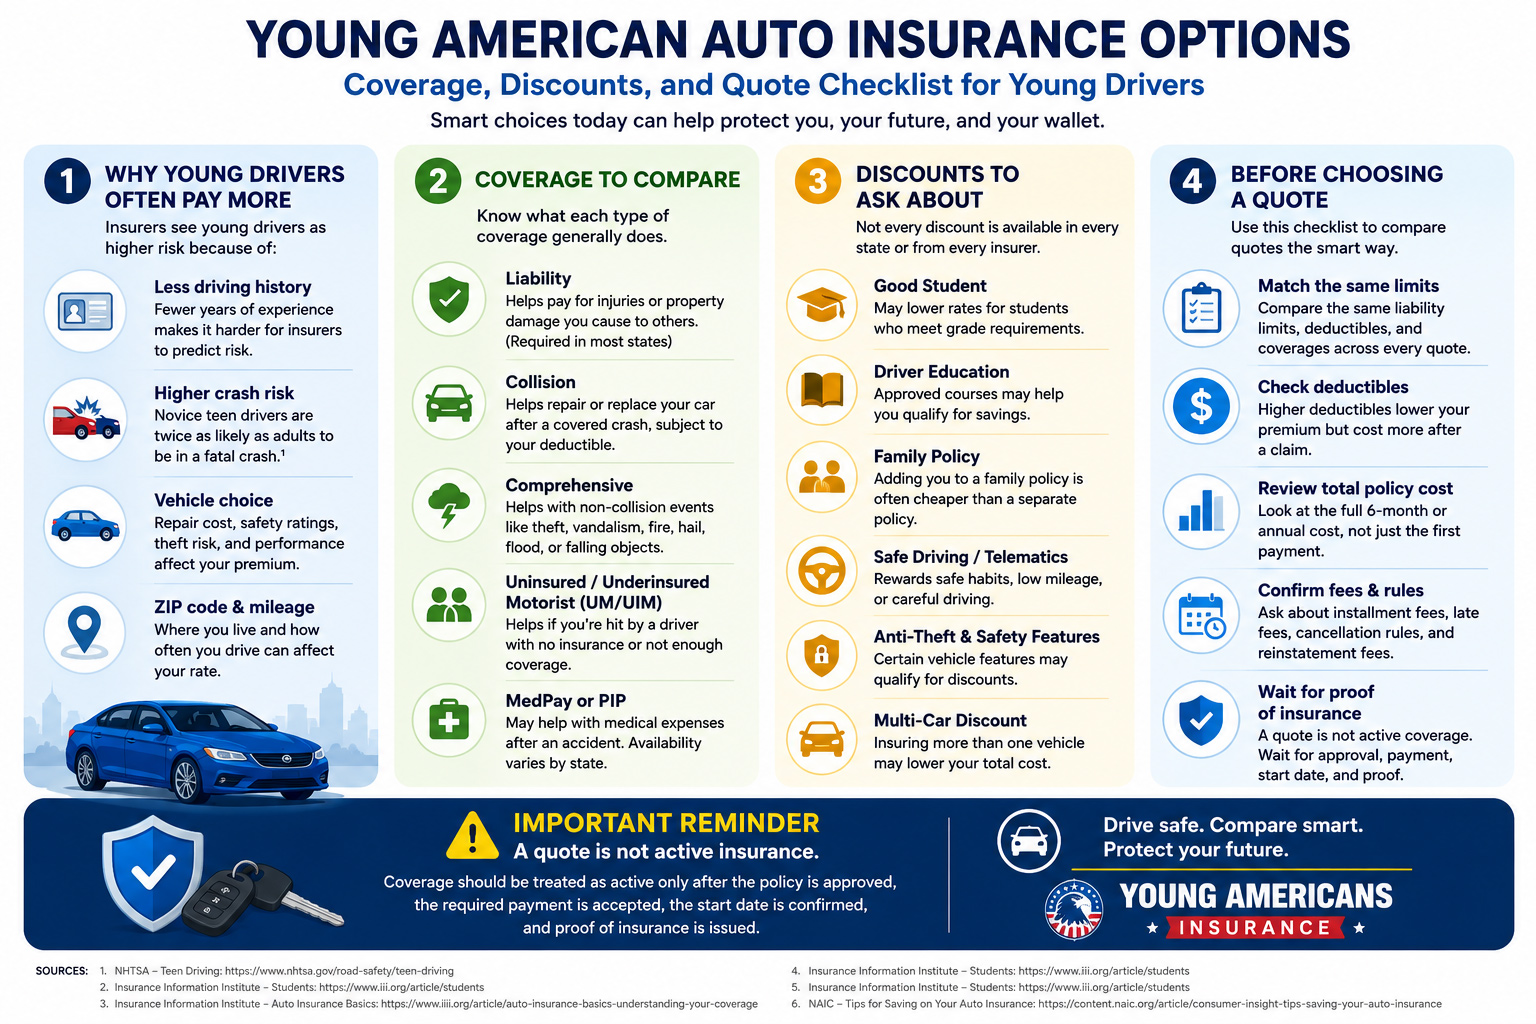
Comparative Overview of Coverage Choices
| Coverage Type | What It Covers | Necessity Level |
|---|---|---|
| Liability | Damage/Injury caused to others | Mandatory |
| Collision | Damage to your car from accidents | Recommended |
| Comprehensive | Theft, vandalism, weather damage | Recommended |
| UM/UIM | Accidents with uninsured drivers | Highly Recommended |
| Medical Payments | Your medical bills (no-fault) | Optional |
Factors Influencing Your Premiums in 2026
Insurance premiums are not arbitrary; they are the result of complex algorithms that factor in both personal and environmental variables.
Driving Record and Experience
Your history of moving violations, accidents, and insurance claims is the primary driver of your premium. A clean driving record for three to five years significantly lowers your risk profile in the eyes of an insurer.
Vehicle Specifications
The year, make, and model of your vehicle play a massive role in your insurance costs. A high-performance car with expensive parts will be significantly more expensive to insure than a standard commuter sedan, even if the driver is the same. In 2026, the rise of advanced driver-assistance systems (ADAS) has created a bifurcation in pricing; while these sensors improve safety, they are also incredibly expensive to calibrate or replace after a collision.
The Role of Credit Scores
In California, there are strict regulations regarding the use of credit scores in determining auto insurance premiums. Unlike in many other states, California law generally restricts insurers from using credit information to set rates. This is a critical distinction that keeps the focus squarely on your driving record and vehicle safety features.
Step-by-Step: Purchasing or Renewing Coverage
If you are currently evaluating your insurance options, follow these systematic steps to ensure you are receiving the best value for your specific needs in 93906.
- Assess Your Current Assets: Before talking to an agent, determine how much protection you actually need. If you have significant assets, you may want higher liability limits.
- Gather Vehicle Documentation: Have your Vehicle Identification Number (VIN), current mileage, and information regarding safety features (e.g., lane-keep assist, automatic emergency braking) ready.
- Request Multiple Quotes: Reach out to at least three different insurers. Compare not just the premium, but the deductible amounts and the coverage limits for each tier.
- Review Exclusions: Read the "Exclusions" section of any prospective policy. Understand what is not covered, such as ride-sharing services (e.g., Uber or Lyft) or business use of the vehicle, which often require supplemental endorsements.
- Verify Licensing: Ensure that all drivers in your household are listed on the policy, as failing to disclose a resident driver can lead to denied claims.
Common Pitfalls and Troubleshooting
Many drivers fall into the trap of focusing solely on the "monthly premium" number. While budget is important, an under-insured driver is essentially one accident away from a financial crisis.
The Deductible Trap
Choosing a high deductible—the amount you pay out-of-pocket before insurance covers a claim—is a common way to lower monthly premiums. However, ensure that the deductible you choose is an amount you could actually afford in an emergency. If you choose a $2,000 deductible to save $20 a month, but you do not have $2,000 in savings, the policy may fail to serve its purpose when you need it most.
Ignoring Policy Renewals
In 2026, insurance markets are dynamic. Your "loyal" rate might be higher than the rate offered to a new customer. Set a calendar reminder to review your policy 30 days before its expiration date. Check if your current insurer is still competitive or if changes in your life (e.g., a shorter commute, a new safety feature on your car, or the age of a household driver) qualify you for new discounts.
Frequently Asked Questions (FAQ)
Does my 93906 zip code specifically raise my rates?
Zip codes are part of the "territory rating" used by insurers. If 93906 experiences higher rates of vehicle theft or accident frequency compared to neighboring regions, it can impact your premium. However, insurers must file their rating plans with the California Department of Insurance to ensure they are not unfairly discriminatory.
How do I prove I have insurance in California?
California requires drivers to carry proof of insurance in their vehicle at all times. This can be a physical insurance card or an official digital version displayed on a smartphone. Failure to provide proof when requested by law enforcement can lead to fines and, in some cases, vehicle impoundment.
Can I bundle my 93906 auto insurance with my home insurance?
Yes, most major carriers offer "multi-policy" or "bundling" discounts. If you own a home or rent an apartment in Salinas, combining your auto and home/renters insurance under one carrier often results in a lower aggregate cost and more streamlined billing.
Are there specific discounts for low-mileage drivers?
Yes. If you work from home or use public transportation, notify your insurer. Many carriers offer "low mileage" discounts for individuals who drive fewer than a certain threshold of miles per year. Ensure you can provide an accurate odometer reading if requested.
What should I do if I am unhappy with my current insurer’s claim process?
If you feel your claim was mishandled, start by speaking with your agent or the company's internal claims ombudsman. If the issue remains unresolved, you can file a formal complaint with the California Department of Insurance, which oversees all consumer grievances regarding insurance practices.
Final Recommendation
Your auto insurance is a critical tool for risk management, not just a line item on your monthly budget. For residents in 93906, the ideal strategy for 2026 is to carry liability limits that exceed state minimums, maintain adequate collision and comprehensive coverage, and conduct an annual review of your policy to capture any new discounts. By proactively managing your coverage, you ensure that you are protected against the unpredictable nature of the road.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
