
Finding the right auto insurance in Lawrence, Massachusetts, requires understanding the state’s unique "no-fault" insurance system, mandatory coverage minimums, and how urban density in Essex County influences local premium calculations. As a Massachusetts driver, you must secure a Standard Massachusetts Auto Insurance Policy, which is strictly regulated by the Division of Insurance to ensure consistency across providers while allowing for competitive pricing based on your driving history and specific vehicle attributes.
Understanding Massachusetts Mandatory Auto Insurance Laws
Massachusetts operates under a mandatory "no-fault" auto insurance system, often referred to as Personal Injury Protection (PIP). This structure is designed to expedite the payment of medical bills and lost wages following an accident, regardless of who caused the collision. Because the state mandates these coverages, every insurance carrier operating in Lawrence must provide the same basic policy framework.
The Four Mandatory Coverage Components
To register a vehicle in Massachusetts, you must prove you carry the following four types of coverage:
- Bodily Injury to Others: This covers damages you are legally responsible for if you cause an accident that results in injury or death to someone else. The minimum limit is $20,000 per person and $40,000 per accident.
- Personal Injury Protection (PIP): This pays for medical expenses, lost wages, and replacement services for you, your passengers, and any pedestrian injured by your car, up to $8,000.
- Bodily Injury Caused by an Uninsured Auto: This protects you if you are injured by someone who has no insurance or is a hit-and-run driver.
- Damage to Someone Else’s Property: This pays for damage your vehicle causes to another person’s property, such as a fence, building, or another vehicle. The state minimum is $5,000.
Factors Influencing Premiums in Lawrence
When shopping for the top auto insurance in Lawrence, you will notice that quotes vary based on factors specific to your profile and the city’s environment. Insurance companies utilize "actuarial data" to assign risk levels to specific zip codes.
Impact of Urban Density and Risk
Lawrence is a densely populated city with a high volume of traffic compared to more rural parts of Massachusetts. Insurance carriers consider the following variables when calculating premiums for Lawrence residents:
- Theft and Vandalism Rates: Higher-density urban areas often statistically correlate with higher instances of vehicle theft and vandalism, which can increase the cost of "Comprehensive" coverage.
- Traffic Accident Frequency: The complexity of navigating local intersections and the volume of commuters influence the likelihood of filing a claim.
- Vehicle Usage: Your annual mileage and whether you use your vehicle for commuting to Boston or locally within Lawrence will change your risk profile.
Personal Rating Factors
Beyond your location, carriers in 2026 continue to weigh these personal factors:
- Driving Record: The Massachusetts Safe Driver Insurance Plan (SDIP) is a merit rating system. Points are assigned for at-fault accidents and traffic violations, which directly increase your premiums for up to six years.
- Experience: Younger, less experienced drivers generally pay significantly higher premiums due to higher statistical risk profiles.
- Vehicle Type: Modern vehicles equipped with advanced safety features (e.g., automatic emergency braking, lane-keep assist) may qualify for discounts, whereas vehicles with high repair costs may command higher premiums.

Optional Coverages for Enhanced Protection
While the state requires the four components mentioned above, many Lawrence drivers opt for additional coverage to protect their assets from litigation and out-of-pocket repair costs.
- Optional Bodily Injury to Others: This increases the limits beyond the state minimum, protecting your personal assets if you are sued for a major accident.
- Collision Coverage: This pays for damage to your car caused by a collision with another object or vehicle, regardless of fault.
- Comprehensive Coverage: This covers non-collision events, including theft, vandalism, fire, and glass damage.
- Medical Payments: This acts as an additional layer of coverage on top of PIP to pay for medical expenses for you and your passengers.
- Gap Insurance: If you are currently financing or leasing a vehicle and the balance of your loan exceeds the car's actual cash value, Gap insurance pays the difference if the vehicle is totaled.
Comparative Overview of Coverage Types
| Coverage Type | Status | Protection Scope |
|---|---|---|
| Bodily Injury (Mandatory) | Required | Injuries caused to others in an at-fault accident. |
| PIP (Mandatory) | Required | Medical/Lost wages for occupants of your vehicle. |
| Property Damage (Mandatory) | Required | Damage caused to others' property/vehicles. |
| Collision (Optional) | Recommended | Repair costs for your vehicle from an accident. |
| Comprehensive (Optional) | Recommended | Theft, fire, and weather damage to your vehicle. |
| Towing & Labor (Optional) | Recommended | Roadside assistance for breakdowns or towing. |
How to Obtain and Verify Insurance in Lawrence
Securing a policy in Lawrence is a streamlined process. Most residents work through an independent insurance agent, though direct-to-consumer digital platforms have become increasingly common in 2026.
Steps to Secure Your Policy
- Gather Necessary Documentation: You will need your current driver’s license, vehicle identification number (VIN), current mileage, and a history of any previous insurance claims.
- Request Multiple Quotes: Obtain quotes from at least three different carriers. Even though the state regulates the core policy, individual carriers have different risk appetites and "discretionary discounts."
- Evaluate Coverage Limits: Do not simply opt for the state minimums if you have significant personal assets or a high-value vehicle. Increasing your limits to $100,000/$300,000 for bodily injury is often relatively inexpensive.
- Confirm RMV Compliance: Once you purchase a policy, your insurer will issue an "Insurance Binder" or electronically transmit the Registration and Title Application (RTA) form to the Massachusetts Registry of Motor Vehicles (RMV).
Common Mistakes to Avoid
Many drivers settle for the first quote they receive, which can lead to missed savings or inadequate coverage.
- Ignoring Deductibles: Choosing the lowest deductible ($200–$300) will keep your out-of-pocket costs low during a claim but will significantly raise your monthly premium. Selecting a $1,000 deductible is a common way to lower annual costs.
- Failing to Bundle: If you have renters or homeowners insurance, keep your auto policy with the same carrier. Most companies offer a "Multi-Policy Discount" that can reduce the total cost of your insurance package.
- Neglecting Safety Equipment Updates: If you have installed aftermarket security devices or if your car has factory-installed anti-theft systems, inform your agent. These can yield significant premium reductions.
Frequently Asked Questions
Is it cheaper to buy insurance online or through a local agent in Lawrence?
There is no universal rule, but local agents in Lawrence often provide better value by identifying "bundled" discounts you might miss online. An agent can also act as an advocate if you encounter issues during the claims process.
Can I change my auto insurance carrier at any time during the year?
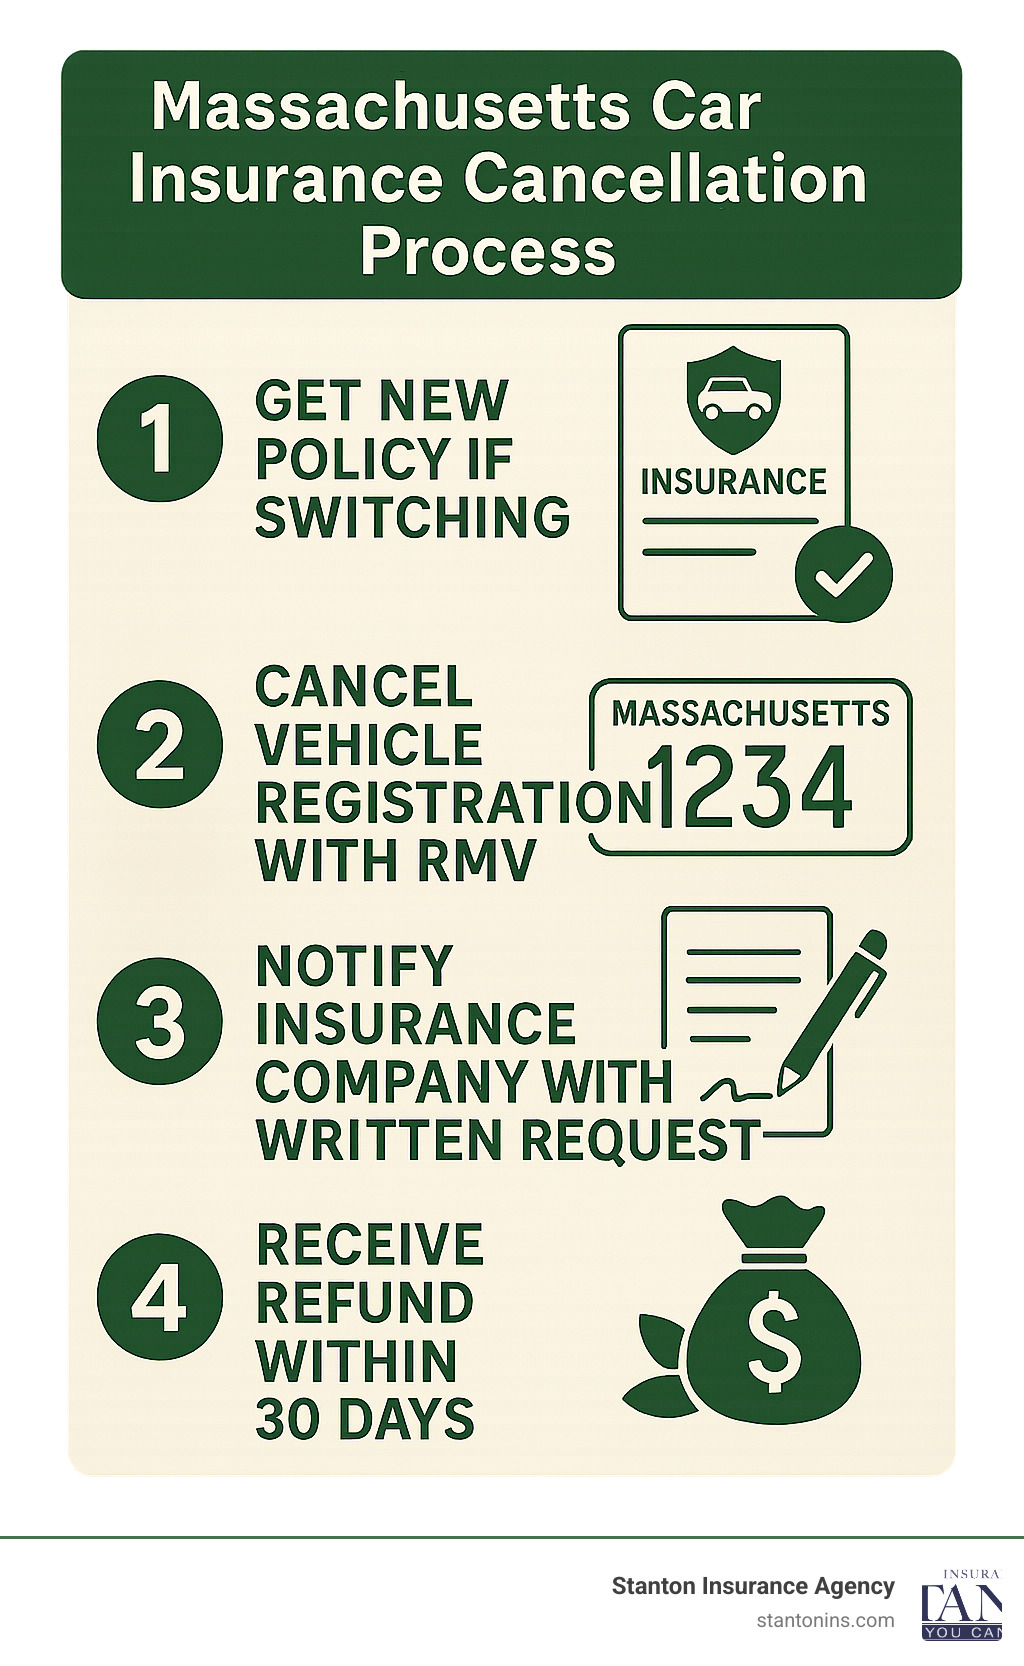
Yes, you can cancel your current policy and switch to a new one at any time. However, ensure that your new policy is active and the RMV has been notified before you cancel the old one to avoid a lapse in coverage, which can lead to significant premium penalties.
Does my credit score affect my insurance rates in Massachusetts?
Massachusetts law specifically prohibits insurance companies from using credit scores to determine auto insurance premiums. This distinguishes Massachusetts from many other states where credit-based insurance scoring is a primary factor in pricing.
What should I do if I’m involved in an accident in Lawrence?
First, ensure the safety of all parties. Contact the Lawrence Police Department to file an official report, regardless of the severity of the damage. Exchange insurance and contact information with the other driver, and notify your insurance company as soon as possible to begin the claim filing process.
How do I verify that my insurance carrier is licensed?
You can visit the Massachusetts Division of Insurance website to search the "Producer and Company" database. This ensures the company is authorized to conduct business in the Commonwealth and is subject to state regulatory oversight.
Next Steps for Lawrence Drivers
To identify the best policy for your needs, start by auditing your current driving habits and the financial protection you require. If you are a high-mileage commuter, prioritize higher liability limits. If you have an older, paid-off vehicle, consider whether the cost of "Collision" and "Comprehensive" exceeds the total value of the car. Use the current year, 2026, as an opportunity to review your policy declarations page, contact your provider, and inquire about unapplied discounts for safety features or membership associations.
Image Gallery
Select an image to open it in a new tab.




Declan O'Connor
Higher Education and Campus Culture Reporter
