
When an accident happens, navigating the aftermath requires balancing medical recovery, vehicle repairs, and complex communication with insurance providers. Among the most critical yet frequently misunderstood elements of this process are the strict time limitations governing auto insurance claims. Missing a designated deadline—whether it is the window for reporting an incident to your insurer, filing a formal claim, or initiating legal action—can mean the complete forfeiture of your right to financial recovery. Understanding how these time limits work ensures you protect your rights, secure necessary compensation, and avoid costly administrative pitfalls.
The Foundation of Auto Insurance Time Limits
Insurance policies are legal contracts governed by specific contractual terms and state statutes. When you purchase auto insurance, you agree to abide by the conditions outlined in the contract, which almost universally include clauses specifying when and how you must report accidents and losses.
These stipulations are not mere bureaucratic red tape; they serve fundamental operational and legal functions. Insurers require prompt notification to investigate accidents while evidence is fresh, vehicles can still be inspected in their damaged state, and witnesses retain clear memories of the events.
Time limitations generally fall into three distinct categories:
- Reporting Deadlines: The timeframe within which you must notify your insurance company that an accident or loss has occurred.
- Proof of Loss Deadlines: The window to submit formal documentation, medical bills, repair estimates, and completed claim forms.
- Statutes of Limitations: State-mandated legal deadlines establishing how long you have to file a lawsuit against an at-fault driver or your own insurer.
Failing to meet any of these thresholds can result in claim denial, regardless of who was at fault for the accident.
Decoding Policy-Level Reporting Deadlines
The policy-level deadline is dictated by the language inside your specific insurance contract. Most auto insurance policies state that you must report an accident "as soon as practicable" or within a specific numeric window, such as 24 to 72 days, or simply "promptly."
What "As Soon as Practicable" Means
In legal and insurance terms, "as soon as practicable" does not necessarily mean the exact moment the airbag deploys. It accounts for extenuating circumstances, such as being hospitalized or incapacitated due to severe injuries. However, it does place a reasonable burden of diligence on the policyholder. Waiting weeks to report an incident simply because you were busy or assumed the damage was minor can give the insurer grounds to deny coverage under the defense of "late reporting prejudice"—meaning the delay hindered their ability to investigate fairly.
Why Immediate Notification Protects Your Claim
Insuring companies rely heavily on early evidence collection. Prompt reporting allows adjusters to:
- Inspect vehicle damage before parts are discarded or repaired.
- Interview witnesses while details are sharp.
- Access police reports and traffic camera footage before they are archived or deleted.
- Mitigate further damage to the insured property.
Delaying notification breeds suspicion, and adjusters may view late-reported claims with heightened scrutiny, increasing the likelihood of a protracted claims adjustment process or outright denial.
Statutes of Limitations: The Legal Backstop
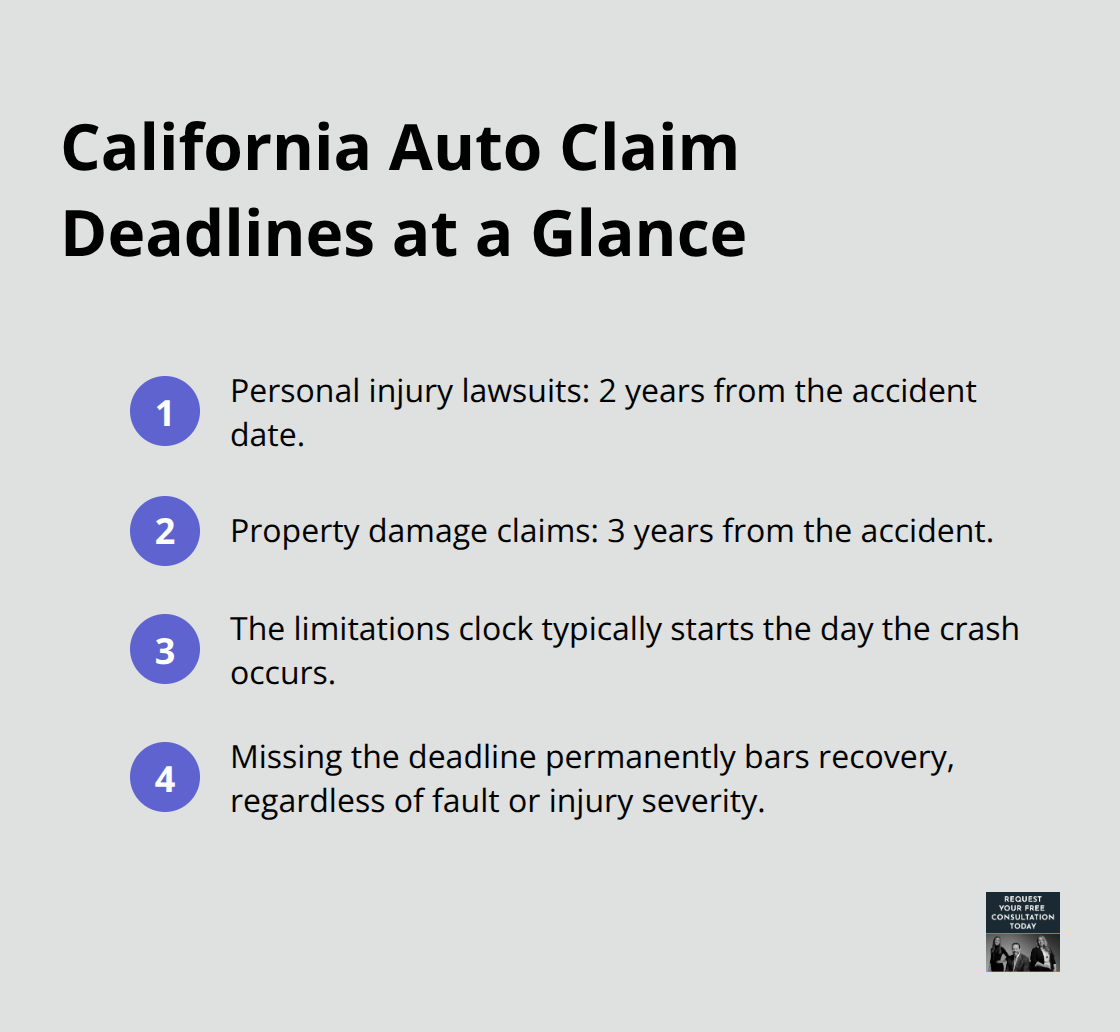
While policy notification windows dictate your relationship with your insurance provider, state statutes of limitations govern your right to seek legal remedies through the court system. These laws establish hard stop dates for filing personal injury or property damage lawsuits against negligent parties.
Property Damage vs. Personal Injury Deadlines
States distinguish between damage to vehicles and injuries sustained by drivers or passengers. Generally, property damage statutes of limitations range from two to three years, whereas personal injury statutes vary widely by jurisdiction, often spanning from one to six years from the date of the accident.
For example, a driver in California typically has two years to file a personal injury lawsuit, while a driver in New York may have up to three years. In contrast, states with no-fault insurance systems introduce unique thresholds that dictate when you can step outside the administrative system to sue an at-fault driver directly.
The Danger of Ongoing Negotiations
A common and perilous trap for claimants is assuming that ongoing settlement negotiations with an insurance adjuster pause or "toll" the statute of limitations. They do not.
Adjusters may drag out discussions, request repeated medical updates, or delay evaluations until the statute of limitations approaches or expires. Once that legal deadline passes, your leverage evaporates entirely because you lose the ability to file a lawsuit. Without the threat of litigation, insurance companies have little incentive to offer a fair settlement.
Comparative Overview of Auto Insurance Claim Timeframes
To better visualize how different deadlines interact during the claims lifecycle, review the standard time thresholds outlined below. Note that exact periods depend entirely on your state of residence and specific policy contract.
| Type of Deadline | Standard Timeframe | Purpose / Consequence of Missing |
|---|---|---|
| Accident Reporting | 24 hours to 30 days (per policy) | Notify insurer of the incident; risk of claim denial for late notice. |
| Uninsured Motorist Notice | Often 30 to 90 days | Notify insurer of potential UM/UIM claim; strict compliance required. |
| Proof of Loss Submission | 30 to 90 days after insurer request | Provide formal financial and medical documentation to support the claim. |
| Personal Injury Statute | 1 to 6 years (state-dependent) | Legal deadline to file a lawsuit for bodily injury; permanent loss of right to sue. |
| Property Damage Statute | 2 to 5 years (state-dependent) | Legal deadline to file a lawsuit for vehicle/property loss. |
Special Scenarios: Uninsured Motorists and Government Entities
Navigating time limitations becomes exponentially more complex when special circumstances are involved. Standard reporting rules often give way to specialized, highly restrictive timelines in specific scenarios.
Uninsured and Underinsured Motorist (UM/UIM) Claims
If you are hit by a driver who lacks insurance or carries insufficient coverage, you may turn to your own policy's UM/UIM provisions. Insurance policies frequently enforce strict, abbreviated notice requirements for UM/UIM claims—sometimes requiring notification within 30 days of the accident, even if you did not immediately realize the other driver lacked insurance. Failing to notify your insurer promptly under these provisions can jeopardize your ability to collect under your own coverage.
Accidents Involving Government Vehicles
When a municipal, state, or federal vehicle is involved in an accident, standard statutes of limitations do not apply in the traditional sense. Sovereign immunity laws require claimants to file a formal notice of claim with the appropriate government agency within an extremely compressed window—frequently ranging from 30 to 180 days from the date of the incident. Missing this administrative notice window bars you from ever filing a lawsuit, regardless of how clear the government driver's liability may be.
Common Mistakes That Lead to Missed Deadlines
Even well-intentioned policyholders frequently undermine their claims by falling into predictable behavioral traps. Recognizing these pitfalls helps safeguard your financial recovery.
- Waiting for Medical Symptoms to Subsides: Adrenaline masks pain immediately following a crash. Waiting weeks to see a doctor not only harms your physical recovery but also creates a gap in the medical timeline that insurers use to argue your injuries were unrelated to the accident.
- Believing Verbal Agreements: Relying on an at-fault driver’s promise to pay out-of-pocket without involving insurance wastes valuable days while you wait for cooperation that may never materialize.
- Assuming Auto and Health Insurers Coordinate Automatically: Delaying your auto claim while sorting out health insurance billing can push you past critical notification or proof-of-loss thresholds.
- Ignoring Policy Renewals and Endorsement Changes: Insurers occasionally update policy terms and shorten reporting windows during annual renewals. Always review changes to your contract declarations.
Strategic Action Steps to Protect Your Timeline
Mitigating the risk of a missed deadline requires proactive organization and disciplined communication from day one. Implementing a structured protocol immediately following a collision ensures all administrative and legal requirements are met.
- Document Everything Immediately: Take photographs of the scene, vehicle damage, and visible injuries. Secure a copy of the police report or obtain the police report number and responding officer's badge information.
- Notify Your Insurer Promptly: Contact your insurance provider within 24 hours of the accident to report the incident, even if you are not sure whether you want to file a claim. Stick to the basic facts and avoid admitting fault or speculating about your injuries.
- Establish a Dedicated Claims Calendar: Record every deadline provided by your insurance adjuster, including dates for submitting proof of loss, medical documentation, and independent medical examinations (IMEs). Set alerts on your digital devices well in advance of each date.
- Consult Legal Counsel Early: If liability is contested, injuries are severe, or the insurance adjuster is unresponsive, consult a qualified personal injury attorney. Legal representation ensures that statutes of limitations are monitored and filed long before the state deadlines expire.
Frequently Asked Questions
What happens if I report my auto accident a few days late?
While minor delays are sometimes excused if you have a valid reason (such as hospitalization), a late report gives the insurer grounds to investigate whether the delay prejudiced their ability to defend the claim. If they can prove the delay compromised their investigation, they can legally deny coverage.
Does calling the police satisfy my insurance reporting requirement?
No. Filing a police report creates an official public record of the accident, but it does not notify your insurance company. You must independently contact your insurer to initiate the claims process according to your policy's guidelines.
Can an insurance adjuster extend my policy's proof-of-loss deadline?
Yes, insurers can grant extensions, but any extension should be requested and confirmed in writing. Never rely on a verbal promise from an adjuster that a deadline has been waived or extended.
What is the difference between a statute of limitations and a policy deadline?
A policy deadline is a contractual requirement set by your insurance company regarding how quickly you must report or document a claim. A statute of limitations is a state law establishing the maximum time you have to file a civil lawsuit in court against an at-fault party.
Does the statute of limitations pause if I am a minor when the accident occurs?
In many jurisdictions, the statute of limitations for personal injury is "tolled" (paused) for minors until they reach the age of majority (usually 18). However, property damage claims or specific municipal notice requirements may still apply, making legal counsel essential.
Conclusion
Navigating the aftermath of a car accident is undeniably stressful, but treating time limitations with urgency is non-negotiable. Whether dealing with internal policy reporting rules or state-enforced statutes of limitations, understanding these deadlines puts you in control of your financial recovery. Document the incident immediately, notify your insurer without delay, track every administrative date meticulously, and seek professional guidance if complex legal or jurisdictional hurdles arise. Protect your claim by acting decisively before time runs out.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
