Maximum Years for Term Life Insurance in Michigan: Policy Lengths and Regulations
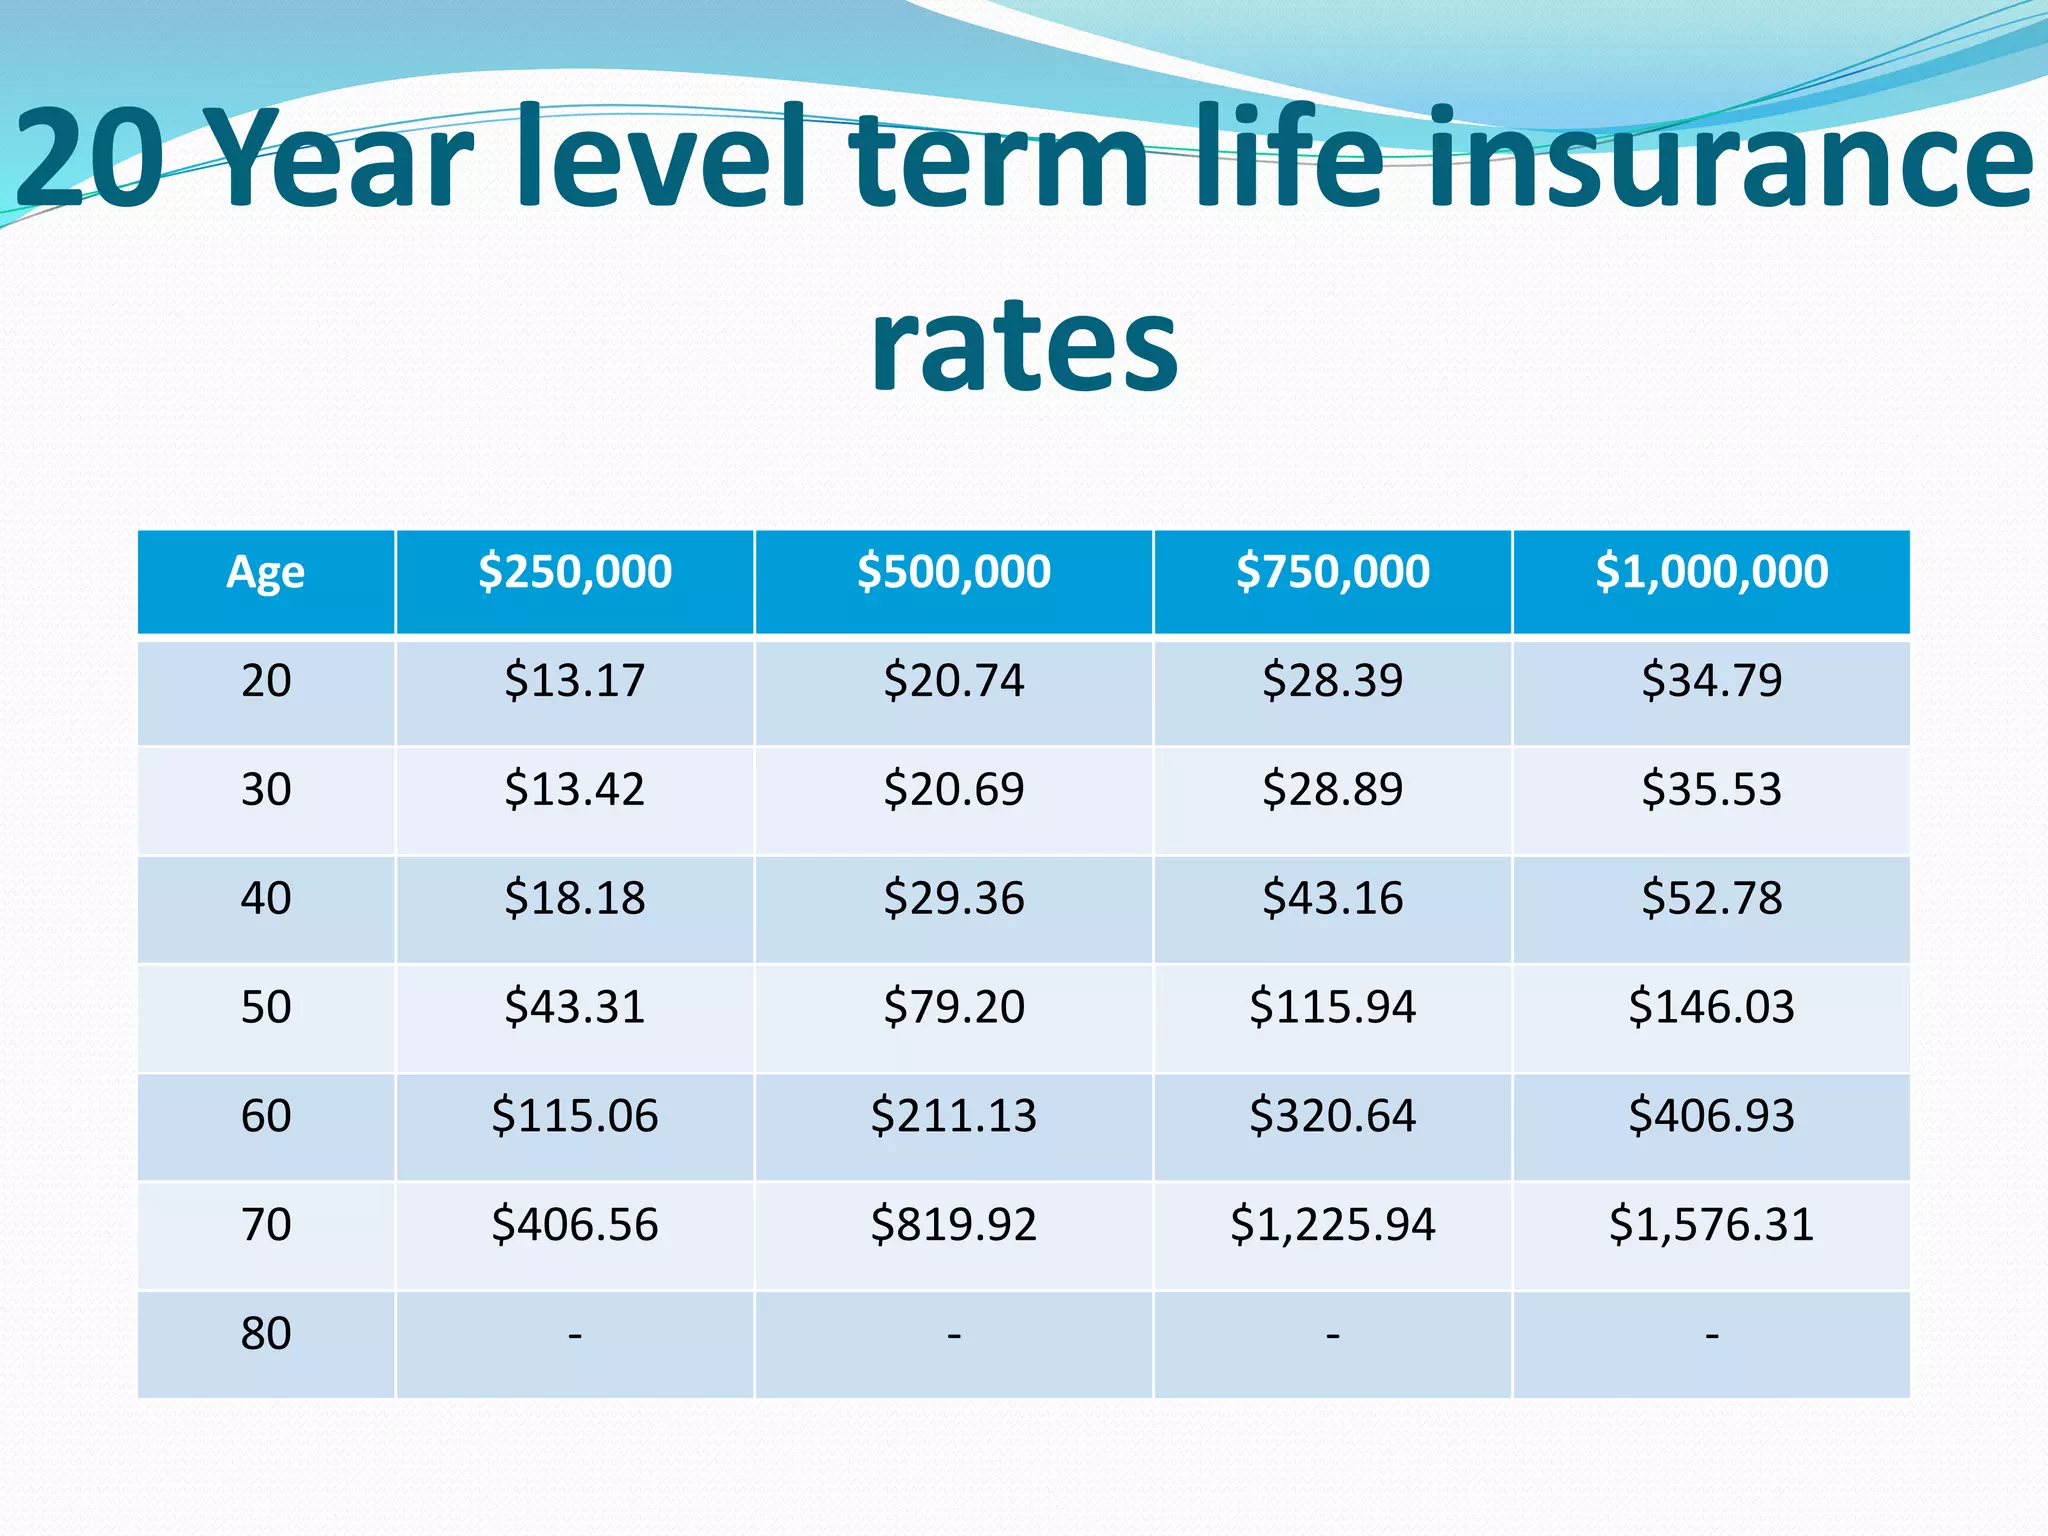
In Michigan, the maximum duration for a term life insurance policy is typically 40 years. While 10, 20, and 30-year terms remain the industry standard, several major carriers now offer 35-year and 40-year level term products to Michigan residents, provided the applicant meets specific age and health requirements at the time of issuance.
Understanding Term Life Durations in the Michigan Market
Term life insurance is designed to provide financial protection for a specific window of time. In Michigan, as in most of the United States, this "term" is the period during which your premiums remain level and your death benefit is guaranteed, provided premiums are paid. As of 2026, the landscape of term life insurance has shifted to accommodate longer financial obligations, such as 30-year mortgages and delayed retirement ages.
When discussing the "maximum years," it is essential to distinguish between the initial level term period and the policy expiration age. While a policy might have a 40-year level period, almost all term products in Michigan also carry an expiration age, often between 85 and 95. This means that even if a 40-year term is available, an older applicant may be barred from selecting it if the term would carry them past the carrier's maximum age limit.
The Michigan Department of Insurance and Financial Services (DIFS) oversees the licensing and conduct of insurance companies within the state. While DIFS does not set a legal "ceiling" on the number of years a term policy can last, it ensures that these products are actuarially sound and that the carriers maintain sufficient reserves to pay out claims decades into the future.
The Evolution of the 40-Year Term
For decades, the 30-year term was considered the "gold standard" for long-term temporary coverage. However, shifting demographics and economic realities in Michigan—including rising housing costs and longer career spans—driven the demand for even longer durations.
Why the 40-Year Term Emerged
The introduction of 35-year and 40-year terms was a direct response to the "sandwich generation" and the extension of the traditional 30-year mortgage. Many Michigan families now find that a 30-year policy may expire before their youngest child has finished graduate school or before their mortgage is fully retired if they refinanced later in life.
Carrier Availability in Michigan
Not every insurance company offers these extended terms. In 2026, major national carriers such as Banner Life (Legal & General America) and Protective Life are among the primary providers offering 40-year term lengths to Michigan residents. These companies utilize sophisticated data modeling to price the risk of a four-decade commitment, which is significantly higher than a standard 10-year or 20-year policy.
Eligibility and Age Restrictions for Maximum Terms
The "maximum years" available to you is largely dictated by your current age. Insurance companies use a "maximum issue age" chart to determine who can qualify for which term length.
The Math of Risk and Age
Generally, the sum of your current age and the term length cannot exceed a certain threshold (usually 80 or 85). For a Michigan resident to qualify for a 40-year term, they typically must be between the ages of 18 and 45. If you are 50 years old, the maximum term available to you might drop to 30 years. If you are 60, you may be limited to a 15 or 20-year term.
Health and Underwriting
Beyond age, your health classification (Preferred Plus, Preferred, Standard, etc.) plays a role. While poor health might not always disqualify you from a longer term, it will dramatically increase the cost. Because a 40-year term carries the insurer's risk deep into the policyholder's later years, underwriting for these products is often more stringent than for a 10-year "quick issue" policy.
Michigan Department of Insurance and Financial Services (DIFS) Regulations
Michigan’s insurance market is governed by the Michigan Insurance Code (Public Act 218 of 1956). The Michigan Department of Insurance and Financial Services (DIFS) acts as the regulatory body that protects consumers and ensures a competitive market.
Standard Nonforfeiture Law
Under Michigan law, term life insurance policies are generally exempt from nonforfeiture requirements (which apply to whole life policies that build cash value). However, if a term policy is designed to last a very long time—such as 40 years—and involves certain premium structures, it must still adhere to state guidelines regarding "suitability." This means an agent cannot sell you a 40-year term if a shorter term or a permanent policy clearly better serves your financial interests.
Policy Filings
Before a company can offer a 40-year term in Grand Rapids, Detroit, or Lansing, the policy form must be filed and approved by DIFS. This process ensures that the language is clear, the "Right to Cancel" (Free Look Period) is included, and the "Grace Period" (typically 30 days in Michigan) is honored.
Comparison of Term Lengths and Maximum Issue Ages
The following table illustrates the typical maximum issue ages for various term lengths available in the Michigan market as of 2026. Note that these are industry averages and can vary by carrier.
| Term Length | Typical Maximum Issue Age (Nonsmoker) | Common Use Case in Michigan |
|---|---|---|
| 10 Years | 75 - 80 | Short-term debt or business loans |
| 15 Years | 70 - 75 | Nearing retirement; short-term mortgage |
| 20 Years | 65 - 70 | Protecting children until adulthood |
| 25 Years | 60 - 65 | Coverage until retirement age |
| 30 Years | 50 - 55 | Standard 30-year mortgage protection |
| 35 Years | 45 - 50 | Extended mortgage or delayed family planning |
| 40 Years | 18 - 45 | Comprehensive protection for young families |
Extending Coverage Beyond the Maximum Term
What happens if you reach the end of your 40-year term and still need coverage? In Michigan, there are several mechanisms built into modern policies that allow for continued protection.
The Conversion Privilege
Most term life policies sold in Michigan include a conversion rider. This is a critical feature that allows you to "convert" your term policy into a permanent life insurance policy (like Whole Life or Universal Life) without undergoing a new medical exam.
The catch is that there is usually a "conversion window." This window might expire at age 65 or 70, or at the end of the term, whichever comes first. If you have a 40-year term policy and develop a chronic illness in year 35, you can exercise this right to keep coverage for the rest of your life, though the premiums will increase to reflect the permanent policy rates.
Annually Renewable Term (ART)
If your 40-year term expires and you do not convert it, most policies enter an "Annually Renewable" phase. You can technically keep the policy, but the premiums will skyrocket every year based on your attained age. This is rarely a viable long-term solution but can provide a few months of "buffer" coverage if needed.
Financial Implications of Long-Term Term Policies
A 40-year term policy is an investment in stability, but it comes with higher costs than its shorter counterparts. In Michigan, the premium for a 40-year term is higher because the probability of the insurance company paying a claim is statistically much greater over 40 years than over 20 years.
Level Premium Guarantee
The primary advantage of these policies is the level premium guarantee. This means that the monthly or annual cost you agree to at age 30 will be the exact same price you pay at age 69. Given inflation and the rising cost of living in Michigan, a locked-in rate from 2026 will likely look very affordable by 2066.
Cost-Benefit Analysis
When deciding if you should opt for the maximum years available, consider the "Total Cost of Insurance."
- A 20-year term might cost $30/month.
- A 40-year term might cost $65/month.
While the 40-year term is more expensive, purchasing a new 20-year policy when you are 50 (after your first 20-year term expires) will likely cost significantly more than $65/month due to your increased age and potential health changes.
Common Mistakes When Selecting Term Lengths in Michigan
Choosing the maximum possible years isn't always the right move. Michigan consumers often fall into a few common traps when navigating long-term coverage.
- Over-Insuring the Duration: If your only major debt is a 15-year mortgage and your children are already in their teens, paying the premium for a 40-year term may be an inefficient use of capital. You are paying for "tail risk" that you might not actually need.
- Ignoring the Conversion Clause: Some "budget" policies in Michigan strip out the conversion rider to lower the price. Always verify that your long-term policy allows for conversion, as your needs may change over four decades.
- Failing to "Ladder" Policies: Instead of one massive 40-year policy, some residents use a strategy called "laddering." They might buy a 20-year policy for $500,000 and a 40-year policy for $250,000. This provides high coverage while the kids are home and lower, cheaper coverage for the long haul.
- Underestimating Inflation: While your death benefit stays level, its purchasing power decreases. A $500,000 policy in 2026 will buy much less in 2066. If you are opting for a 40-year term, consider a slightly higher death benefit than you think you need today.
Frequently Asked Questions
Can I get a 50-year term life insurance policy in Michigan?
As of 2026, 50-year term life insurance policies are not a standard offering in the Michigan market. The current industry ceiling is 40 years. If you require coverage for 50 years or more, you should investigate "Term to Age 90" policies or permanent insurance options like Guaranteed Universal Life (GUL), which can act like a long-duration term policy but last until a specific age rather than a set number of years.
Does Michigan law require a "Free Look" period for long-term policies?
Yes. In Michigan, life insurance policies typically come with a 10-day free look period. This allows you to review the policy after it is delivered. If you decide the 40-year term is not right for you, you can return the policy for a full refund of any premiums paid within this window.
Are premiums for a 40-year term tax-deductible in Michigan?
Generally, no. For individual taxpayers in Michigan, life insurance premiums are considered a personal expense and are not deductible from state or federal income taxes. However, the death benefit paid out to your beneficiaries is typically free from federal and Michigan state income tax.
Can I shorten my term later if I don't need it?
You cannot technically "shorten" a term length (e.g., turn a 40-year policy into a 20-year policy), but you can cancel your policy at any time without penalty. Since term insurance does not build cash value, you simply stop paying premiums and the coverage ceases. Some carriers may allow you to reduce the death benefit amount to lower your premiums while keeping the original 40-year duration.
Is the maximum term different for smokers in Michigan?
The maximum available years (40 years) is theoretically the same for smokers, but many carriers restrict smoker eligibility for the longest terms. A smoker may find that while a 20-year term is available, a carrier might cap their term at 30 years due to the significantly higher mortality risk associated with tobacco use over a four-decade span.
Practical Recommendation
If you are a Michigan resident under age 45 with long-term financial obligations—such as a new mortgage or young children—the 40-year term represents the maximum "peace of mind" duration currently available. Before committing, however, you should perform a "laddering" analysis to see if a combination of 20 and 40-year policies could save you money over time.
Always ensure the carrier is highly rated (A- or better) by A.M. Best, as a 40-year term is a very long-term promise that requires a financially stable institution. If you are over age 45, focus on "Term to Age" products or 30-year terms, as these will likely be the practical maximums available to you.
Disclaimer: The information provided in this article is for educational purposes only and does not constitute financial, legal, or tax advice. Insurance regulations and product availability can change. Consult with a licensed Michigan insurance professional or financial advisor to discuss your specific situation.
Image Gallery
Select an image to open it in a new tab.
Celine Dubois
Contemporary Living and Global Arts Columnist
