When a 19-year-old moves out of the family home, managing their auto insurance often becomes a source of confusion regarding policy residency requirements and liability. Generally, the individual must secure their own policy if they maintain a separate residence, as insurance providers require the primary policy address to reflect where the vehicle is garaged most of the time to accurately assess risk and state-specific legal requirements.
Navigating the transition from being a dependent on a parent’s policy to becoming an independent policyholder is a significant financial step. For a 19-year-old, this change often coincides with a period where insurance premiums are typically higher due to age-related risk profiles. Understanding the nuances of residency, coverage limits, and potential discounts is essential for securing adequate protection while maintaining financial stability.
1. Establish Residency and Garaging Location
The most critical factor in auto insurance is the "garaging address." Insurance companies base their premium calculations on the statistical risk of the specific zip code where the car is parked overnight. If a 19-year-old has moved to a new city or state, they must update their policy to reflect the actual location of the vehicle.
Failing to update this address can lead to "rate evasion," which is considered insurance fraud. If you file a claim for an incident that occurred at a different address than the one on file, the insurer may deny the claim entirely or retroactively adjust the premiums. Always ensure the policy reflects the address where the driver and the vehicle physically reside, regardless of where they are registered to vote or where their parents live.
2. Understand the Cost of Independence
Statistics consistently show that drivers under the age of 25 are statistically more likely to be involved in accidents. Consequently, insurance carriers apply a "youthful driver" surcharge. When a 19-year-old transitions to their own policy, they lose the benefits of being a "secondary driver" on a parent’s multi-car policy, which often benefits from longevity discounts and combined coverage bundles.
It is helpful to obtain quotes from multiple carriers to see how the independence factor shifts your pricing. While individual policies are almost always more expensive than staying under a parent’s roof, comparing prices allows you to find a carrier that offers the best balance of coverage and cost for young, single drivers.
3. Maintain Continuous Coverage
Insurance companies value "tenure" and "continuous coverage." A gap in your insurance history—even for a few weeks while transitioning between a parent's policy and your own—can cause your insurance score to drop. When you eventually apply for your own policy, a lapse in coverage is often flagged by underwriters as a high-risk indicator, leading to higher premiums.
To mitigate this, ensure that the effective date of the new policy is the exact day the previous coverage ends. If you are moving out, work with your parent's agent to determine the precise date you will be removed from their policy and ensure your new policy is bound before that date.
4. Evaluate Coverage Limits and Deductibles
As a young adult, budget constraints are common, but cutting corners on liability limits can lead to catastrophic financial consequences. Liability insurance covers the costs you are responsible for if you cause an accident, including other people's medical bills and property damage.
For a 19-year-old, it is strongly recommended to purchase higher liability limits than the state minimum requirements. State minimums are often insufficient to cover significant medical bills, leaving you personally liable for any amount exceeding your policy limits. Consider balancing your budget by opting for a higher deductible for collision or comprehensive coverage—which lowers your monthly premium—while keeping your liability limits robust.
5. Leverage Student and Safety Discounts
Insurance carriers often provide specific discounts that can substantially reduce the burden of high premiums for 19-year-olds. Research the following common discounts:
- Good Student Discount: Many insurers offer a discount if you maintain a "B" average or higher. You will typically need to provide your most recent transcript.
- Telematics Programs: Some carriers offer apps that track your driving habits, such as hard braking and acceleration. If you are a safe driver, this data can lead to significant personalized discounts.
- Defensive Driving Courses: Completing an accredited safety course can often result in a permanent reduction in your premium for a set period.
- Vehicle Safety Features: If your vehicle is equipped with advanced safety systems like anti-lock brakes, airbags, or lane-departure warnings, mention this to your agent.
6. Consider the Benefits of Renters Insurance
One of the most effective ways to lower the cost of auto insurance is through "bundling." If you are living in an apartment or a rented house, you should carry renters insurance. Most major insurance carriers offer a substantial discount on your auto policy if you carry a renters policy with the same company.
Beyond the insurance savings, renters insurance protects your personal belongings in the event of theft, fire, or water damage—risks that are not covered by your landlord's insurance policy. This is a practical, proactive step that offers double-layered protection for a young adult living independently.
7. Shop as an Individual, Not a Household
When living with parents, you are part of a "household" rating, which involves the collective driving history and credit scores of everyone in the house. Once you move out, you are rated solely on your own profile. This means your credit history (if applicable), your own driving record, and your specific vehicle profile determine your rates.
Because you are no longer part of a family pool, you have the flexibility to switch to companies that specialize in policies for younger, single drivers. Use comparison tools to look at companies that prioritize tech-forward, digital-first claim processing, which often aligns better with the needs of a 19-year-old.
Comparison Table: Factors Impacting Your Premium
| Factor | Impact on Premium | Strategy |
|---|---|---|
| Credit History | Moderate to High | Establish and maintain a positive credit file. |
| Vehicle Age/Model | High | Choose vehicles with high safety ratings. |
| Annual Mileage | Moderate | Provide accurate odometer readings. |
| Deductible Amount | Moderate | Raise the deductible to lower the monthly premium. |
| Bundle (Auto/Renters) | Low (Discount) | Combine policies to save 5%–15%. |
Frequently Asked Questions
Can I remain on my parents' policy if I don't live with them? Generally, no. Insurance companies require the policy to be linked to the primary garaging address. If you move, the insurer requires you to be moved to your own policy to ensure the risk profile matches the physical location of the vehicle.
Does a 19-year-old need their own insurance if they are still a student? Yes, if you have established a separate, permanent residence for school or work, you are legally obligated to insure the vehicle where it is parked. Being a student does not exempt you from the residency requirements defined in the insurance contract.
How much does insurance usually increase for a 19-year-old? There is no fixed dollar amount, as premiums depend on location, car, and history. However, industry data shows that teen and young adult drivers pay significantly higher premiums than those aged 30 and older due to higher crash frequency statistics.
What happens if I don't update my address with my insurer? Providing inaccurate information regarding where a car is garaged can be viewed as material misrepresentation. This can result in the cancellation of your policy or the denial of claims during the investigation process.
Are there specialized insurance companies for young drivers? Most major national carriers offer products designed for younger demographics. Rather than seeking a "specialty" company, focus on carriers that offer telematics programs, as these are the most effective ways for young drivers to demonstrate safety and secure lower rates.
Next Steps for Implementation
If you are moving out, the first step is to contact your parent’s current insurance agent. Request a "transfer of policy" or a quote for a standalone policy based on your new address. By obtaining this quote 30 days before your move-in date, you can ensure that your coverage is seamless and your new policy is effective immediately upon your arrival at your new residence. Take the time to verify your state’s minimum liability requirements, and aim to exceed those minimums to protect your future financial health.

Image Gallery
Select an image to open it in a new tab.
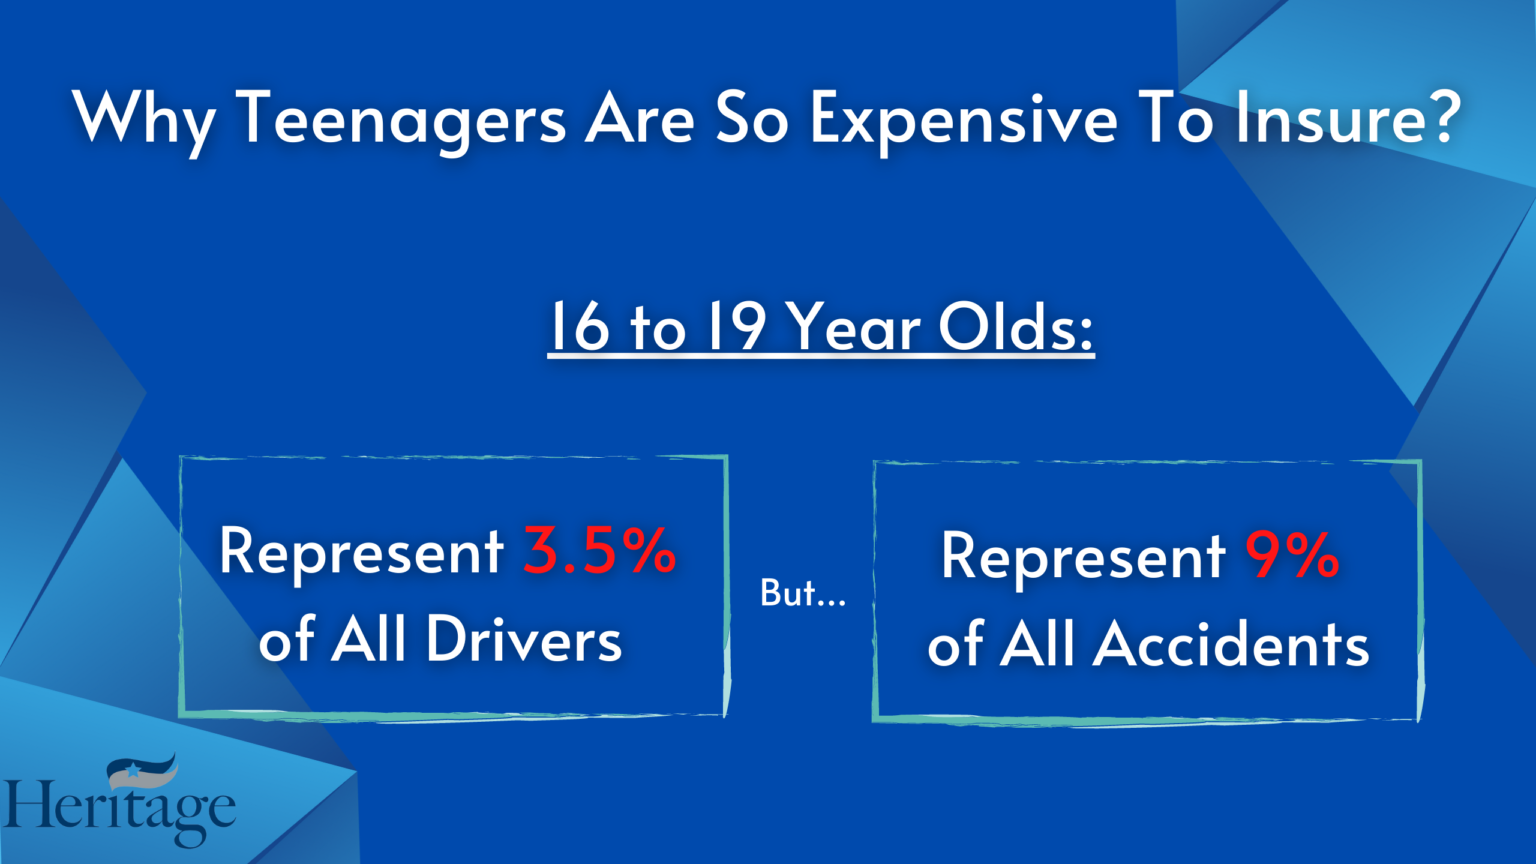

Mateo Castillo
Decentralized Finance and E-Payments Strategist
