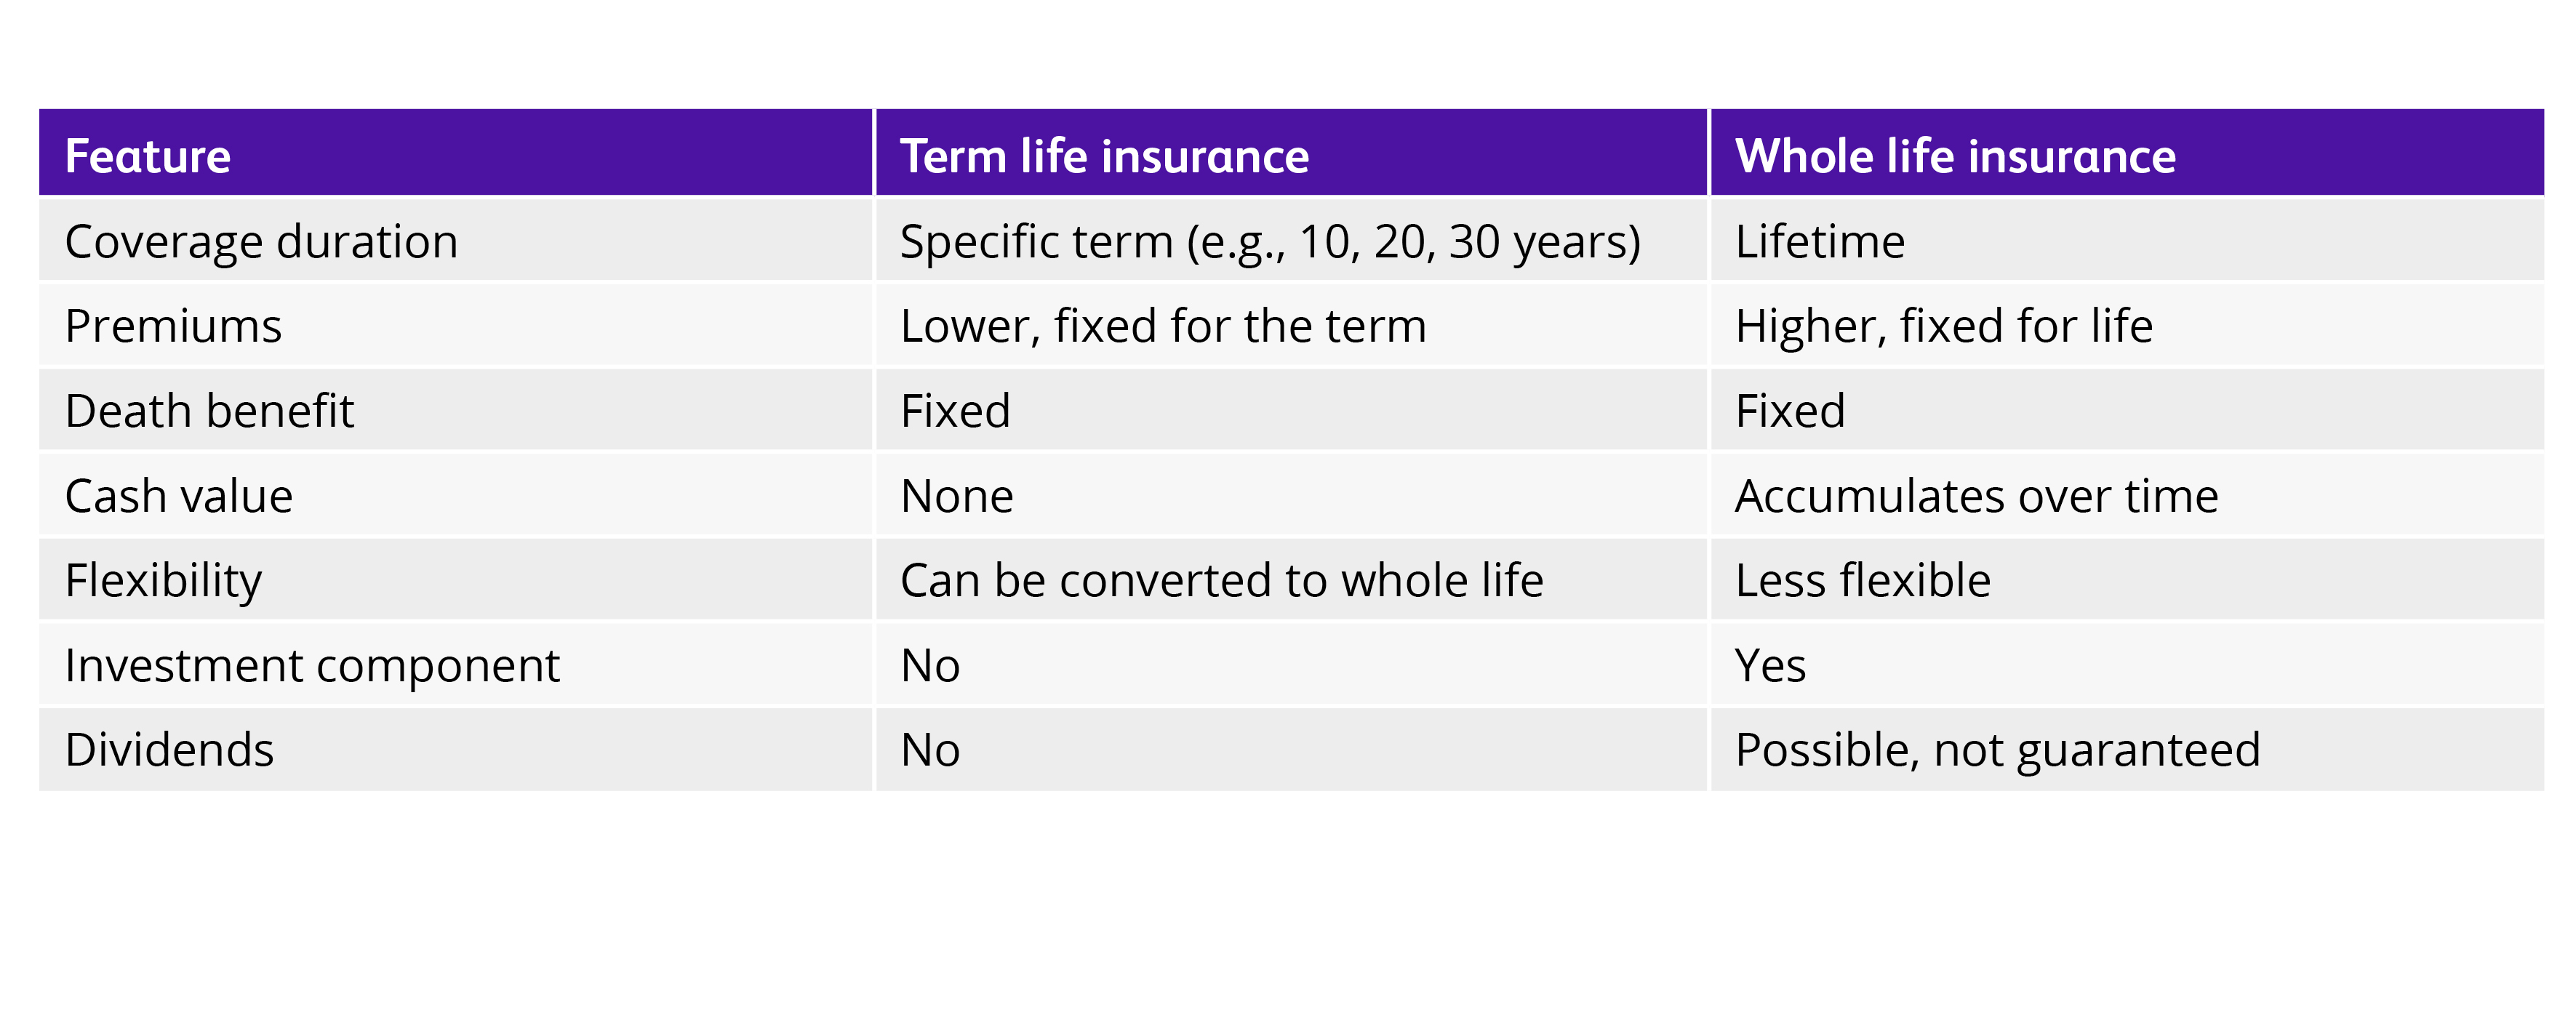
Term life insurance is significantly more affordable than whole life insurance because it provides temporary coverage without a savings component. While term life premiums cover only the statistical risk of death during a set period, whole life premiums are higher to fund permanent protection and a tax-deferred cash value account.
Understanding the financial implications of life insurance requires looking beyond the monthly premium. In 2026, the landscape of personal finance emphasizes efficiency and long-term utility. Whether you are protecting a young family’s future or planning a complex estate, the choice between term and whole life insurance hinges on how much you are willing to pay for "living benefits" versus pure death benefit protection.
The Fundamental Cost Difference: Why Whole Life Costs More
The primary reason whole life insurance costs more than term life insurance is the guaranteed nature of the payout and the inclusion of a cash value component. When you purchase term life insurance, you are buying a contract that pays out only if you die within a specific timeframe—typically 10, 20, or 30 years. Because many policyholders outlive their terms, the insurance company takes on less total risk, allowing them to charge lower premiums.
Whole life insurance, conversely, is a permanent policy. As long as you pay the premiums, the insurer will eventually pay a death benefit. To sustain this guaranteed payout as you age and the risk of death reaches 100%, the insurance company must collect much higher premiums in the early years of the policy. These "excess" premiums are invested by the company to build a cash value reserve.
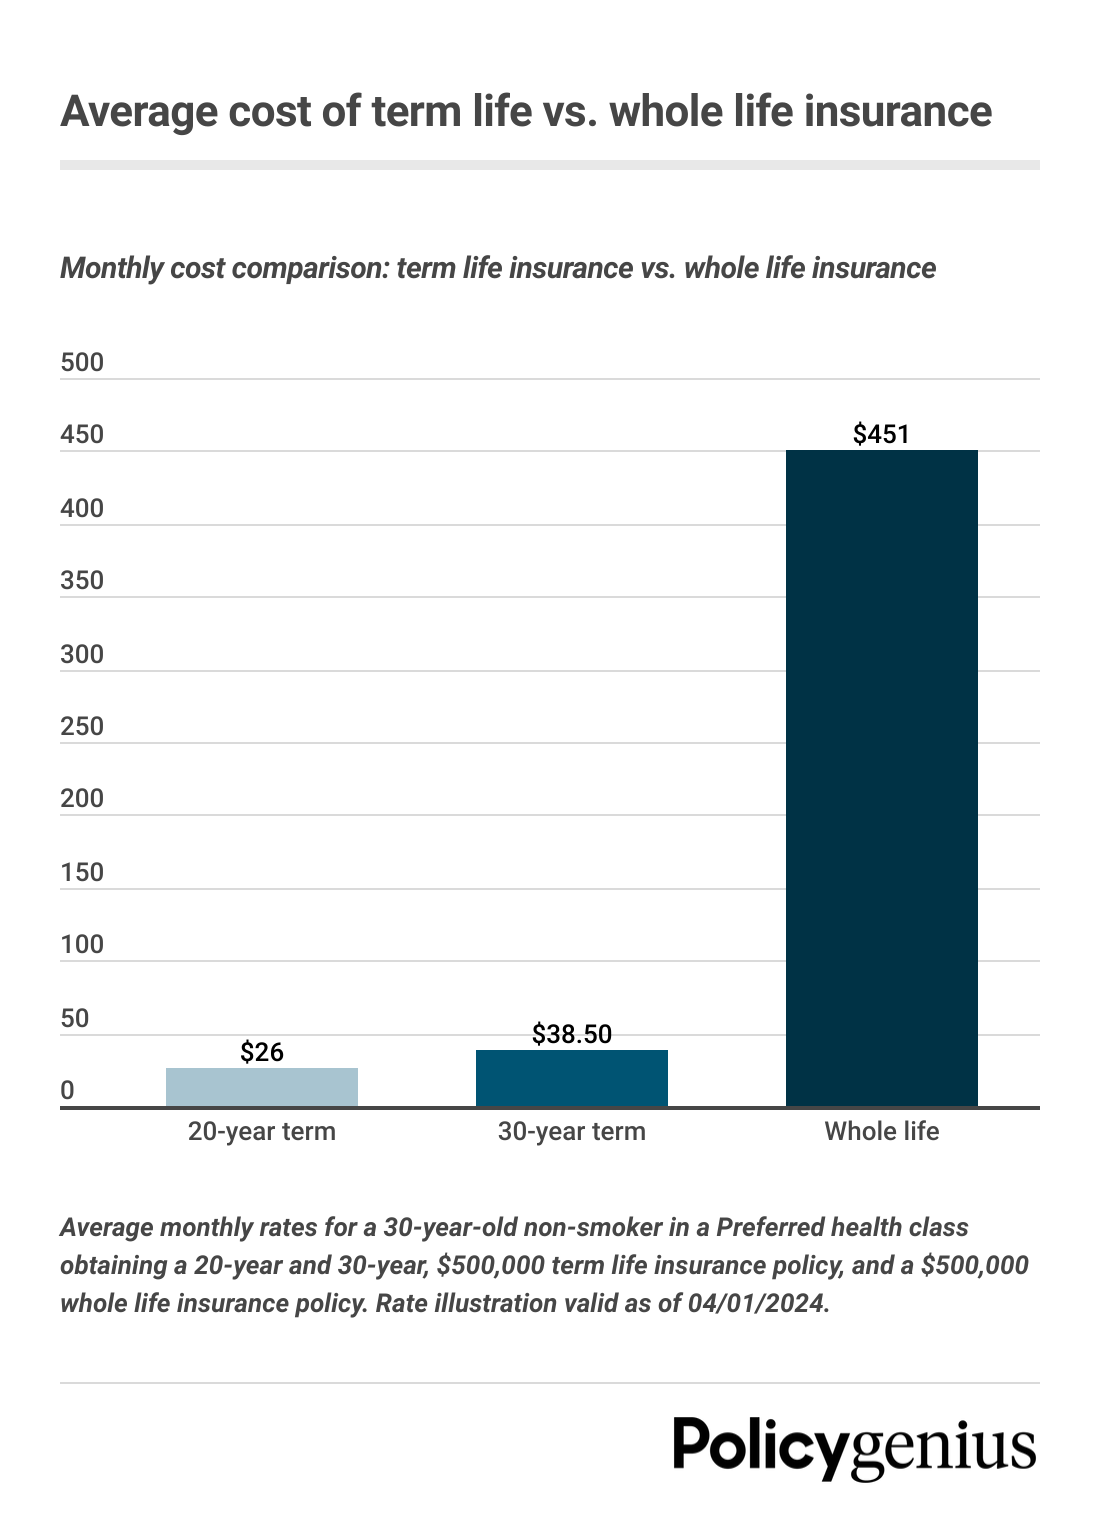
In 2026, a healthy 35-year-old might find a $500,000 term life policy for $30 to $50 per month, whereas a whole life policy for the same amount could cost $400 to $600 per month. This 10x to 15x price multiplier represents the cost of permanence and the underlying investment vehicle.
Mechanics of Term Life Insurance Costs
Term life insurance is often described as "renting" coverage. It is designed for specific periods of high financial vulnerability, such as the years when you have a mortgage or children living at home.
Level Premium vs. Increasing Risk
Most modern term policies feature level premiums, meaning your cost remains the same for the duration of the term. Even though your risk of dying increases every year you age, the insurance company averages the cost over the 20 or 30-year period. If you choose to renew a term policy after the initial period expires, the cost typically skyrockets because it is then based on your attained age and the immediate risk of mortality.
The Role of Underwriting in 2026
By 2026, the underwriting process has become more data-driven. Insurers use "accelerated underwriting" which leverages prescription history, motor vehicle records, and even credit-based insurance scores to determine rates instantly. For those in excellent health, this has stabilized term costs. However, for those with pre-existing conditions, the cost of term life can still vary significantly between providers based on how they weigh specific health risks like hypertension or Type 2 diabetes.
Length of Term and Price Sensitivity
The length of the term directly impacts the premium. A 30-year term is more expensive than a 10-year term because the insurer is committed to a level price for a longer period, during which the likelihood of a claim increases.
- 10-Year Term: Best for short-term debts or those nearing retirement.
- 20-Year Term: The "sweet spot" for many families with young children.
- 30-Year Term: Provides the most stability but at the highest "term" price point.

Mechanics of Whole Life Insurance Costs
Whole life insurance is a form of "owning" coverage. It combines a death benefit with an investment account that grows over time.
The Cash Value Component
A portion of every whole life premium is funneled into a cash value account. This account grows at a guaranteed rate set by the insurer. In many policies, particularly those from mutual insurance companies, you may also receive dividends. While dividends are not guaranteed, they can be used to pay premiums, increase the death benefit, or be taken as cash.
The cost of a whole life policy remains level for life. While the premium seems high at age 30, it remains the same at age 80, when the actual cost of insuring an 80-year-old would be prohibitively expensive. This "front-loading" of costs is what builds the cash value.
Administrative and Commission Costs
It is important to note that whole life policies carry higher administrative fees and agent commissions than term policies. In the first few years of a whole life policy, the cash value grows slowly because a significant portion of the premium goes toward these acquisition costs. This is why whole life insurance is generally considered a poor short-term financial instrument; it often takes 10 to 15 years for the cash value to equal the total premiums paid.
Comparing the Value: A 2026 Perspective
To decide between the two, one must evaluate the opportunity cost. If you buy a term policy for $50 and invest the $450 difference (that would have gone to a whole life policy) into a diversified brokerage account, will you end up with more wealth?
The "Buy Term and Invest the Difference" (BTID) Strategy
For the majority of individuals in 2026, the BTID strategy remains the mathematically superior path for wealth accumulation. The historical returns of the stock market generally outperform the 2% to 4% guaranteed internal rate of return (IRR) found in most whole life products. Furthermore, money in a brokerage account or 401(k) is more accessible than cash value trapped in an insurance policy, which often requires a "policy loan" (on which you must pay interest) to access.
When Whole Life Justifies the Cost
Despite the high cost, whole life insurance serves specific functions that term life cannot:
- Estate Liquidity: For high-net-worth individuals facing estate taxes, whole life provides the cash necessary to pay taxes without liquidating property or businesses.
- Special Needs Planning: For parents of children with lifelong disabilities, permanent insurance ensures funding for a special needs trust regardless of when the parents pass away.
- Final Expenses: Some people prefer a small whole life policy ($10,000 to $25,000) specifically to cover funeral and burial costs, ensuring they aren't a burden to their heirs.
Comparative Cost and Feature Overview
The following table summarizes the primary differences in cost structure and utility between term and whole life insurance as of 2026.
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Relative Monthly Cost | Low (e.g., $30 - $60) | High (e.g., $400 - $600) |
| Premium Structure | Usually level for a set term | Fixed for life |
| Cash Value Growth | None | Guaranteed growth + potential dividends |
| Duration of Coverage | Temporary (10, 20, 30 years) | Permanent (ends at death or age 121) |
| ROI Potential | High (if death occurs during term) | Moderate (stable, low-risk growth) |
| Tax Treatment | Death benefit is tax-free | Death benefit is tax-free; cash value is tax-deferred |
| Complexity | Simple / Easy to understand | Complex / Requires financial planning |
| Best For | Income replacement and debt | Estate planning and lifelong dependents |
Factors That Influence Your Specific Premium
Regardless of which type you choose, several universal factors will dictate your final cost in 2026.
Age and Mortality Risk
Life insurance is priced based on the probability of death. Every year you wait to buy a policy, the base rate increases. For whole life insurance, waiting even five years can result in a significantly higher lifetime premium because the insurer has fewer years to collect the "overfunded" portion of the premium to build the necessary cash value.
Health Classification
Insurers typically assign applicants to health tiers:
- Preferred Plus: Excellent health, no tobacco use, ideal family history.
- Preferred: Great health, minor issues (e.g., well-controlled cholesterol).
- Standard: Average health, perhaps a higher BMI or minor treated conditions.
- Substandard (Rated): Significant health issues; premiums include a "rating" or extra fee.
Lifestyle and Occupation
In 2026, insurers continue to look at high-risk hobbies. If you engage in SCUBA diving, private aviation, or rock climbing, you may face a "flat extra" fee—a specific dollar amount added to your premium per $1,000 of coverage.
Policy Riders
Riders are optional add-ons that customize your coverage but increase the cost. Common riders include:
- Waiver of Premium: If you become totally disabled, the insurer pays your premiums for you.
- Accelerated Death Benefit: Allows you to access a portion of the death benefit if diagnosed with a terminal illness.
- Child Term Rider: Provides small amounts of coverage for children on a parent's policy.
Strategic Selection: Which Should You Choose?
Choosing between term and whole life isn't just about the monthly bill; it is about aligning your insurance with your broader financial plan.
Choose Term Life Insurance if:
- You need the maximum amount of coverage for the lowest possible price.
- Your need for insurance is temporary (e.g., until the kids graduate or the mortgage is paid).
- You are disciplined enough to save and invest your money elsewhere.
- You want a simple, straightforward financial product.
Choose Whole Life Insurance if:
- You have a lifelong dependent, such as a child with special needs.
- You have maximized all other tax-advantaged accounts (401(k), IRA, HSA) and are looking for another tax-deferred vehicle.
- You need to provide liquidity for a large estate or a business buy-sell agreement.
- You want the "forced savings" aspect of a policy that builds cash value.
Frequently Asked Questions
Is whole life insurance a good investment in 2026?
Whole life is generally not considered a high-performing investment when compared to equities or real estate. However, it is a stable, low-volatility asset class. In 2026, it is best viewed as a conservative portion of a diversified portfolio or a specialized tool for estate planning rather than a primary wealth-building vehicle.
Can I convert my term life policy to whole life later?
Yes, many term policies include a conversion rider. This allows you to switch to a permanent policy without undergoing a new medical exam. This is a valuable feature if you develop a health condition during your term that would otherwise make you uninsurable or prohibitively expensive for a new policy.
What happens to the cost of term life if I smoke?
Smoking significantly increases the cost of both term and whole life insurance, often doubling or tripling the premium. In 2026, insurers also distinguish between cigarette smokers, occasional cigar users, and those using nicotine replacement therapies or vaping, each with different pricing impacts.
Can I cancel a whole life policy and get my money back?
If you cancel a whole life policy, you are entitled to the surrender value, which is the accumulated cash value minus any surrender charges or outstanding loans. In the first few years of a policy, the surrender value is often zero or very low due to the initial costs of the policy.
Does term life insurance have any value if I don't die?
Standard term life insurance has no cash value and provides no return if you outlive the policy. However, "Return of Premium" (ROP) riders exist, which refund your premiums at the end of the term if you are still alive. These riders significantly increase the monthly cost, often making them less efficient than simply buying a standard term policy and investing the difference.
Final Recommendation
For the vast majority of consumers in 2026, term life insurance remains the most efficient way to protect a family's financial security. It provides the highest death benefit for the lowest cost, allowing you to use your remaining income to build wealth through more aggressive investment vehicles.
Before making a decision, calculate your "human life value"—the total income you would earn between now and retirement—and match that with a term policy of equal length. If you have unique estate tax concerns or lifelong dependents, consult with a financial advisor to see if a whole life policy should play a supplemental role in your long-term strategy. Always obtain multiple quotes from A-rated (or higher) insurance companies to ensure you are receiving the most competitive rate for your specific health profile.
Image Gallery
Select an image to open it in a new tab.
Simon Caldwell
Enterprise Technology and Systems Editor
