Why the Credit Suisse Hedge Fund Index Matters: A Global Benchmark for Alternative Investments
The Credit Suisse Hedge Fund Index matters because it provides an institutional-grade, asset-weighted performance benchmark that translates the opaque world of alternative investments into transparent, actionable data. By tracking thousands of funds across diverse strategies, it allows investors to measure risk-adjusted returns, identify market trends, and validate the alpha generated by individual fund managers against the broader industry.
For decades, the hedge fund industry was often viewed as a "black box," characterized by high barriers to entry, limited reporting requirements, and a lack of standardized performance metrics. The emergence of the Credit Suisse Hedge Fund Index (formerly the Credit Suisse/Tremont Hedge Fund Index) fundamentally altered this landscape. As of 2026, even following the integration of Credit Suisse’s operations into UBS, the methodology and historical data set associated with this index remain the gold standard for institutional asset allocators, academic researchers, and financial consultants.
The Foundation of Institutional Benchmarking
To understand why the Credit Suisse Hedge Fund Index is significant, one must first understand the problem it solved. Unlike mutual funds, which are heavily regulated under the Investment Company Act of 1940 and required to report daily Net Asset Values (NAV), hedge funds operate with significantly more latitude. This lack of uniformity made it nearly impossible for an investor to determine whether a specific fund’s 10% annual return was a sign of outperformance or merely a result of a rising tide in a specific strategy.
The Credit Suisse Hedge Fund Index introduced a rigorous, rules-based methodology. It was the first major index to utilize an asset-weighted approach rather than an equal-weighted one. In an asset-weighted index, the performance of larger funds has a greater impact on the index value than that of smaller funds. This is crucial because it more accurately reflects the actual "dollar-weighted" experience of the investing public. If a $10 billion fund loses 5% and a $10 million fund gains 50%, an equal-weighted index might suggest the industry is doing well, while an asset-weighted index would correctly show that the vast majority of capital in the space lost value.
Why Asset Weighting Changes the Narrative
The technical depth of the Credit Suisse methodology lies in its selection criteria and rebalancing acts. For a fund to be included, it must meet specific minimum Assets Under Management (AUM) thresholds and provide audited financial statements. This ensures that the index represents "investable" reality rather than a collection of small, ephemeral funds that might not be accessible to institutional capital.
Asset weighting serves several functions:
- Economic Reality: It mirrors the systemic impact of large-scale capital shifts.
- Capacity Awareness: It acknowledges that achieving high returns is significantly harder as AUM grows, providing a more realistic benchmark for "mega-funds."
- Reduced Noise: It prevents the extreme volatility of "boutique" funds from distorting the overall industry performance picture.

Deconstructing the Strategy-Specific Sub-Indices
The Credit Suisse Hedge Fund Index is not a monolithic entity; it is a family of indices. Its importance is magnified by its ability to segment the market into specific strategies. This allows an investor who is specifically interested in Global Macro to compare their manager against a Global Macro benchmark, rather than a generic industry average.
Long/Short Equity
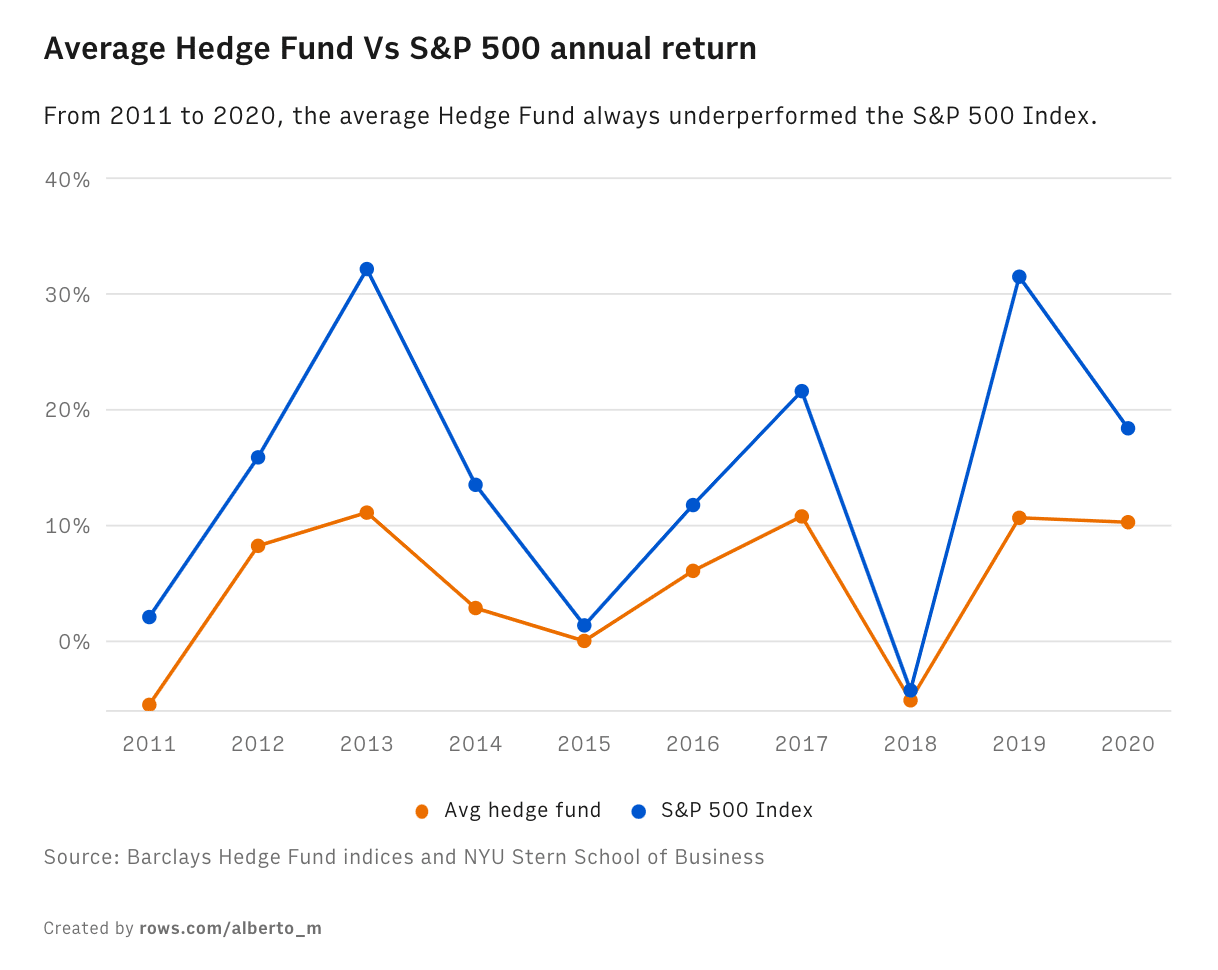
This is the largest component of the index and arguably the most well-known hedge fund strategy. The index tracks managers who maintain both long and short positions in equity markets. By observing this sub-index, investors can gauge the "equity risk premium" that hedge funds are capturing compared to traditional long-only indices like the S&P 500.
Event-Driven
The Event-Driven sub-index focuses on funds that trade based on corporate milestones such as mergers, acquisitions, bankruptcies, or restructurings. This matters because it provides a benchmark for "special situations" investing, which often has a low correlation with broader market movements.
Managed Futures (CTAs)
Managed Futures indices track Commodity Trading Advisors who use systematic, trend-following models. In years of market crisis—such as the volatility seen in the early 2020s—this sub-index often serves as a "crisis alpha" indicator, showing how systematic strategies perform when traditional equities are in a drawdown.
Dedicated Short Bias
While often a small component, the Dedicated Short Bias index is one of the few places where investors can see a consolidated view of how professional "bears" are performing. It serves as an essential tool for tail-risk hedging analysis.
Addressing Survivorship and Selection Bias
A primary reason the Credit Suisse Hedge Fund Index is respected in technical circles is its proactive approach to addressing the inherent biases of hedge fund reporting. Because reporting to databases is voluntary, the industry suffers from:
- Selection Bias: Only funds with good performance tend to report.
- Survivorship Bias: Funds that go out of business are often removed from historical databases, making the past look better than it actually was.
The Credit Suisse methodology accounts for these by maintaining a rigorous inclusion process and keeping historical data for funds that have closed or ceased reporting. This provides a "cleaner" look at the industry's historical performance, which is vital for pension funds and insurance companies that must project future returns with high levels of accuracy.
The Role of the Index in Portfolio Construction
In 2026, asset allocation has become more complex due to the blurring lines between private equity, private credit, and hedge funds. The Credit Suisse Hedge Fund Index serves as the "anchor" for the alternative portion of a 60/40 or "Endowment Model" portfolio.
Institutional investors use the index for:
- Performance Attribution: Determining if a manager’s performance came from "Beta" (market exposure) or "Alpha" (manager skill).
- Risk Management: Using the index's volatility and correlation data to model how a portfolio will behave during a market stress event.
- Fee Justification: If a manager is charging "2 and 20" (2% management fee and 20% performance fee) but is consistently underperforming the Credit Suisse sub-index for their strategy, it provides the investor with the data needed to negotiate fees or reallocate capital.
Comparative Analysis: Credit Suisse vs. Other Benchmarks
| Feature | Credit Suisse Hedge Fund Index | Equal-Weighted Peer Indices | S&P 500 (Traditional) |
|---|---|---|---|
| Weighting Method | Asset-Weighted | Equal-Weighted | Market-Cap Weighted |
| Minimum AUM | High (Institutional Focus) | Low to Medium | N/A (Public Equities) |
| Transparency | High (Rule-based) | Variable | Absolute |
| Frequency | Monthly (with daily estimates) | Monthly | Real-time |
| Primary Use | Institutional Benchmarking | Broad Market Sentiment | Equity Market Proxy |
The Impact of the UBS-Credit Suisse Integration
Following the 2023 acquisition of Credit Suisse by UBS, there were initial questions regarding the future of the index suite. However, by 2026, the index has been maintained as a distinct brand or integrated into a broader "UBS-CS" index family because of its immense historical value. For many long-term institutional contracts, the Credit Suisse Hedge Fund Index is named as the primary benchmark; changing it would require significant legal and administrative effort. Thus, it continues to matter as a "legacy of record" that bridges the gap between the early days of hedge funds and the modern era of integrated global banking.
Common Pitfalls When Using the Index
While the index is a powerful tool, sophisticated users must be aware of its limitations. The index is "investable" in theory, but an investor cannot "buy" the index as easily as they can buy an S&P 500 ETF. While there are "index-tracking" funds, they often face challenges related to liquidity and the fact that some underlying hedge funds may be closed to new capital.
Furthermore, the "backfill bias" is a constant technical concern. When a fund is added to an index, its past performance is sometimes added retrospectively. The Credit Suisse methodology minimizes this, but it is a factor that analysts must account for when performing deep-dive quantitative research.
Strategic Importance for 2026 and Beyond
As we move through 2026, the macro environment is characterized by shifting interest rate regimes and geopolitical volatility. In such an environment, the "Global Macro" and "Multi-Strategy" components of the index become even more relevant. They provide a high-level view of how the world's most sophisticated capital is positioning itself for a "higher-for-longer" or "volatile-normal" interest rate environment.
The index also matters for the "democratization" of alternatives. As retail-accessible "liquid alt" products (UCITS or 40-act funds) proliferate, they often use the Credit Suisse Hedge Fund Index as their "North Star" to prove that they are delivering true hedge-fund-like returns to the average investor.
FAQ
How often is the Credit Suisse Hedge Fund Index updated?
The index provides monthly performance data, typically released mid-month for the preceding month. However, there are also "Liquid Alternative" versions of the index that provide daily estimates based on a representative proxy of liquid securities. This dual-track reporting allows for both long-term accuracy and short-term market monitoring.
Is the index still active after the Credit Suisse and UBS merger?
Yes. As of 2026, the index methodology and data dissemination have been preserved. Financial indices are valuable intellectual property and serve as critical infrastructure for the global financial markets. UBS has maintained the index suite to support the massive ecosystem of institutional investors who rely on this data for reporting and compliance.
How does the index handle fund closures?
When a fund in the index closes, its historical performance remains part of the index up until the point of liquidation. This is a critical feature that prevents "survivorship bias," where an index might otherwise only show the "winners" who are still in business, thereby inflating the perceived returns of the industry.
Can individual investors invest directly in the index?
While you cannot "buy" the index like a stock, there are various financial products, including UCITS funds and index-tracking vehicles, that attempt to replicate the performance of the Credit Suisse Hedge Fund Index or its sub-strategies. These allow smaller investors to gain exposure to the aggregate performance of the hedge fund industry.
What is the minimum AUM for a fund to be included?
Historically, the index has required funds to have at least $50 million in Assets Under Management (AUM) and a minimum one-year track record with audited financial statements. These requirements ensure that the index represents established, professional operations rather than speculative start-ups.
Final Recommendation
For institutional investors and financial analysts, the Credit Suisse Hedge Fund Index should be used as a primary benchmark for assessing the health and performance of the alternative investment sector. However, it should not be used in isolation. To get a complete picture, one should compare the asset-weighted returns of the CS index against equal-weighted peers to understand the "dispersion" of returns—the gap between what the biggest players are earning and what the broader market is experiencing. In 2026, as market correlations remain unpredictable, the index's ability to provide a clean, strategy-specific view of risk and return is more essential than ever.
Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
