Securing the right auto insurance in Southern California requires balancing mandatory state minimum liability limits with comprehensive coverage options designed to handle high-density traffic, unique urban commutes, and regional risk factors like uninsured motorists and wildfire exposure.
Southern California—spanning sprawling metropolitan areas like Los Angeles, Orange County, San Diego, and the Inland Empire—presents a distinct environment for drivers and insurance providers alike. Operating a motor vehicle in this region requires a clear understanding of California’s legal mandates, the specific risk variables that drive up or lower insurance premiums, and how to select the right policy balance to protect your financial well-being.
Whether you are relocating to the region, purchasing a new vehicle, or shopping around to lower your monthly premium, navigating the Southern California auto insurance market involves evaluating statutory requirements, assessing optional coverages, and adopting smart strategies to manage costs in one of the country's most heavily trafficked regions.
Understanding California Auto Insurance Requirements
Before evaluating regional nuances, every driver in Southern California must comply with the California Insurance Code enforced by the California Department of Insurance (CDI) and the Department of Motor Vehicles (DMV). California operates under a traditional fault system, meaning the driver who causes an accident is financially responsible for the resulting damages, injuries, and property losses.
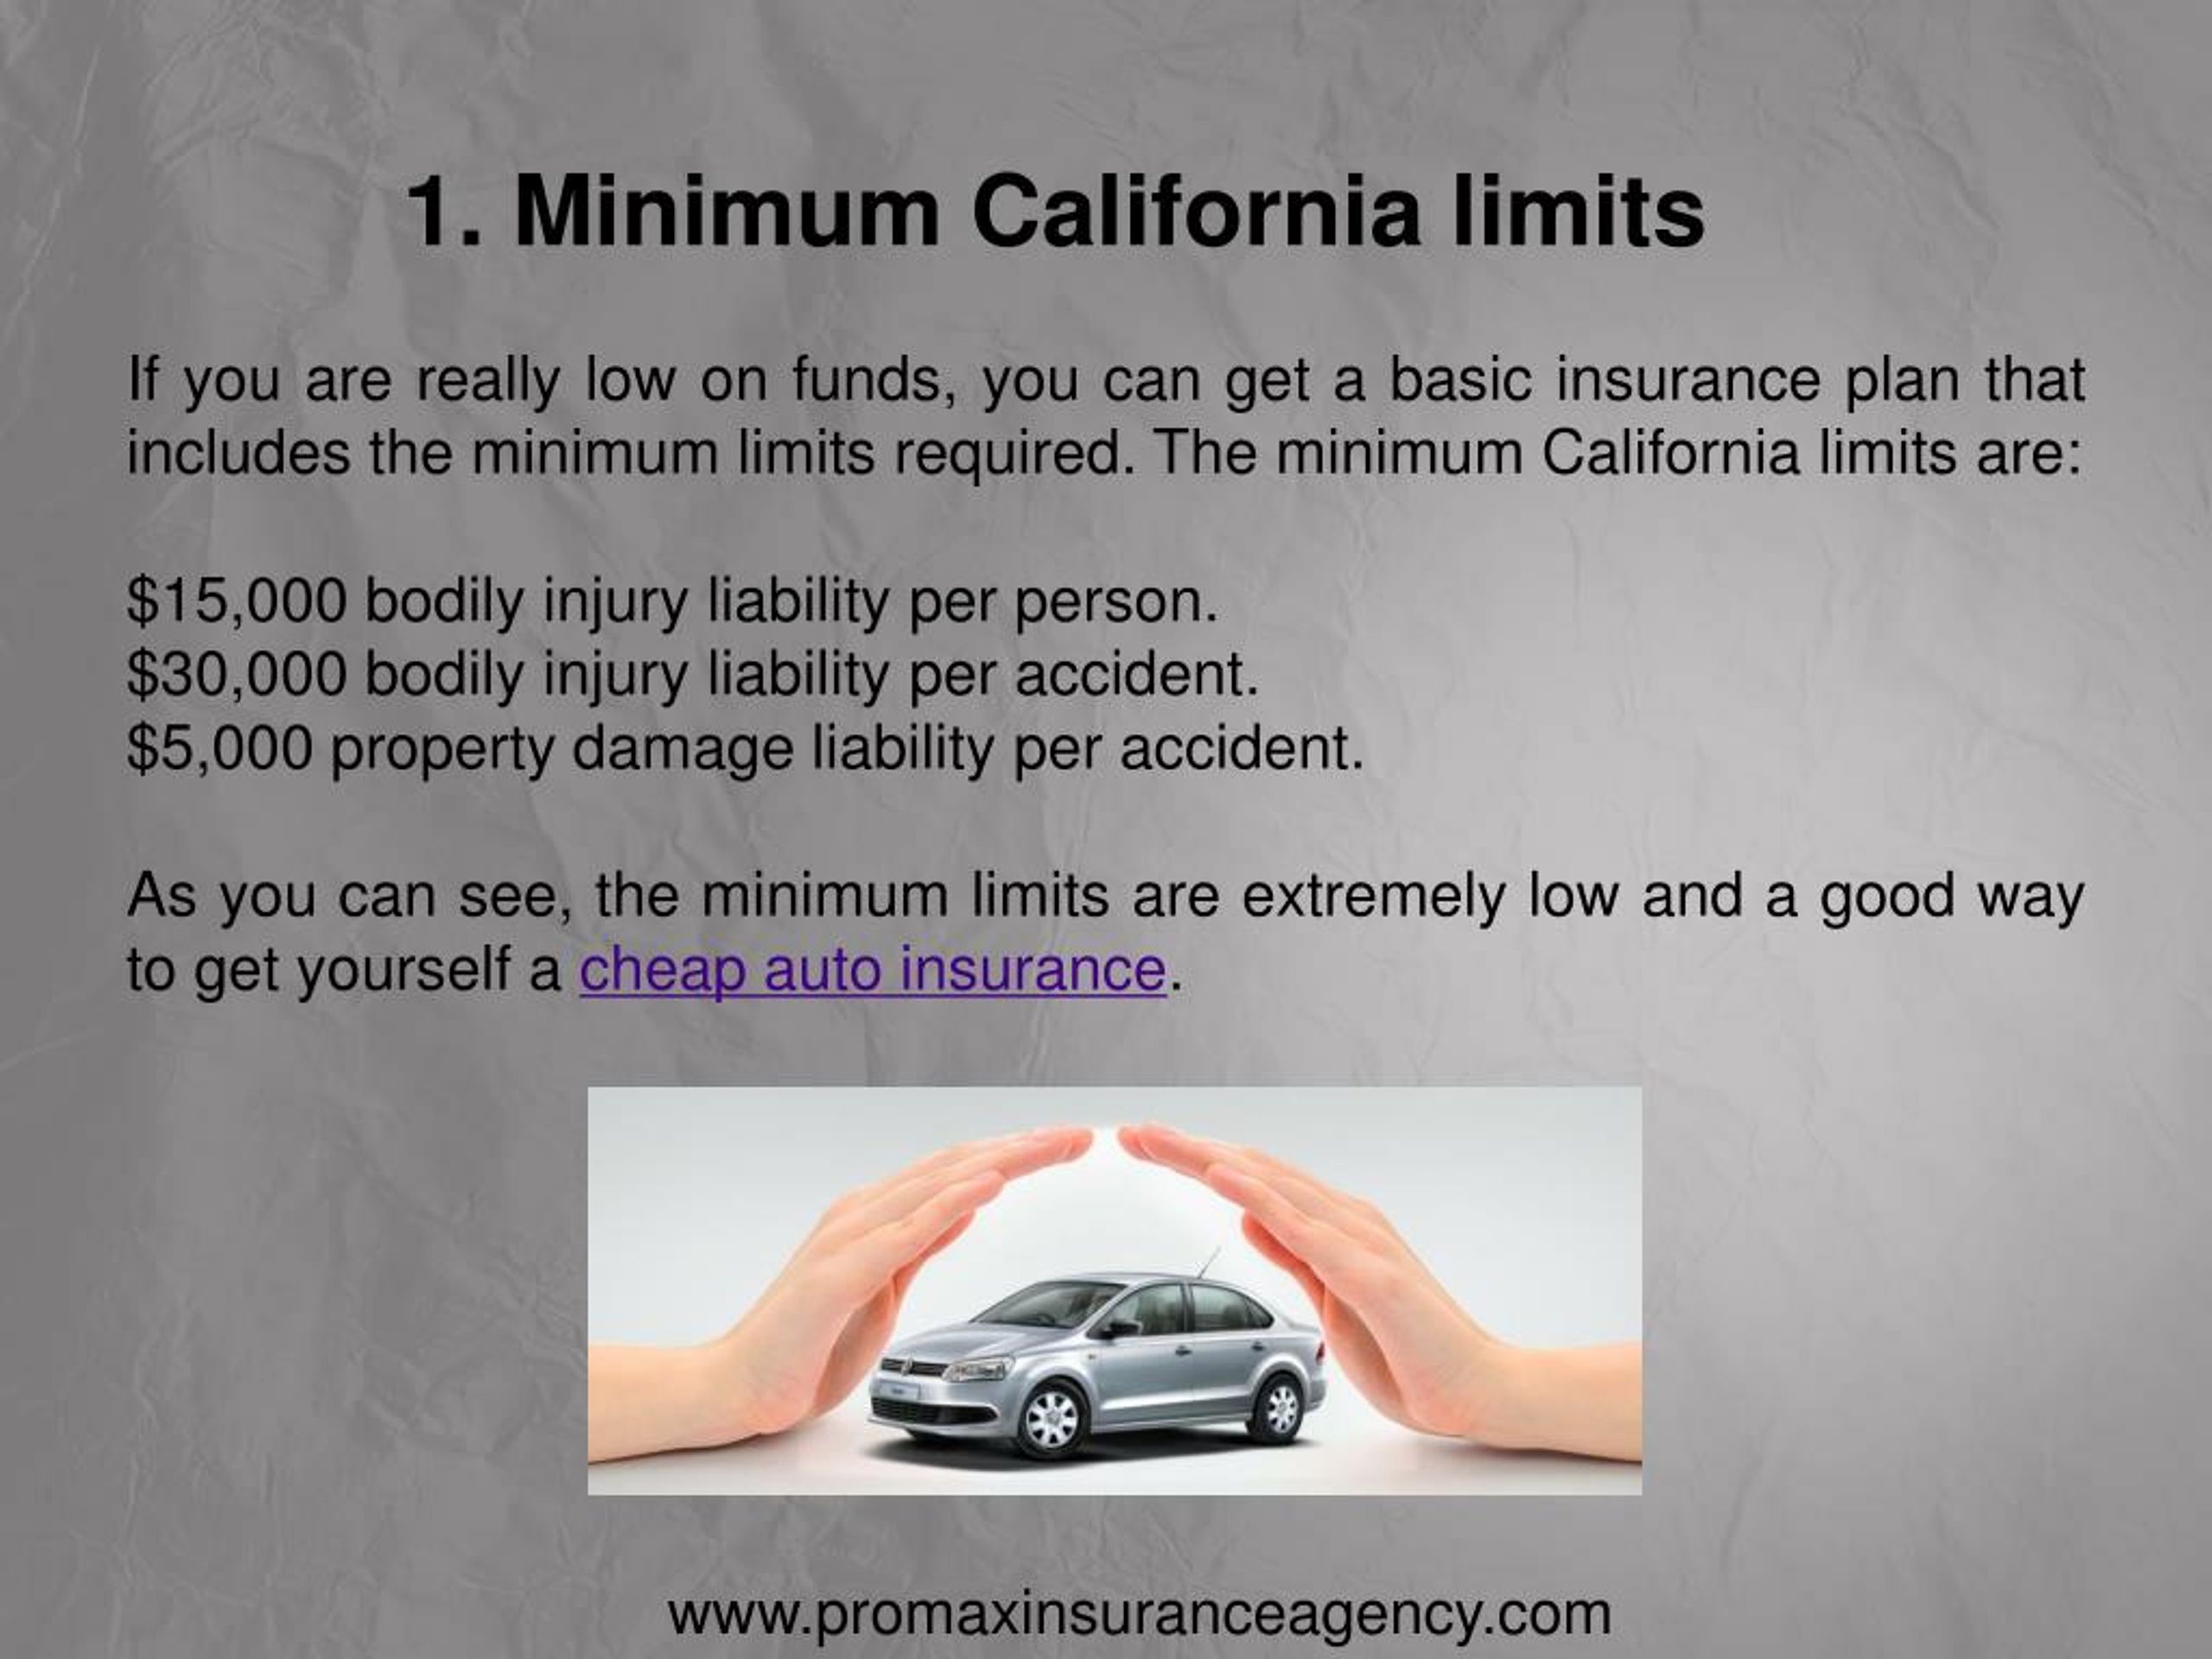
To legally drive on any public roadway in Southern California, vehicle owners must carry active liability insurance that meets or exceeds the state-mandated minimum limits. As of recent updates, the mandatory minimum liability coverage limits in California are:
- Bodily Injury Liability: $15,000 per person and $30,000 per accident.
- Property Damage Liability: $5,000 per accident.
These figures represent the absolute legal minimums required to register a vehicle and maintain driving privileges. However, automotive and financial experts universally recommend purchasing higher liability limits. In a region where luxury vehicles are common and medical costs are high, a $5,000 property damage limit or a $30,000 total bodily injury limit can be exhausted within seconds during a multi-car collision on the I-405 or I-5 freeways, leaving the at-fault driver personally liable for remaining expenses.
Alternatives to Standard Liability Policies
For drivers who struggle to secure coverage through the standard voluntary market due to a poor driving record, accidents, or lack of insurance history, the state provides an alternative. The California Automobile Assigned Risk Plan (CAARP) helps high-risk drivers obtain basic liability coverage when private insurers turn them down. Additionally, the California Low-Cost Automobile Insurance Program (CLCA) offers qualifying low-income drivers state-subsidized liability coverage, provided they meet specific household income limits and own a vehicle valued below a specified threshold.
Key Risk Factors Affecting SoCal Auto Insurance Rates
Southern California consistently ranks among the more expensive regions in the United States for auto insurance. Insurance companies calculate premiums using complex actuarial algorithms that weigh individual driver characteristics against regional risk profiles. Understanding why SoCal rates often trend higher can help you identify areas where you can manage your exposure and negotiate better pricing.
Traffic Density and Accident Frequency
The massive network of freeways, surface streets, and congested corridors stretching from Santa Barbara down to the Mexican border generates exceptionally high traffic density. High vehicle concentration naturally correlates with a higher statistical probability of traffic collisions, fender-benders, and multi-vehicle pileups. Insurers factor this macro-level accident frequency directly into base rates for ZIP codes across Los Angeles, Orange, and San Diego counties.
Uninsured and Underinsured Motorists
Despite strict state laws requiring insurance, California has a significant population of uninsured motorists. When an uninsured driver causes an accident, the financial burden frequently shifts to the victim's insurance company unless that policy includes Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage. Because the prevalence of uninsured drivers in certain Southern California neighborhoods is elevated, insurers price this risk into regional policy premiums.
Vehicle Repair Costs and Labor Rates
Modern vehicles feature advanced driver assistance systems (ADAS), complex computer sensors embedded in bumpers and windshields, and specialized lightweight alloys. When a vehicle is involved in a collision in Southern California, repairing these components requires specialized diagnostic equipment and certified technician labor. High local labor rates and parts shipping costs across metropolitan SoCal drive up average claim severity, which in turn influences insurance premiums.
Environmental and Climate Risks
Southern California is prone to specific natural catastrophes, most notably seasonal wildfires. Insurance policies include comprehensive coverage (often called "other than collision") that protects vehicles against damage caused by fire, falling tree branches, vandalism, or floods. During severe wildfire seasons, vehicles parked outdoors or traveling through affected canyons face heightened exposure, prompting insurers to adjust comprehensive rates accordingly.
Comparing Essential Coverage Types
When building an auto insurance policy in Southern California, relying solely on state minimums leaves significant financial exposure. A robust policy typically combines several types of coverage to ensure complete protection against unpredictable road events.
| Coverage Type | What It Protects | Recommended For |
|---|---|---|
| Liability Coverage | Bodily injury and property damage you cause to others. | All drivers (mandatory state minimums required; higher limits advised). |
| Collision Coverage | Damage to your own vehicle resulting from a crash with another car or object. | Newer vehicles, financed cars, or drivers who cannot afford to replace their car out-of-pocket. |
| Comprehensive Coverage | Non-collision damage, including theft, vandalism, fire, glass breakage, and weather events. | Vehicles parked on the street, parked in wildfire-prone zones, or carrying loan balances. |
| Uninsured Motorist (UM/UIM) | Medical bills and vehicle repairs if you are hit by a driver with no insurance or insufficient limits. | Highly recommended for all SoCal drivers given regional uninsured motorist statistics. |
| Medical Payments (MedPay) | Immediate medical and funeral expenses for you and your passengers regardless of fault. | Supplementing health insurance deductibles and copays after an accident. |
Practical Strategies to Lower Your SoCal Auto Insurance Premium
Because insurance rates in Southern California can be steep, finding ways to optimize your policy without sacrificing necessary protection is vital. Insurance companies offer numerous discounts and structural adjustments that can yield substantial savings over the course of a year.
Bundle Your Policies
One of the most effective ways to secure a discount is through policy bundling. Many major insurance carriers offer multi-policy discounts if you purchase your auto insurance from the same company that insures your home, condo, or renters policy. Bundling simplifies your financial management and typically triggers percentage-based discounts on both policies.
Maintain a Clean Driving Record
Insurers reward safe driving. Avoiding moving violations, speeding tickets, and preventable at-fault accidents keeps your motor vehicle record (MVR) clean. In California, Proposition 103 mandates that insurance companies base rates primarily on driving safety record, annual mileage, and years of driving experience, rather than arbitrary non-driving factors. Maintaining a spotless record over a three-to-five-year period qualifies you for "good driver" discounts, which can reduce your base premium by 20% or more under state regulations.
Adjust Deductibles Wisely
Your deductible is the out-of-pocket amount you pay before insurance kicks in for a comprehensive or collision claim. Opting for a higher deductible—such as raising it from $500 to $1,000—will immediately lower your monthly premium. However, you should only select a higher deductible if you have sufficient emergency savings set aside to cover that amount in the event of an unexpected claim.
Utilize Telematics and Usage-Based Insurance
Many insurance providers operating in Southern California offer telematics programs—either via a plug-in device or a smartphone app—that monitor your actual driving habits. If you are a low-mileage driver who avoids late-night driving, practices smooth braking, and observes speed limits, enrolling in a usage-based insurance program can yield significant discounts based on your verified performance behind the wheel.
Take Advantage of Group and Association Discounts
Check with your employer, professional associations, alumni networks, or membership organizations (such as wholesale clubs or auto clubs). Many insurers maintain partnerships with large organizations, offering exclusive discounted group rates to their members.
Frequently Asked Questions About SoCal Auto Insurance
What are the minimum auto insurance requirements in Southern California?
California law requires all drivers to carry liability insurance with minimum limits of $15,000 for injury to one person, $30,000 for injury to multiple people per accident, and $5,000 for property damage. However, experts strongly recommend purchasing higher limits to protect against costly lawsuits and high-value vehicle damages common in the region.
Why is auto insurance so expensive in Southern California?
Insurance rates in Southern California are driven upward by dense traffic congestion, a high volume of daily commuters, elevated rates of uninsured motorists, high local vehicle repair and labor costs, and environmental risk factors like seasonal wildfires that increase comprehensive claims exposure.
Does California allow non-owner car insurance policies?
Yes. If you do not own a vehicle but frequently rent cars or drive vehicles belonging to others, you can purchase a non-owner auto insurance policy. This provides liability coverage when you drive borrowed or rented vehicles and helps maintain continuous insurance history, which prevents future rate spikes.
How does Proposition 103 affect auto insurance pricing in California?
Passed by voters, Proposition 103 mandates that auto insurance rates in California cannot be excessive, inadequate, or unfairly discriminatory. It requires insurance companies to prioritize a driver's safety record, annual mileage, and driving experience above other rating factors when determining premiums.
Should I purchase comprehensive and collision coverage for an older car?
If your car is older, paid off, and has a low market value, paying for comprehensive and collision coverage might not make financial sense. A good rule of thumb is to compare the cost of annual comprehensive and collision premiums against 10% of the vehicle’s current cash value. If the annual premium exceeds that threshold, dropping those coverages and saving the difference may be more practical.
Next Actions and Shopping Tips
When shopping for auto insurance in Southern California, take a methodical approach to ensure you get optimal value. Begin by gathering your current policy declarations page, driver's license numbers, and estimated annual mileage. Obtain quotes from at least three different reputable insurance carriers—ranging from nationwide brands to regional specialists—ensuring that you compare identical coverage limits and deductibles across all quotes. Review customer satisfaction ratings regarding claims handling to ensure your provider will be reliable when you need them most.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
