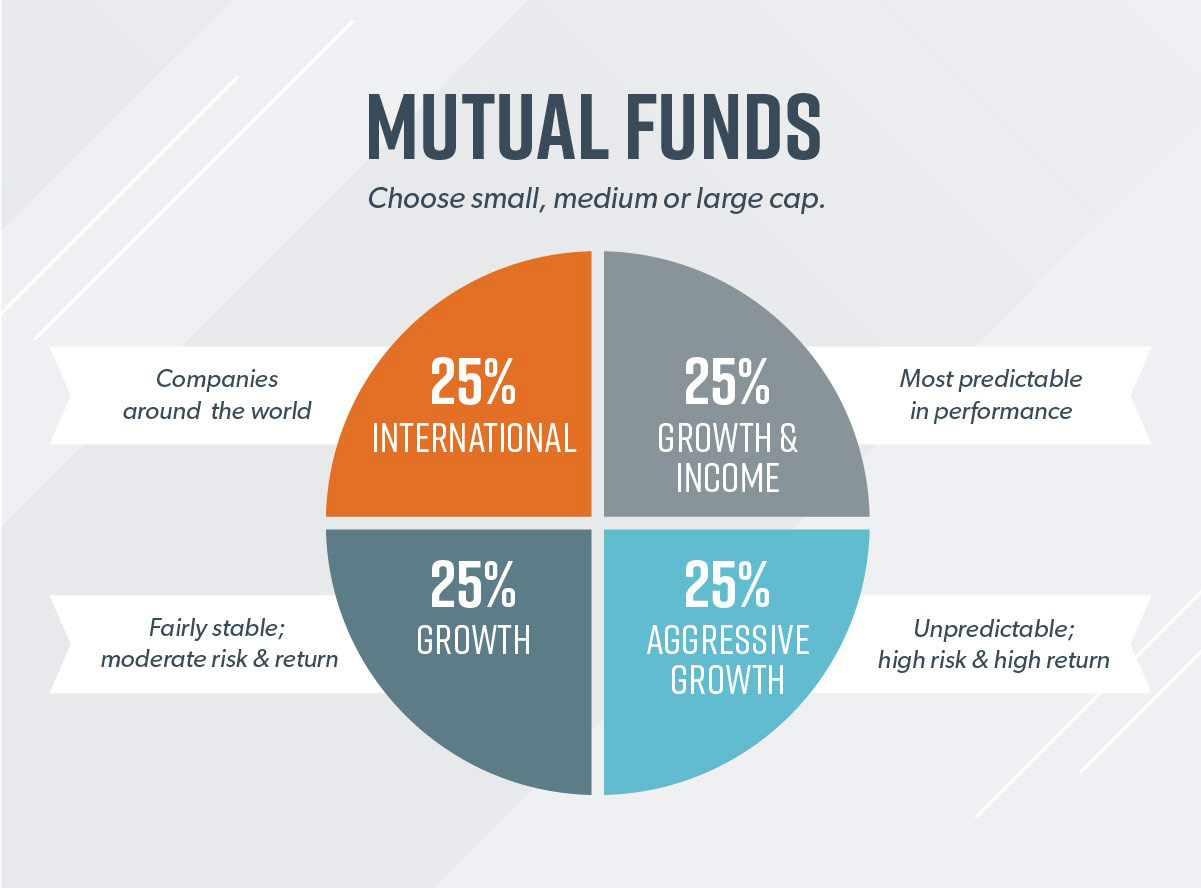
Growth income funds offer a strategic middle ground by combining the capital appreciation potential of growth stocks with the steady cash flow of dividend-paying companies. To optimize your portfolio in 2026, focus on low-cost ETFs and mutual funds that prioritize dividend sustainability, high-quality balance sheets, and a proven history of increasing payouts over multiple market cycles.
The Philosophy of Growth and Income Investing
The primary objective of a growth income strategy—often referred to as a "total return" approach—is to capture the upside of the equity markets while mitigating volatility through regular distributions. In the economic landscape of 2026, where market cycles have become more condensed and interest rate paths remain a primary focus for investors, this dual-purpose strategy serves as a critical stabilizer.
Unlike pure "income" funds, which may chase high yields at the expense of capital preservation (yield traps), or pure "growth" funds, which can be highly sensitive to interest rate fluctuations, growth income funds target companies that are profitable enough to reinvest in their own expansion while simultaneously rewarding shareholders. This typically involves investing in "Dividend Achievers" or "Dividend Aristocrats"—companies that have raised their dividends for at least 10 or 25 consecutive years, respectively.
By reinvesting these dividends, investors benefit from the power of compounding. In 2026, with the digital transformation of the economy continuing to mature, many traditional growth sectors like technology and healthcare have evolved into reliable income producers, making the selection of these funds more nuanced than in previous decades.
Core Selection Criteria for Growth Income Funds
When evaluating the best growth income funds for your portfolio, four technical metrics should guide your decision-making process. These metrics help distinguish between funds that are merely surviving and those that are positioned to thrive in 2026.
1. Dividend Growth Rate vs. Current Yield
A common mistake is prioritizing the current "trailing twelve months" (TTM) yield over the growth rate of that yield. A fund with a 2% yield that grows its payout by 10% annually will eventually outperform a stagnant 4% yield in terms of both income and capital appreciation. In your 2026 analysis, look for funds where the 5-year dividend growth rate exceeds the headline inflation rate by at least 3-5%.
2. The Payout Ratio
For the underlying holdings in a growth income fund, the payout ratio (the percentage of earnings paid out as dividends) is a vital health indicator. A payout ratio between 30% and 60% is generally considered the "sweet spot." It indicates that the company is returning cash to shareholders but retaining enough capital to fund R&D, acquisitions, and debt reduction. Funds holding companies with payout ratios exceeding 80% may face dividend cuts if earnings stumble.
3. Expense Ratios and Operational Efficiency
In a world of low-cost indexing, there is rarely a reason to pay high management fees for a growth income strategy. For passively managed ETFs, an expense ratio below 0.15% is the standard. For actively managed funds, which may aim to navigate specific 2026 market volatilities, anything above 0.60% should be scrutinized heavily to ensure the "alpha" (excess return) justifies the cost.
4. Quality Factors (ROE and Debt-to-Equity)
Growth income funds should emphasize "quality" factors. High Return on Equity (ROE) and low debt-to-equity ratios suggest that the companies within the fund are efficient and not over-leveraged. In 2026, as credit conditions remain tighter than the "easy money" era of the early 2020s, a company’s ability to self-fund its growth is a major competitive advantage.

Top Recommended Growth Income Funds for 2026
The following funds represent the gold standard in the growth income category, offering a blend of systematic selection and sector diversification.
| Fund Name | Ticker | Expense Ratio | Primary Strategy | 2026 Outlook |
|---|---|---|---|---|
| Vanguard Dividend Appreciation ETF | VIG | 0.06% | Focuses on companies with 10+ years of dividend growth. | Low volatility; heavy tilt toward high-quality tech and healthcare. |
| Schwab US Dividend Equity ETF | SCHD | 0.06% | Filters for fundamental strength and sustainable yield. | Excellent "value-growth" hybrid with a focus on cash flow. |
| iShares Core Dividend Growth ETF | DGRO | 0.08% | Broad exposure to dividend growers across all sectors. | Highly diversified; prevents over-concentration in any single sector. |
| Vanguard High Dividend Yield ETF | VYM | 0.06% | Targets higher-than-average yields without sacrificing quality. | Best for those needing immediate cash flow with moderate growth. |
| JPMorgan Equity Premium Income ETF | JEPI | 0.35% | Active management using ELNs and covered calls. | High income (8-10%) but limited capital upside compared to VIG/SCHD. |
Vanguard Dividend Appreciation ETF (VIG)
VIG remains a cornerstone for growth-oriented income seekers. It does not necessarily seek the highest yields; instead, it tracks the S&P US Dividend Growers Index. This index excludes the top 25% highest-yielding eligible companies to avoid yield traps. In 2026, VIG is particularly valuable for its exposure to "mature tech" companies that have transitioned from pure growth to dividend-growth engines.
Schwab US Dividend Equity ETF (SCHD)
SCHD is widely regarded for its rigorous screening process. It evaluates companies based on cash flow to total debt, return on equity, dividend yield, and 5-year dividend growth rate. This multi-factor approach ensures that the fund remains resilient during market downturns. For investors in 2026, SCHD provides a disciplined "value" tilt that complements more aggressive growth holdings.
iShares Core Dividend Growth ETF (DGRO)
DGRO offers a slightly broader canvas than VIG. It requires only five years of dividend growth and includes companies that pay out a maximum of 75% of their earnings. This allows the fund to capture younger, faster-growing companies that are just beginning their dividend-paying lifecycle. It is an ideal "bridge" fund for investors who want more growth than a traditional utility-heavy income fund provides.
Portfolio Allocation Strategies
Integrating growth income funds into your 2026 portfolio requires a clear understanding of your time horizon and tax status.
The Core-Satellite Approach
Many sophisticated investors use a "Core-Satellite" model. In this setup, a broad-market growth income fund like VIG or DGRO acts as the "Core" (comprising 40-60% of the equity sleeve). "Satellite" positions might include more aggressive growth funds or high-yield vehicles like JEPI to tilt the portfolio toward specific income or growth goals.
Tax Considerations: Qualified vs. Ordinary Dividends
In 2026, the tax treatment of your distributions remains a significant factor in your "net" return. Most dividends from the funds mentioned above are "qualified dividends," which are taxed at the lower long-term capital gains rate (0%, 15%, or 20% depending on income). However, income from funds that use covered call strategies (like JEPI) or Real Estate Investment Trusts (REITs) may be taxed as ordinary income.
- Tax-Advantaged Accounts (IRA/401k): Best suited for high-turnover or high-yield funds (REITs, Covered Call ETFs).
- Taxable Brokerage Accounts: Best suited for low-turnover, dividend-growth ETFs (VIG, SCHD) to take advantage of qualified dividend rates.
Risks and Limitations to Monitor
While growth income funds are generally more conservative than pure growth portfolios, they are not without risk.
- Interest Rate Sensitivity: When interest rates rise, income-producing assets often face downward pressure as "risk-free" rates (like Treasury bonds) become more attractive. While 2026 projections show more stability, any sudden hawkish shift by the Federal Reserve can cause temporary price compression in high-yield sectors.
- Sector Concentration: Some dividend funds can become overly concentrated in Financials, Consumer Staples, or Utilities. If these sectors underperform the broader market (e.g., during a massive tech rally), the fund may lag significantly.
- Growth Lag: By definition, companies that pay dividends are diverting cash away from internal reinvestment. In a hyper-growth environment driven by emerging technologies, a growth income fund will likely underperform a pure NASDAQ-style growth fund.
How to Transition Your Portfolio in 2026
If you are currently holding a portfolio heavy in non-dividend-paying growth stocks and wish to transition to a growth-income model, a gradual approach is recommended to manage tax liabilities and market timing.
- Step 1: Audit Your Current Holdings. Identify stocks with high valuations but no dividend yield. Consider trimming these positions, especially those in volatile sectors.
- Step 2: Direct New Contributions. Instead of selling all at once, direct all new investment capital and any existing dividend payouts into your chosen growth income ETFs.
- Step 3: Rebalance Semi-Annually. Check your allocations every six months. In 2026, the divergence between AI-driven growth and traditional value might require manual intervention to keep your risk profile consistent.
For more detailed information on fund regulations and investor protections, you can consult the U.S. Securities and Exchange Commission (SEC) bulletins on mutual fund costs and the Financial Industry Regulatory Authority (FINRA) guides on ETF risks.
Frequently Asked Questions
What is the difference between a Dividend Growth fund and a High Yield fund?
A Dividend Growth fund (like VIG) focuses on companies that consistently increase their payouts, often signaling strong earnings and financial health. A High Yield fund (like VYM) prioritizes companies with the highest current percentage payout. While High Yield funds provide more immediate cash, Dividend Growth funds typically offer better capital appreciation and long-term inflation protection.
Are growth income funds safe for retirees in 2026?
They are generally considered a core component of a retirement strategy because they provide a "natural" income stream that prevents the need to sell shares during a market downturn. However, "safe" is relative; they are still equity products and subject to market volatility. Retirees should always balance these funds with fixed-income assets like bonds or CDs.
Should I choose an ETF or a Mutual Fund for this strategy?
In 2026, ETFs are generally preferred for growth income strategies due to their superior tax efficiency and lower expense ratios. Mutual funds may still be appropriate if they offer a unique active management strategy that is not available in an ETF format, or if you are investing through a 401(k) that has a limited menu of options.
Is the dividend yield the most important factor in a growth income fund?
No. In a growth income strategy, the "Total Return" (capital gains plus dividends) is the most important metric. A fund with a 1.5% yield and 8% annual price appreciation is superior to a fund with a 5% yield and 2% price appreciation. Always look at the combined performance over 3, 5, and 10-year periods.
How does inflation affect these funds?
Growth income funds are traditionally excellent inflation hedges. Companies that can consistently raise their dividends often possess "pricing power," meaning they can pass increased costs on to consumers, thereby protecting their profit margins and their ability to pay shareholders.
Practical Recommendation
For most investors in 2026, the most effective path is to select one "Core" ETF—such as VIG for growth-tilt or SCHD for value-tilt—and commit to a long-term dollar-cost averaging plan. Focus on the expense ratio and the underlying quality of the holdings rather than chasing the highest advertised yield. If you require higher income for immediate expenses, consider allocating a small "Satellite" portion (10-15%) to an actively managed income fund like JEPI to boost your monthly cash flow without compromising your long-term growth potential.
Image Gallery
Select an image to open it in a new tab.
Celine Dubois
Contemporary Living and Global Arts Columnist
