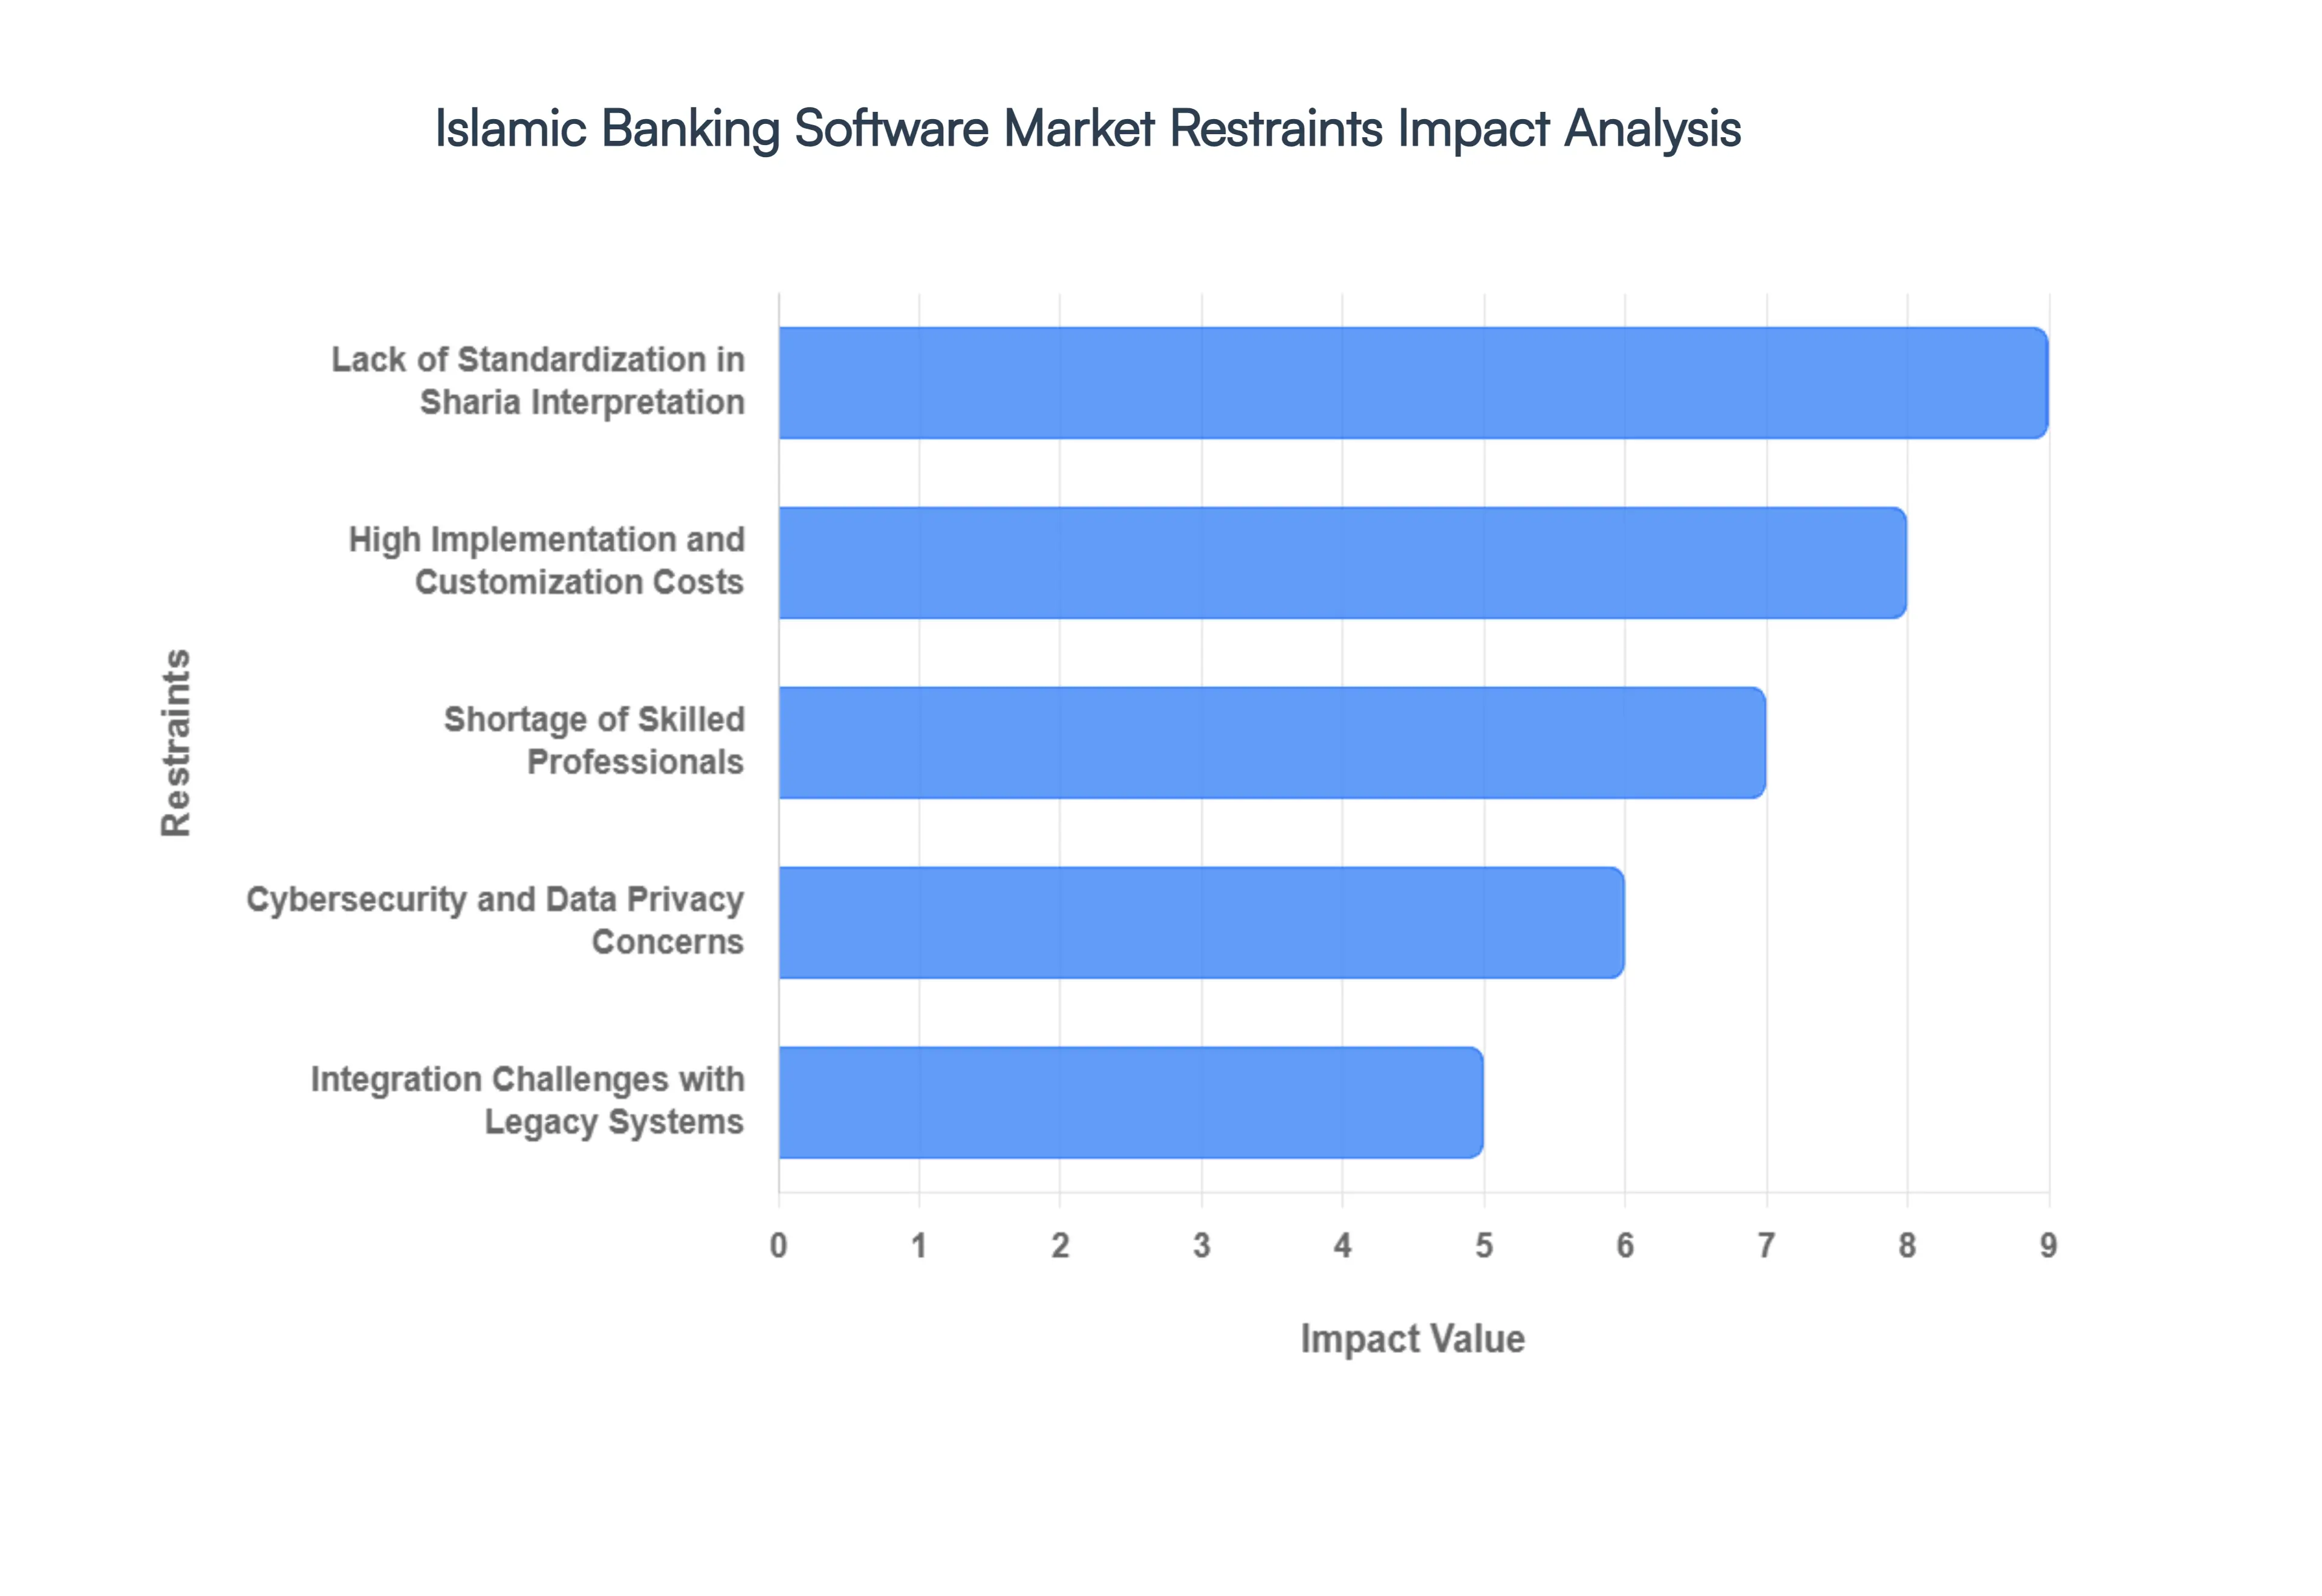
Selecting the right banking software vendor in 2026 requires balancing legacy system compatibility with the integration of generative AI, real-time payment processing, and evolving cybersecurity standards. Financial institutions must rigorously assess vendors based on architectural scalability, regulatory compliance documentation, and the ability to support hybrid cloud infrastructure to ensure long-term operational resilience and competitive agility.
The Evolving Landscape of Core Banking Systems
The banking software sector has transitioned from monolithic, on-premise architectures toward modular, API-first ecosystems. In 2026, the primary challenge for financial institutions is not merely the digitization of services but the transformation of the "core." Vendors now prioritize "composable banking," where institutions can swap out individual components—such as lending modules, card management, or ledger systems—without requiring a full-scale system replacement.
When evaluating vendors, institutions must distinguish between legacy-modernized suites and cloud-native platforms. Cloud-native solutions generally offer higher degrees of elasticity, allowing banks to scale compute resources based on transactional volume, which is critical during peak financial seasons. However, the migration risk remains the highest barrier to entry. Vendors that provide comprehensive data migration toolkits and parallel-run environments should be prioritized over those offering "rip-and-replace" strategies that lack clear contingency planning.
Criteria for Vendor Selection and Due Diligence
Due diligence in 2026 goes beyond feature parity. The focus has shifted toward operational resilience and vendor risk management. Before shortlisting, procurement teams should evaluate potential partners against a standardized framework that includes technical, financial, and legal pillars.
1. Architectural Integrity and API Strategy
An effective banking software vendor must provide a robust, documented API catalog. This ensures that the platform can integrate seamlessly with third-party fintech applications, Open Banking initiatives, and internal data analytics engines. Examine whether the vendor supports industry-standard messaging protocols such as ISO 20022 for payment interoperability.
2. Regulatory Compliance and Jurisdictional Support
Banking software is inherently constrained by regional legislation. Vendors must demonstrate how their software stays compliant with evolving frameworks such as the Digital Operational Resilience Act (DORA) in the EU, or specific regional data residency requirements. A vendor’s inability to provide localized compliance maps is a major red flag.
3. Security and Incident Response
Verify the vendor’s security certifications, such as SOC 2 Type II, ISO/IEC 27001, and PCI DSS compliance. Furthermore, request documentation on their DevSecOps pipeline—how frequently they push security patches, and what their average time-to-remediation is for high-severity vulnerabilities.
Comparative Analysis of Banking Software Categories
The following table outlines the segments within the banking software market to assist in aligning your institution's specific needs with the appropriate vendor profile.
| Segment | Primary Functionality | Target Institution Type | Critical Success Factor |
|---|---|---|---|
| Tier-1 Core Providers | End-to-end processing, multi-currency, massive scale. | Global Systemic Banks | High Availability / Scalability |
| Cloud-Native SaaS | Agile, microservices-based, rapid deployment. | Neo-banks, Digital Challengers | Speed-to-Market / API Depth |
| Niche/Specialized Vendors | Targeted lending, AML/KYC, or trade finance modules. | Community Banks, Credit Unions | Ease of Integration |
| Modernized Legacy | Bridge solutions for older monolithic infrastructures. | Regional Banks (Incumbents) | Data Migration Continuity |
Managing the Implementation Lifecycle
The implementation phase is where most digital transformation projects fail. In 2026, the industry standard has moved toward "phased-in" implementations. Instead of attempting a "big bang" switchover, successful institutions are decoupling their customer-facing digital channels from the core, updating these first, and then incrementally migrating backend processing modules.
Prerequisites for Success
- Data Cleansing: Raw data in legacy systems is often fragmented or improperly mapped. Spend significant time—prior to procurement—mapping data architecture to modern standards.
- Stakeholder Alignment: Ensure that the IT department, the Compliance office, and the Business unit leads are aligned on the total cost of ownership (TCO). This includes not just software licensing, but the long-term support, training, and maintenance costs.
- Change Management: The most significant obstacle is often internal culture. Ensure the vendor provides comprehensive training programs for staff during the onboarding phase.
Common Pitfalls and Troubleshooting
A frequent mistake during the vendor selection process is over-reliance on a vendor's "out-of-the-box" capability. No banking software platform is a complete turnkey solution that requires zero configuration. Institutions often underestimate the "gap analysis" phase—the process of identifying where the vendor's software fails to meet unique operational workflows.
If your institution encounters difficulty during the integration phase, consider the following troubleshooting steps:
- Isolate the Middleware: If an integration fails, determine if the issue lies in the vendor’s API or the bank’s internal middleware layer.
- Audit Data Mapping: Often, transactional failures occur because legacy data formats do not match modern JSON or XML structures utilized by the new vendor.
- Review SLA Compliance: If performance latency occurs, revisit the Service Level Agreement (SLA) to confirm the vendor is providing the committed throughput and server uptime as contractually obligated.
Frequently Asked Questions
What is the difference between core banking software and digital banking platforms? Core banking software manages the internal ledger, account processing, and transactions (the "book of record"). A digital banking platform is the user-facing interface that connects customers to those core services. Many modern vendors offer both, but they are technically distinct components.
How long does a typical core banking migration take in 2026? While smaller institutions can complete a migration in 12 to 18 months, larger institutions typically require 24 to 48 months. The timeline is primarily dictated by the complexity of existing data migration and the number of peripheral legacy systems being retired.
Should we prioritize an on-premise or cloud-based solution? The choice depends on your regulatory environment and existing IT capability. Cloud-based SaaS solutions are significantly faster to deploy and require less local maintenance, but they require strict adherence to third-party risk management protocols as outlined by national financial regulators.
What is the role of Generative AI in banking software? In 2026, GenAI is primarily used for automated document processing, fraud detection pattern recognition, and improving customer support via high-fidelity chatbots. When vetting vendors, look for clear evidence of how their AI models are "explainable" to regulators.
How do we verify vendor claims about system uptime? Do not rely on marketing brochures. Request historical uptime logs for the past three years. Additionally, perform independent testing on the vendor's disaster recovery site, ensuring that the Recovery Time Objective (RTO) meets your internal institutional mandates.
Recommendation for Next Steps
To begin your selection process, form a cross-functional task force consisting of IT, Risk/Compliance, and Business operations leaders. Create a detailed "Requirements Traceability Matrix" (RTM) that maps your specific business pain points against potential vendor features. Before signing any contract, conduct a formal "proof of concept" (PoC) in a sandboxed environment that replicates your most complex transaction workflow. This PoC is your most effective tool for mitigating the risk of vendor lock-in and ensuring technical feasibility.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
