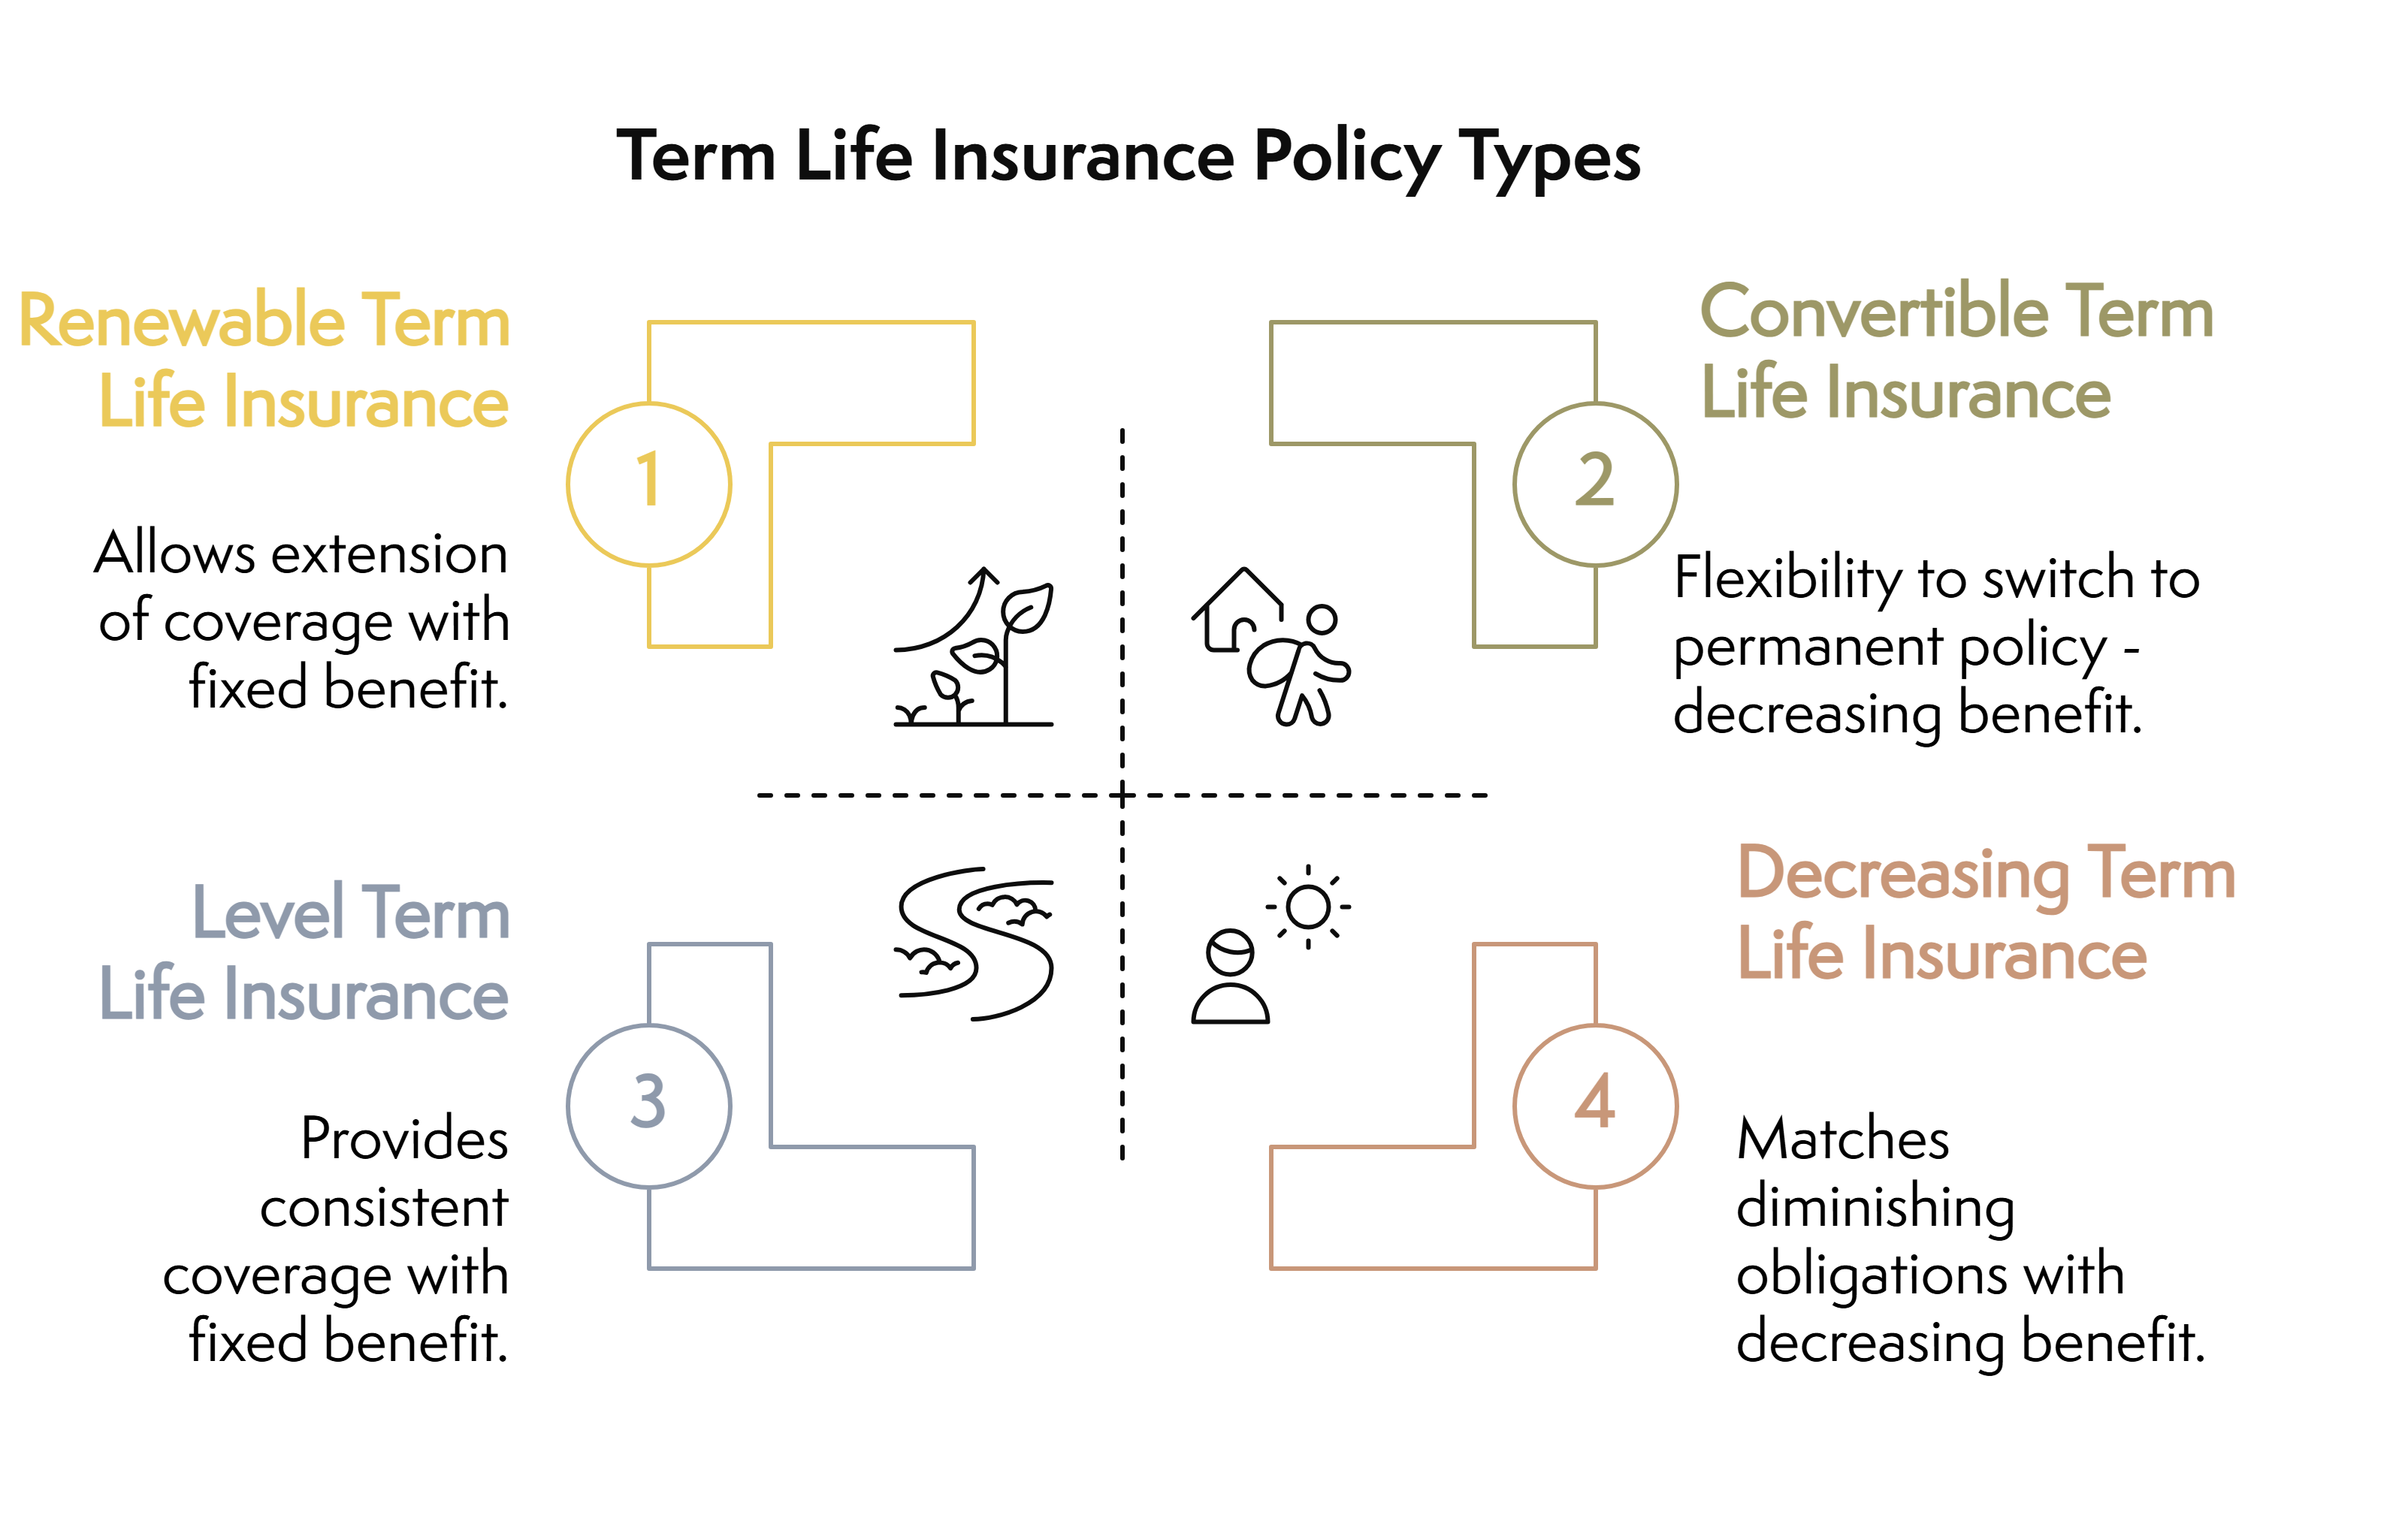
Term life insurance in Sheffield provides a financial safety net for your beneficiaries by paying out a tax-free lump sum if you pass away during a specific, pre-agreed timeframe. In 2026, it remains the most cost-effective way for South Yorkshire residents to secure mortgage repayments, protect family living standards, and cover future educational costs.
Understanding Term Life Insurance in the Sheffield Context
Term life insurance—often referred to simply as "term coverage"—is a straightforward protection product. Unlike "whole-of-life" policies that guarantee a payout whenever death occurs, a term policy only pays out if the claim happens within the "term" or duration of the policy (e.g., 20 or 25 years). If the policyholder survives the term, the coverage simply expires with no cash-in value.
For residents in Sheffield, from the suburban stretches of Dore and Totley to the revitalized urban centers of Kelham Island, this type of insurance is particularly relevant. The local property market and the specific demographic profile of the "Steel City" influence how residents approach financial planning. As we navigate 2026, the emphasis has shifted toward highly flexible policies that can adapt to changing employment patterns in Sheffield’s growing tech and healthcare sectors.
Why "Term" Coverage is Preferred
Most Sheffield families choose term insurance over permanent options because of its affordability. It allows for high levels of coverage during the years when financial vulnerability is at its peak—such as while raising children or paying off a substantial mortgage on a semi-detached home in S10 or S11. By 2026, the integration of digital health data has made these policies even more accessible, with many Sheffield residents qualifying for "instant-issue" term coverage without the need for traditional medical exams.
Primary Types of Term Coverage Available in Sheffield
When seeking term coverage life insurance in Sheffield, you will generally encounter three primary structures. Choosing the right one depends heavily on your specific financial goal, whether that is clearing a debt or providing an ongoing income for a partner.
1. Level Term Insurance
With Level Term insurance, the payout amount (the "sum assured") remains the same throughout the entire duration of the policy. If you take out a £300,000 policy for 25 years, the payout is the same in year 1 as it is in year 24.
- Best for: Family protection and interest-only mortgages.
- Sheffield Considerations: Given the rising cost of living in South Yorkshire over the last few years, many advisors in the city now recommend "index-linked" level term policies. These allow the payout to increase in line with inflation, ensuring that the purchasing power of the benefit remains intact for your loved ones.
2. Decreasing Term Insurance
Often called "Mortgage Protection," the sum assured in a decreasing term policy reduces over time, roughly in line with the remaining balance of a repayment mortgage.
- Best for: Repayment mortgages.
- Sheffield Considerations: With Sheffield’s average house prices seeing steady growth through 2025 and into 2026, decreasing term remains the go-to choice for first-time buyers in areas like Hillsborough or Woodseats. Because the risk to the insurer decreases over time, the premiums are significantly lower than Level Term insurance.
3. Increasing Term Insurance
To combat the effects of inflation, increasing term insurance allows the sum assured to rise annually. This is usually tied to a specific measure, such as the Consumer Price Index (CPI).
- Best for: Long-term financial legacies and protecting against the rising costs of childcare and education.
- Sheffield Considerations: For parents looking toward the future costs of Sheffield’s high-performing schools or the University of Sheffield, increasing coverage ensures that a payout in 15 years will still cover the same real-world costs as it would today.

Factors Influencing Term Life Insurance Costs in Sheffield
Insurance premiums are calculated based on risk. While many factors are national, your lifestyle in Sheffield can play a role in your underwriting process.
Occupational Risks
Sheffield has a high concentration of healthcare professionals working within the Sheffield Teaching Hospitals NHS Foundation Trust and the University of Sheffield. Generally, these professional roles are viewed favorably by insurers, often leading to lower premiums compared to high-risk manual labor or industrial roles. If you work in some of the remaining heavy industrial sectors in the Don Valley, you may find that specific accidental death riders are recommended.
Lifestyle and Health
The "Outdoor City" reputation of Sheffield means many residents are active, participating in cycling, climbing in the nearby Peak District, or running in the city’s many parks. In 2026, many UK insurers offer "wellness discounts" where policyholders can lower their premiums by sharing data from wearable fitness devices. Being an active resident of a hilly city like Sheffield can literally pay off in your insurance premiums.
Smoking and Vaping Status
As has been the case for years, smokers pay significantly higher premiums—often double those of non-smokers. In 2026, insurers are increasingly stringent about vaping, often categorizing e-cigarette users in the same risk pool as traditional smokers unless they have been nicotine-free for at least 12 to 24 months.
Determining How Much Coverage You Need
A common mistake for Sheffield residents is underestimating the "true" cost of their absence. To calculate the appropriate sum assured for term coverage, consider the following four pillars:
- Debt Liquidation: This includes your mortgage balance, car loans, and any outstanding credit card debt.
- Income Replacement: Multiply your annual salary by the number of years your family would need support (e.g., until your youngest child reaches 18 or 21).
- Educational Costs: If you intend for your children to attend private schools or go to university, these costs must be factored in, accounting for tuition and living expenses.
- Final Expenses: While term insurance is not typically bought for funeral costs (that is usually the domain of "Over 50s" plans), a portion of the lump sum can be used to alleviate the immediate financial burden of funeral services in Sheffield.
2026 Term Insurance Premium Estimations
The following table provides estimated monthly premiums for Level Term Life Insurance (Non-Smoker, Standard Health, 20-Year Term) as of 2026. Note that these are illustrative and based on market averages.
| Age | £100,000 Coverage | £250,000 Coverage | £500,000 Coverage |
|---|---|---|---|
| 25 | £5.40 | £8.90 | £14.50 |
| 35 | £7.20 | £12.40 | £21.10 |
| 45 | £14.80 | £28.50 | £52.30 |
| 55 | £33.10 | £74.20 | £142.00 |
Disclaimer: These figures are estimates for 2026. Actual quotes depend on individual medical history, BMI, occupation, and specific policy riders.
Critical Illness Cover: A Vital Addition for Sheffielders
When taking out term coverage life insurance in Sheffield, many residents opt to add Critical Illness Cover (CIC). While life insurance pays out upon death, CIC pays out a lump sum if you are diagnosed with a specific serious illness—such as certain types of cancer, heart attack, or stroke—as defined in the policy.
In 2026, medical advancements mean more people are surviving serious illnesses but require significant time off work for recovery. In a city where many are employed in demanding roles at the two universities or the digital hub at Electric Works, the loss of income during recovery can be devastating. Adding CIC to a term policy ensures that you can pay for private medical costs, modify your home, or simply keep up with mortgage payments while you focus on getting better.
The Role of Local Brokers vs. Online Comparison
Sheffield offers a robust network of independent financial advisors (IFAs) and dedicated insurance brokers, particularly in areas like Ecclesall Road and the City Centre.
The Benefit of Local Expertise
A Sheffield-based broker understands the local economic climate. They can provide face-to-face consultations which are often beneficial for those with "non-standard" requirements, such as pre-existing medical conditions or complex income structures (common among freelancers in the creative industries at the Workstation).
The Speed of Digital Platforms
Conversely, online comparison tools in 2026 are more sophisticated than ever. They utilize "Open Finance" to pull relevant data (with your permission) to provide near-instant underwriting decisions. For a healthy individual with a standard 9-to-5 job in a Sheffield office, online platforms often provide the most competitive rates by stripping away the commission costs associated with traditional brokerage.
Legal Considerations: Placing Your Policy in Trust
One of the most overlooked aspects of term coverage life insurance in Sheffield is the use of a Trust. If you do not place your life insurance policy in a trust, the payout is considered part of your legal estate. This could lead to two major issues:
- Inheritance Tax (IHT): If your total estate exceeds the current thresholds, the government may take up to 40% of the insurance payout in tax.
- Probate Delays: Without a trust, the payout cannot be released until probate is granted, which in 2026 can still take several months. This leaves your family without immediate funds when they need them most.
Most Sheffield solicitors and reputable insurance providers can help you write your policy "in trust" at the time of application, usually at no extra cost. This ensures the money goes directly to your beneficiaries, tax-free and without delay.
Common Pitfalls to Avoid
When arranging your term coverage, be wary of these frequent errors:
- Non-Disclosure: Failing to mention a medical condition or a "social" smoking habit can invalidate your entire policy. Insurers in 2026 have more ways than ever to verify health data during the claims process.
- Only Insuring the Breadwinner: If a stay-at-home parent passes away, the cost of replacing their labor (childcare, cleaning, transport) can be enormous. Both partners should ideally have coverage.
- The "Price-Only" Trap: The cheapest policy isn't always the best. Look at the "added value" services, such as 24/7 virtual GP access or mental health support, which have become standard features for premium insurers by 2026.
- Ignoring Policy Reviews: Life changes fast. A policy taken out when you lived in a small flat in Walkley might not be sufficient once you move to a larger family home in Broomhill or have a second child.
Frequently Asked Questions
Does term life insurance cover terminal illness?
Yes, most term coverage policies in the UK include "Terminal Illness Cover" as standard. This allows the policy to pay out the full sum assured if you are diagnosed with a terminal condition and are expected to have less than 12 months to live. This is distinct from "Critical Illness Cover," which covers a broader range of non-terminal conditions.
Can I change my term policy if I move house within Sheffield?
You don't need to change your policy simply because you move house, but you should review if the coverage amount is still adequate. If you have moved from a terrace in Meersbrook to a larger detached home in S17, your mortgage debt has likely increased, meaning you may need to increase your sum assured to remain fully protected.
What happens if I outlive the term of my insurance?
If you reach the end of the term (e.g., you hit age 65 and the policy was for 25 years), the coverage simply stops. There is no payout, and you do not get your premiums back. This is why term insurance is so much cheaper than whole-of-life insurance; the insurer is only covering the risk of you dying during that specific window.
Are premiums higher for people living in certain parts of Sheffield?
Generally, no. UK life insurers do not typically use specific postcodes (like S1 or S2) to determine premiums in the same way car insurers do. They focus on your personal health, age, and occupation. However, your lifestyle—which may be influenced by your environment—is a factor.
Is COVID-19 still a factor for life insurance in 2026?
By 2026, COVID-19 is treated similarly to other respiratory illnesses. Unless you are suffering from severe "Long COVID" symptoms that impact your ability to work or your long-term organ health, it generally does not negatively affect your ability to get standard term coverage.
Next Steps for Sheffield Residents
If you are considering term coverage life insurance in Sheffield, your first step should be a thorough audit of your finances. Calculate your outstanding debts and determine exactly how much your family would need to maintain their current lifestyle.
Once you have a figure, compare quotes from both major national providers and consider speaking with a local Sheffield broker who can provide tailored advice. Ensure you have your medical history and details of any employer-provided "Death in Service" benefits to hand, as these will influence how much private cover you actually need to purchase.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
