
Securing auto insurance in Lynchburg, Virginia, requires compliance with the Commonwealth’s minimum liability requirements, administered by the Virginia Department of Motor Vehicles (DMV). Residents must maintain specific financial responsibility levels or pay an uninsured motor vehicle fee, while also evaluating optional coverages like comprehensive and collision to protect against local risks such as wildlife collisions and severe weather.
Understanding Virginia’s Financial Responsibility Requirements
In Virginia, operating a motor vehicle is a privilege tied directly to financial responsibility. Unlike many other states that mandate a traditional insurance policy as the only pathway to legal operation, Virginia provides a unique alternative. You must either maintain a motor vehicle liability insurance policy that meets the state's minimum standards or pay the $500 Uninsured Motor Vehicle (UMV) fee to the DMV.
Paying the UMV fee does not provide you with any insurance coverage; it merely grants you the legal right to register and operate an uninsured vehicle. If you cause an accident while your vehicle is registered under the UMV fee, you remain personally and fully liable for all damages, medical expenses, and legal costs. For the vast majority of drivers, maintaining a formal insurance policy is the most prudent financial decision to protect personal assets.
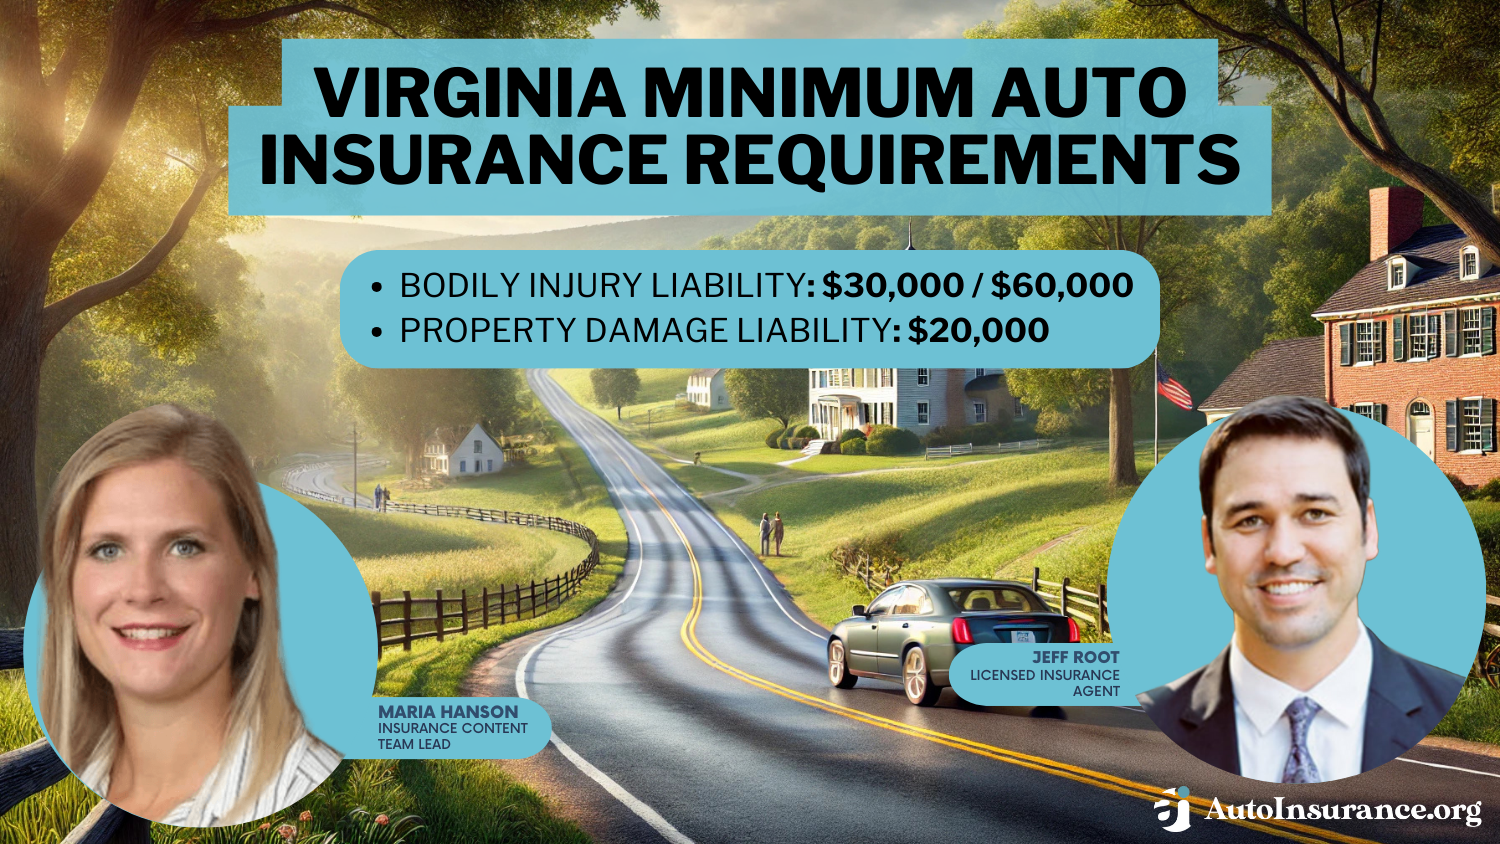
As of 2026, the mandatory minimum liability coverage limits in Virginia are as follows:
- $30,000 for bodily injury or death of one person.
- $60,000 for bodily injury or death of two or more persons.
- $20,000 for property damage.
Factors Influencing Insurance Premiums in Lynchburg
Lynchburg drivers may notice variations in premiums based on several localized and individual factors. Insurance providers use actuarial data to determine risk, and your specific profile—combined with the regional risk environment—dictates your annual or monthly cost.
Regional Risk Profiles
Lynchburg is a city characterized by a mix of urban traffic, suburban sprawl, and proximity to rural roads. Insurance carriers account for the probability of collisions in high-traffic areas like Wards Road or the heavy commuting routes into the downtown area. Furthermore, Virginia’s climate can impact insurance rates; severe storms, flooding potential, and winter weather conditions contribute to the actuarial calculation of "comprehensive" claims, which cover non-collision incidents such as tree limbs falling on a vehicle or flood damage.
Individual Driver Metrics
Beyond your geography, your personal history is the primary engine of your insurance rate. This includes:
- Driving Record: A clean record over the past three to five years is the strongest predictor of lower premiums. Moving violations, at-fault accidents, and license suspensions serve as red flags to underwriters.
- Credit History: In Virginia, insurers are permitted to use credit-based insurance scores as one factor in determining premiums. Maintaining a high credit score generally correlates with lower insurance costs.
- Vehicle Characteristics: The make, model, year, and safety features of your car affect your premium. Newer vehicles with high-tech driver-assist systems might be cheaper to insure due to safety ratings, but they are often more expensive to repair, which can offset those savings.

Types of Coverage: Beyond the State Minimums
While the state mandates minimum liability, these limits are often insufficient in the event of a serious collision. Liability insurance covers the other party; it does nothing to repair your own vehicle or cover your medical bills. To protect yourself comprehensively, consider the following elective coverages:
Collision and Comprehensive
Collision coverage pays for repairs to your vehicle resulting from an accident, regardless of who is at fault. Comprehensive coverage protects against "acts of God" and other non-collision events, including theft, vandalism, fire, and collisions with wildlife—the latter being a common concern in the more forested areas surrounding Lynchburg.
Uninsured/Underinsured Motorist Coverage
Even if you carry insurance, you share the road with drivers who do not. Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage are critical in Virginia. If you are hit by a driver who lacks insurance, or whose insurance limits are too low to cover the full cost of your medical expenses and property damage, this coverage bridges the gap.
Medical Payments (MedPay)
MedPay provides coverage for medical expenses incurred by you or your passengers as a result of an accident, regardless of fault. This can be particularly useful for covering health insurance deductibles or copays immediately following an incident.
Comparison of Coverage Types
The following table outlines the function of various common insurance components to help you distinguish between mandatory requirements and optional protections.
| Coverage Type | What It Covers | Mandatory in VA? | Recommended for |
|---|---|---|---|
| Bodily Injury Liability | Injuries caused to others | Yes | All drivers |
| Property Damage Liability | Damage to other property | Yes | All drivers |
| Collision | Repairs to your own car | No | Financed/Leased cars |
| Comprehensive | Theft, fire, weather, animals | No | All vehicle owners |
| Uninsured Motorist | Damage caused by uninsured | No | All drivers |
| MedPay | Medical bills (any party) | No | Added peace of mind |
Steps to Verify and Maintain Insurance Compliance
Staying compliant with the Virginia DMV is an ongoing responsibility. When you purchase an insurance policy, your provider is required to electronically report your coverage to the DMV.
- Maintain Active Policy: Ensure that your policy never lapses. If you switch insurance providers, ensure the new policy is effective before the old one expires.
- Report Changes: If you move to a new address within Lynchburg or acquire a new vehicle, update your policy immediately. A mismatch between your registration address and your policy address can lead to coverage disputes.
- Keep Proof in Vehicle: Although many law enforcement agencies now use electronic databases, it is a best practice to carry a physical or digital copy of your insurance ID card.
- Monitor Your DMV Record: Periodically review your driver transcript through the Virginia DMV portal to ensure your insurance status is correctly recorded.
Common Mistakes and How to Avoid Them
The most frequent error Lynchburg drivers make is choosing the minimum required liability coverage to save money. If you are involved in a major accident, damages can quickly exceed the $20,000 property damage limit. In such cases, you are personally responsible for the balance, which could place your assets, such as your home or savings, at risk.
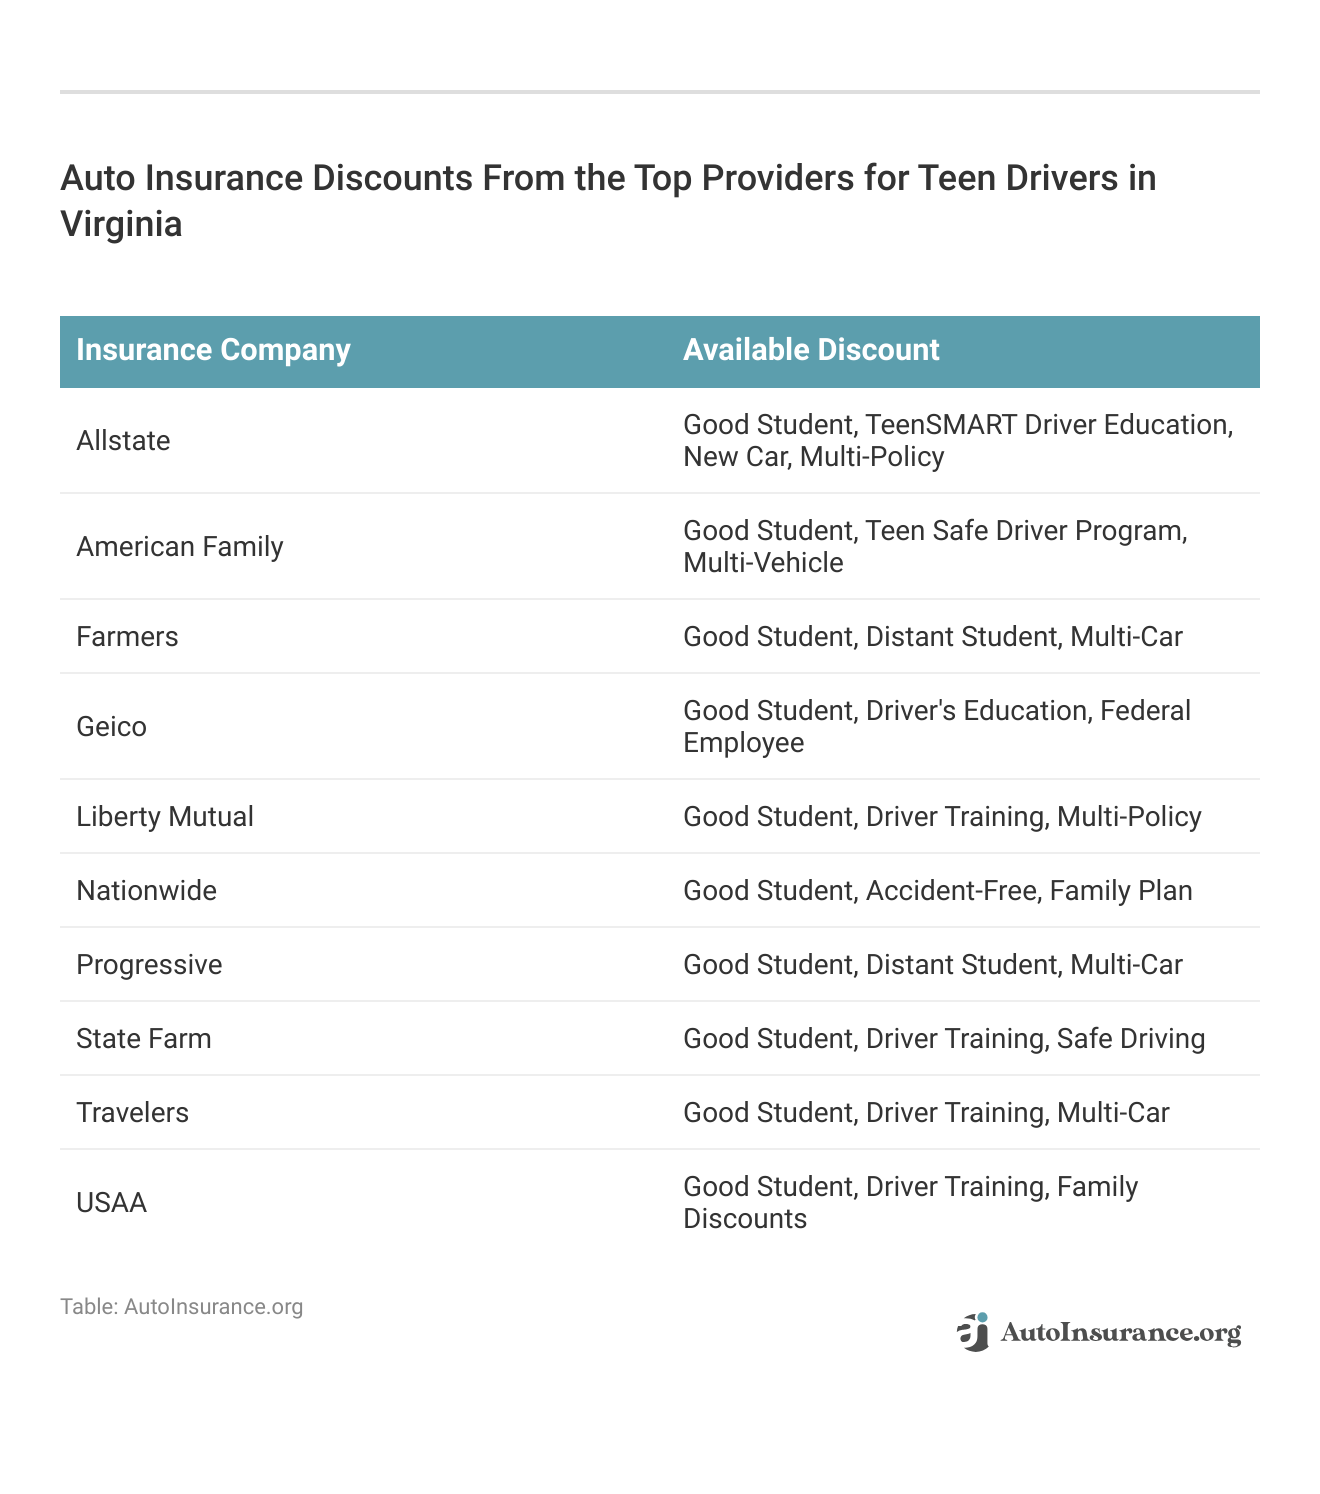
Another common mistake is failing to bundle insurance products. Many carriers offer "multi-policy" discounts if you combine your auto insurance with homeowners or renters insurance. Before finalizing your auto policy, ask your agent or broker if a bundling discount is available, as this is often the most effective way to lower total insurance costs without sacrificing coverage quality.
Finally, do not ignore the "garaging address" when getting a quote. The address where you primarily park your car is essential to accurate pricing. Providing an incorrect address to lower premiums can result in claim denials, as the insurance company may classify this as material misrepresentation.
Frequently Asked Questions
1. Is it cheaper to pay the $500 Uninsured Motor Vehicle fee instead of buying insurance? No. While $500 may seem like a lower upfront cost, it is a fee, not an insurance policy. If you have an accident, you are responsible for every dollar of damage. If you cause a serious accident, the financial loss will vastly exceed the cost of an annual insurance premium.
2. Does Virginia require "no-fault" insurance? No. Virginia is a "fault" or "tort" state. This means that the driver responsible for an accident is legally and financially liable for the damages and injuries caused to others.
3. Will my rate increase if I file a claim for a weather-related incident? Generally, comprehensive claims, such as those for tree damage or glass breakage, are less likely to result in a premium increase than at-fault collision claims. However, specific carrier policies vary, so review your policy document for "surcharge" triggers.
4. Can I get insurance if I have a history of moving violations? Yes, you can obtain insurance, but you may be classified as a "high-risk" driver, which will result in higher premiums. In some cases, if you cannot find coverage through standard carriers, you may need to look into non-standard insurance markets or the Virginia Automobile Insurance Plan (VAIP), which provides coverage to those who have been rejected by standard insurers.
5. Do I need to inform the DMV if I change insurance companies? Usually, your new insurance company will notify the DMV electronically. However, it is wise to keep a copy of your new policy effective date and binder information just in case there is a delay in the electronic reporting system to avoid a temporary suspension notice.
Final Recommendation
To find the best auto insurance in Lynchburg, prioritize quotes from at least three different reputable carriers. Do not rely solely on the state minimums; calculate your personal risk and consider the value of your vehicle and your total assets. Once you have selected a policy, set up automatic payments to prevent accidental lapses. If you find your current premiums are high, ask about available discounts for defensive driving courses, low annual mileage, or safety features installed in your vehicle. Always verify that your agent is licensed to operate in Virginia to ensure your policy is backed by the state’s regulatory framework.
Image Gallery
Select an image to open it in a new tab.

Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
