Why Universal Life Insurance Differs from Term Life Insurance for Most Families

For most families, the primary difference lies in the duration of coverage and the cost structure. Term life insurance provides straightforward protection for a specific period at a low cost, whereas universal life insurance offers permanent coverage with a flexible cash-value component that fluctuates based on interest rates and premium payments.
Selecting the right life insurance policy is one of the most consequential financial decisions a household can make. In 2026, the landscape of financial security has evolved, but the fundamental choice remains between the simplicity of term insurance and the complexity of permanent solutions like universal life (UL). While both products aim to provide a death benefit to beneficiaries, their mechanisms, costs, and long-term implications for a family’s budget differ significantly.
Understanding the Fundamental Mechanics of Term Life Insurance
Term life insurance is often described as "pure" life insurance. It is designed with one singular purpose: to pay a specific sum of money to beneficiaries if the insured individual passes away during a predetermined timeframe. This timeframe, or "term," typically ranges from 10 to 30 years.
For the average family, term insurance acts as a temporary safety net during the years of highest financial vulnerability. These are the years when a mortgage is being paid down, children are growing up, and the loss of a breadwinner’s income would be catastrophic. Because the policy only covers a specific window of time and does not build any internal value, the premiums are significantly lower than any form of permanent insurance.
One of the defining features of term insurance is its level premium structure. When you purchase a 20-year term policy in 2026, your monthly or annual payment remains exactly the same for the duration of those two decades. This predictability is a cornerstone of family budgeting. However, it is important to understand that once the term expires, the coverage ends. If you wish to continue coverage, the cost to renew or purchase a new policy will be substantially higher because it will be based on your older age and current health status.
The Architecture of Universal Life Insurance
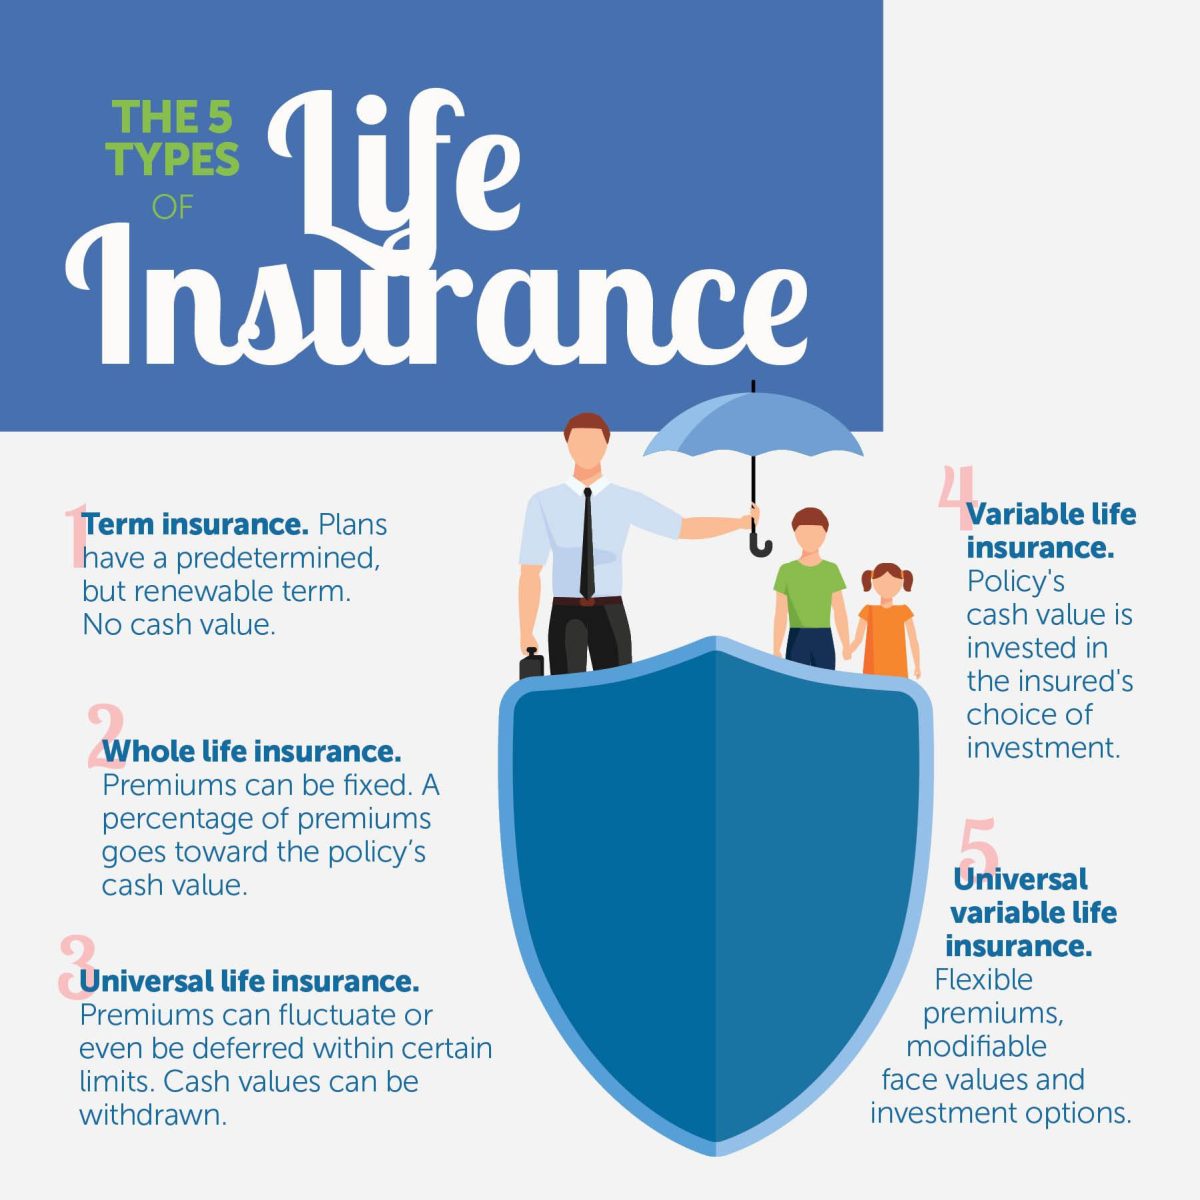
Universal life insurance is a type of permanent life insurance, meaning it is designed to last for the insured's entire lifetime, provided the required premiums are paid. Unlike term insurance, UL policies are "unbundled," meaning the insurance component, the savings (cash value) component, and the administrative expenses are managed separately within the policy.
The "universal" in its name refers to the flexibility it offers the policyholder. Within certain limits set by the insurance carrier and the Internal Revenue Service (IRS), owners of a UL policy can adjust their premium payments and even the death benefit amount. If a family experiences a lean year financially, they may be able to reduce or skip a premium payment by letting the accumulated cash value cover the cost of insurance. Conversely, during high-earning years, they can over-fund the policy to grow the cash value faster.
The cash value in a universal life policy earns interest based on current market rates or a minimum guaranteed rate. In the financial environment of 2026, this interest-bearing feature is often marketed as a way to build a tax-advantaged asset. However, the complexity arises from the rising cost of insurance (COI). As the insured person ages, the actual cost of providing the death benefit increases. If the cash value does not grow sufficiently to cover these rising costs, the policyholder may be forced to pay significantly higher premiums later in life to prevent the policy from lapsing.

Key Differentiators for Family Financial Planning
To choose effectively, families must look beyond the basic definitions and analyze how these products interact with long-term wealth goals and daily cash flow.
Duration and the "Lease vs. Own" Analogy
Term insurance is frequently compared to renting or leasing a home. You pay for the right to occupy the space (the coverage) for a set time. At the end of the lease, you have no equity, but you also had much lower monthly expenses. Universal life is more akin to a mortgage. Your payments are higher because you are building equity (cash value) in an asset that you intend to keep forever.
For most families, the "lease" (term) is sufficient because the need for insurance eventually goes away. Once the kids are through college, the house is paid off, and retirement accounts are funded, the "need" for a $1 million death benefit often disappears.
Premium Volatility vs. Predictability
A major differentiator is the risk of the unknown. With term insurance, the risk is capped: you know exactly what you will pay. With universal life, the policyholder assumes more risk. If interest rates underperform or the insurance company increases its internal fees, the projected cash value might not materialize. Many families have found that universal life policies purchased decades ago now require massive "catch-up" payments to stay active because the underlying assumptions about interest rates were too optimistic.
The Opportunity Cost of Capital
In 2026, the concept of "Buy Term and Invest the Difference" (BTID) remains a popular strategy. Because a $500,000 term policy might cost $40 a month while a $500,000 universal life policy costs $400 a month, a family could take the $360 difference and invest it in a diversified portfolio or a 529 college savings plan. For many, the historical returns of the stock market combined with the lower cost of term insurance provide a higher total net worth over 30 years than the cash value accumulation inside a UL policy.
Comparing Features: Term vs. Universal Life
| Feature | Term Life Insurance | Universal Life Insurance |
|---|---|---|
| Policy Duration | Temporary (10, 20, 30 years) | Permanent (Lifetime) |
| Initial Cost | Lowest; highly affordable | High; 5x to 10x more than term |
| Cash Value | None; no savings component | Yes; grows based on interest/market |
| Premium Flexibility | Fixed; cannot be changed | Flexible; can be adjusted by owner |
| Death Benefit | Fixed for the term length | Adjustable; can be increased or decreased |
| Complexity | Simple; easy to understand | Complex; requires annual monitoring |
| Suitability | Families with high temporary debt | High-net-worth estate planning |
Why "Most Families" Opt for Term Insurance
The statistical reality is that for the vast majority of households, the primary goal of life insurance is income replacement. If a parent dies, the family needs money to replace their salary, pay off the mortgage, and ensure the children can attend university.
Term insurance allows a family to buy a large amount of coverage for a very small price. A young family can often secure $1,000,000 of coverage for less than the cost of a monthly streaming subscription. In contrast, trying to secure that same $1,000,000 through a universal life policy might cost several thousand dollars per year, which often crowds out other important financial goals like retirement savings or emergency funds.
Furthermore, the flexibility of universal life can be a double-edged sword. While the ability to skip premiums sounds attractive, doing so often erodes the policy's long-term health. Most families prefer the "set it and forget it" nature of term insurance, which provides peace of mind without the need for constant financial management of the policy's internal cash accounts.
Scenarios Where Universal Life Becomes Relevant
While term is usually the better fit for the average family, universal life insurance serves specific niches that are important to acknowledge in 2026:
- Lifelong Dependents: If a family has a child with special needs who will require financial support for their entire life, a permanent policy like UL ensures that a death benefit will be available regardless of when the parents pass away.
- High-Net-Worth Estate Planning: For families whose estates exceed the federal or state tax thresholds, the death benefit from a UL policy (often held in an Irrevocable Life Insurance Trust) can provide the liquidity needed to pay estate taxes without selling off family assets.
- Tax-Advantaged Savings for High Earners: For individuals who have already maximized their 401(k), IRA, and HSA contributions, the tax-deferred growth of a UL policy’s cash value can serve as a supplementary "shadow" retirement account.
- Final Expenses: Some families choose a small universal life policy specifically to cover funeral and burial costs, ensuring that these "permanent" needs are met without the expiration risk of a term policy.
Common Mistakes When Choosing Between the Two
A frequent error made by families is under-insuring. Because universal life is so expensive, many families purchase a small UL policy (e.g., $100,000) when they actually need $1,000,000 of coverage to be fully protected. It is almost always better to have $1,000,000 of term insurance than $100,000 of universal life insurance if your family's actual need is the higher amount.
Another mistake is failing to review the illustration of a universal life policy. An illustration is a projection of how the policy might perform. In 2026, agents are required to show both "guaranteed" and "non-guaranteed" values. Families often look only at the optimistic non-guaranteed side, failing to realize that if interest rates drop, the policy could require much higher premiums to stay in force.
Frequently Asked Questions
Can I convert my term policy into a universal life policy later?
Most term life insurance policies include a conversion rider. This allows the policyholder to switch their term coverage to a permanent policy (like universal life) without undergoing a new medical exam. This is a valuable feature for families who start with term due to budget constraints but later decide they need permanent coverage or have developed health issues that would make a new policy expensive.
What happens to the cash value in a universal life policy when I die?
In most standard universal life policies, the beneficiaries receive the face amount (the death benefit), but the insurance company keeps the accumulated cash value. Some policies offer an "Option B" death benefit where the beneficiaries receive both the face amount and the cash value, but these policies typically have significantly higher premiums.
Is term insurance a waste of money if I don't die during the term?
No. Insurance is a purchase of risk transfer, not an investment. Just as you do not consider your car insurance a "waste" because you didn't get into an accident, term insurance is the price paid for the certainty that your family is protected. The "saved" money from choosing term over universal life can be invested elsewhere, often resulting in a larger net worth at the end of the term.
Does universal life insurance have high fees?
Yes, universal life policies typically have higher internal fees than term insurance. These include premium load fees, monthly administrative charges, and the cost of insurance (COI). Additionally, if you try to withdraw your cash value in the first 10 to 15 years of the policy, you may face substantial surrender charges that significantly reduce the amount you receive.
Which is better for a "Buy Term and Invest the Difference" strategy?
Term insurance is the necessary component for this strategy. The goal is to obtain the maximum death benefit for the minimum cost, freeing up as much capital as possible to invest in assets with higher growth potential and lower internal fees than a typical insurance product.
Moving Forward: Next Actions for Your Family
Before committing to a policy, families should conduct a needs analysis. Calculate your total debt, future education costs, and the annual income your family would need to replace. If that total is high—as it is for most young families in 2026—prioritize term insurance to ensure your coverage amount is sufficient.
Consult with a fee-only financial planner who does not earn commissions on the products they recommend. If you are considering universal life, ask for a "stress test" illustration that shows how the policy would perform if interest rates remain at historical lows. For the majority of families, securing a 20 or 30-year term policy remains the most efficient way to protect their loved ones while maintaining the budget flexibility needed to build long-term wealth.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
