Understanding Free Life and Health Insurance Classes: A Complete Guide to Licensing Prep and Education

Free life and health insurance classes provide individuals with foundational knowledge regarding policy structures, risk management, and regulatory compliance. These courses serve two primary audiences: aspiring insurance agents preparing for state licensing examinations and consumers seeking to understand personal coverage. Accessing these classes through state guides, employer sponsorships, and open educational platforms allows learners to master complex concepts without initial tuition costs.
What Are Life and Health Insurance Classes?
Life and health insurance classes are structured educational programs designed to explain how insurance products operate, how claims are underwritten, and how state and federal laws govern the industry. Depending on your goals, these classes focus either on pre-licensing exam preparation or consumer financial literacy.
- LIFE AND HEALTH INSURANCE CLASSES
- Pre-Licensing Education
- Exam prep for prospective agents
- Covers policy mechanics & state law
- Meets state pre-licensing mandates
- Consumer Literacy
- Guidance for policy buyers
- Covers coverage selection & costs
- Provided by non-profits & extensions
- Pre-Licensing Education
Pre-Licensing Education vs. Consumer Financial Literacy
It is essential to distinguish between pre-licensing classes and general financial education:
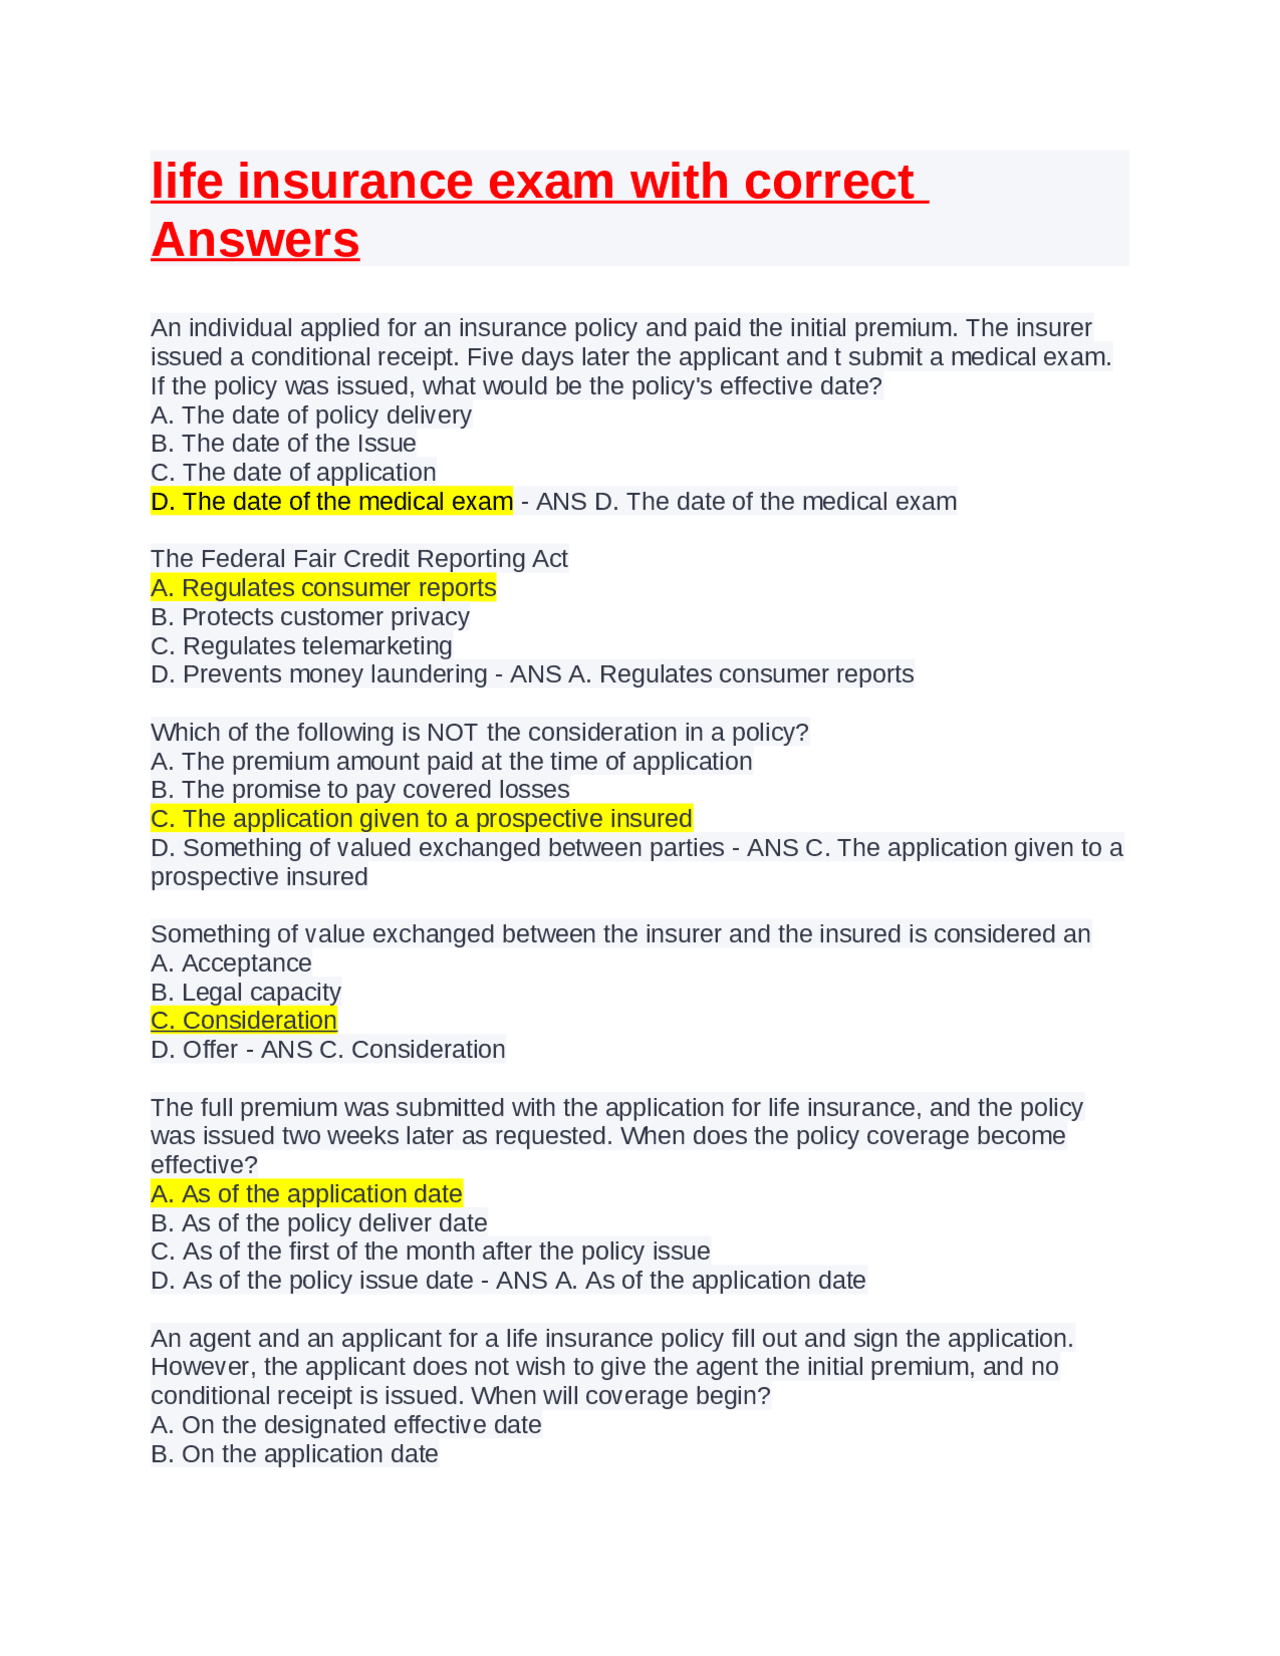
- Pre-Licensing Courses: Targeted at individuals pursuing a professional license to sell, solicit, or negotiate insurance policies. These programs align with test content outlines provided by testing vendors like Pearson VUE, Prometric, or PSI. They cover technical policy language, contract law, agent ethics, and state-specific statutes.
- Consumer Financial Literacy Courses: Aimed at policyholders, employees evaluating workplace benefits, or retirees navigating health options. These classes focus on how to select coverage limits, understand out-of-pocket costs, and integrate policies into broader financial plans.
Core Topics Covered in Standard Curricula
While state requirements vary, standardized life and health insurance curricula generally cover the following core areas:
- Insurance Regulation: The role of the State Insurance Commissioner, licensing requirements, unfair trade practices, and consumer protection statutes.
- General Insurance Concepts: Risk transfer, indemnity, law of large numbers, insurable interest, and elements of a legal contract.
- Life Insurance Products: Term life, whole life, universal life, variable policies, group life, and annuities.
- Health Insurance Products: Individual and group medical expense plans, Disability Income (DI), Long-Term Care (LTC), Medicare Advantage, and Medicare Supplement policies.
- Policy Provisions, Options, and Riders: Beneficiary designations, policy loans, waiver of premium, accidental death benefits, and pre-existing condition limitations.
Where to Find Free Life and Health Insurance Training
While commercial pre-licensing providers often charge between $100 and $300 for study packages, several legitimate avenues offer comprehensive training at no cost.
Employer-Sponsored Pre-Licensing Programs
The most common path to free, structured pre-licensing education is through insurance agencies and brokerage firms. Many captive agencies (such as State Farm, Allstate, or Farmers) and independent marketing organizations (IMOs) sponsor candidates by covering the cost of approved online prep courses.
- Sponsorship Agreements: In exchange for sponsored study materials, agencies may require candidates to contract with them or complete a minimum training period upon passing the exam.
- Direct In-House Training: Some larger agencies conduct classroom or virtual instruction led by experienced agency managers, offering direct mentorship alongside test prep.
State Department of Insurance (DOI) Resources
State insurance regulatory authorities—such as the California Department of Insurance, the Texas Department of Insurance, or the Florida Department of Financial Services—provide valuable free resources on their official websites:
- Candidate Information Bulletins (CIBs): Detailed outlines published by state testing agencies (e.g., Pearson VUE or Prometric) listing every topic, subtopic, and percentage weighting for the state licensing exam.
- State Law Manuals: Many state insurance departments publish downloadable study guides or PDF handbooks covering state-specific insurance statutes and administrative rules.
Non-Profit Organizations and University Extensions
For general consumer education, non-profit institutions and university cooperative extension services offer free webinars and self-paced courses:
- Cooperative Extension System: Land-grant universities frequently host free community workshops covering health insurance literacy, Medicare options, and life insurance planning.
- The National Association of Insurance Commissioners (NAIC): Provides consumer education materials, policy buyer guides, and explanatory content through its InsureU portal.
- Non-Profit Literacy Foundations: Groups focused on personal finance often host free modules covering basic health policy mechanics, health savings accounts (HSAs), and life insurance underwriting.
Open-Access Courses and Free Audits
Online educational platforms and video repositories offer free access to structured lessons:
- Massive Open Online Courses (MOOCs): Platforms like Coursera or edX allow users to audit courses on risk management and healthcare policy from accredited universities without paying for a certificate.
- Public Instructional Videos: Licensed instructors and educators publish topic-by-topic breakdowns on public video platforms covering tricky concepts like annuity payout options, policy riders, and disability elimination periods.
Key Concepts Taught in Life and Health Insurance Courses
Understanding the subject matter requires mastering specific technical terms and policy structures. Below is an overview of the core subjects taught in these classes.
- LIFE & HEALTH INSURANCE TOPICS
- Life Insurance & Annuities
- Term vs. Permanent
- Cash Value Mechanics
- Immediate/Deferred Annuities
- Health Insurance & Provisions
- HMO, PPO, POS, HDHP
- Deductibles & Out-of-Pocket Maximums
- LTC & Disability
- Life Insurance & Annuities
Fundamentals of Life Insurance
Life insurance contracts protect against the risk of premature death and can serve as wealth transfer instruments. Courses break down these policies into distinct categories:
Term Life Insurance
Provides temporary coverage for a specified duration (e.g., 10, 20, or 30 years). It pays a death benefit only if the insured passes away during the term period. Term policies build no cash value, making them the most affordable form of life coverage.
Permanent Life Insurance
Combines a death benefit with an accumulation element known as cash value. Common types include:
- Whole Life: Guarantees fixed premiums, a fixed death benefit, and a guaranteed rate of cash value growth.
- Universal Life: Offers flexible premium payments and adjustable death benefits, with cash value accumulation tied to current interest rates.
- Variable Life: Allows policyholders to allocate cash value into sub-accounts (similar to mutual funds), carrying investment risk and market-dependent growth potential.
Annuities
While not technically life insurance policies, annuities are risk-management products sold by life insurance companies. They convert a lump sum or series of payments into a guaranteed stream of income, protecting retirees against the risk of outliving their assets (longevity risk).
Health Insurance Essentials
Health insurance classes address medical expense coverage, disability protection, and specialized health contracts.
Managed Care Organizations
- Health Maintenance Organizations (HMOs): Emphasize preventive care and require policyholders to select a Primary Care Physician (PCP) who coordinates all care and issues referrals for specialists. Services outside the network are generally not covered.
- Preferred Provider Organizations (PPOs): Offer greater flexibility by allowing members to visit any healthcare provider without a referral, though out-of-network care results in higher out-of-pocket costs.
- Point of Service (POS) Plans: Combine elements of HMOs and PPOs, requiring a primary care referral for specialists while offering partial coverage for out-of-network services.
Disability Income (DI) Insurance
Designed to replace a portion of an worker's lost income if an injury or illness prevents them from working. Classes cover key policy definitions such as Own Occupation (paying benefits if you cannot perform your specific job) versus Any Occupation (paying benefits only if you cannot work in any job for which you are reasonably suited).
Long-Term Care (LTC) Insurance
Covers custodial and medical care for individuals unable to perform basic Activities of Daily Living (ADLs)—such as bathing, dressing, eating, transferring, and toileting—or those suffering from severe cognitive impairment.
Policy Provisions, Options, and Riders
Understanding policy modifications is crucial for passing state exams and evaluating real-world coverage:
- Incontestability Clause: Prevents the insurer from voiding a policy due to misstatements on the application after a specified timeframe (typically two years).
- Grace Period: A mandatory timeframe (usually 30 or 31 days) after a premium due date during which the policy remains active despite unpaid premiums.
- Waiver of Premium Rider: Waives future premium payments if the insured becomes totally disabled.
- Accelerated Death Benefit Rider: Allows a terminally ill policyholder to receive a portion of the death benefit while still living to pay for medical care.
Comparing Free vs. Paid Insurance Pre-Licensing Options
Choosing between free resources and paid training packages depends on your learning style, timeline, and whether your state mandates approved pre-licensing hours.
| Feature / Metric | Free / Open-Source Resources | Employer-Sponsored Programs | Paid Commercial Prep Courses |
|---|---|---|---|
| Out-of-Pocket Cost | $0 | $0 (often requires commitment) | $100 – $300+ |
| State Certificate Included? | Rarely | Yes (if using approved provider) | Yes |
| Study Format | PDFs, Candidate Guides, Public Videos | Self-paced online or classroom | Structured online modules, videos, QBank |
| Practice Exam Quality | Variable / Basic state outlines | Full-length simulated exams | Dynamic test banks with detailed rationales |
| Instructor Support | None | Agency manager or tutor | Live webinars / Instructor Q&A |
| Best Suited For | Self-directed learners, basic prep | Dedicated career changers | Learners in states with strict hour mandates |
Hidden Costs and Licensing Exam Fees
Even when using free study materials, obtaining an insurance producer license involves unavoidable administrative fees charged by state regulators and third-party testing services.
- State Exam Fee: Charged by testing administrators (e.g., Pearson VUE, Prometric, PSI). Fees typically range from $40 to $100 per exam attempt.
- Fingerprinting and Background Check Fees: Most states require background checks prior to licensing, costing between $30 and $70.
- State License Application Fee: Paid directly to the State Department of Insurance upon passing the exam, ranging from $50 to $300 depending on the jurisdiction.
Step-by-Step Guide to Preparing for the Life and Health Insurance Exam
For individuals using free classes and materials to prepare for licensing, following a structured study plan maximizes the chance of passing on the first attempt.
- Step 1: Verify State Requirements
- Step 2: Collect Study Outlines
- Step 3: Build Schedule
- Step 4: Complete Timed Practice Tests
- Step 5: Take State Exam
Step 1: Verify State Requirements
Check your state's Department of Insurance website to confirm pre-licensing education requirements:
- Mandated Hours States: Some states require candidates to complete a set number of approved classroom or online hours (e.g., 20 hours for Life, 20 hours for Health) and earn a Certificate of Completion before sitting for the exam.
- Non-Mandated States: Other states allow candidates to schedule the licensing exam directly without proving completion of a formal pre-licensing course. In these states, free self-study methods are fully sufficient to gain exam eligibility.
Step 2: Download the Official Exam Content Outline
Obtain the specific Candidate Information Bulletin (CIB) from the testing vendor contracted by your state (Pearson VUE, Prometric, or PSI).
Use this outline as your primary master checklist. It provides the exact breakdown of how many questions will appear for each topic, including general concepts and state-specific laws.
Step 3: Develop a Structured Study Schedule
Allocate 30 to 40 hours of study time spread over two to three weeks. Focus on high-weight areas first:
- Week 1: Master General Insurance Concepts, Life Insurance Types, and Health Insurance Structures.
- Week 2: Study Policy Provisions, Riders, Taxes, and Annuities.
- Week 3: Memorize State Insurance Laws, Licensing Rules, and Ethics.
Step 4: Utilize Free Practice Exams
Test your comprehension using sample questions found in state bulletins, open-access study tools, and public review materials.
Focus on understanding why an answer is correct rather than simple rote memorization. Pay close attention to key terms like guaranteed renewable, non-cancellable, incontestable, and insurable interest.
Step 5: Schedule and Take the Examination
Schedule your exam prompt after completing your preparation to keep concepts fresh in your mind.
On test day:
- Bring two forms of valid government-issued ID.
- Arrive at least 30 minutes before your scheduled appointment.
- Pace yourself: most exams allow roughly one minute per question.
- Flag difficult questions for review and complete straightforward questions first.
Frequently Asked Questions
Are state insurance pre-licensing classes completely free?
State insurance pre-licensing classes can be completed for free if you utilize employer sponsorships, free university resources, or study independently in states that do not mandate paid provider certification. However, state administrative fees, background checks, and exam registration fees must still be paid out-of-pocket unless covered by a hiring employer.
How many hours of pre-licensing education are required for Life and Health insurance?
Mandatory pre-licensing hours depend entirely on state regulations. States that require formal education typically mandate between 20 to 40 hours of combined instruction for a joint Life and Health license. Other states have no hour requirements, allowing candidates to sit for the exam whenever they feel prepared.
Can I take the Life and Health Insurance exam without taking a formal class?
Yes, in states without pre-licensing education mandates, candidates can self-study using free state outlines, textbooks, and public reference materials before scheduling their exam directly with the state testing vendor. In states with mandates, candidates must complete an approved course to receive a completion certificate before taking the state exam.
What is the passing score for the Life and Health Insurance licensing exam?
In most states, the passing score for the Life and Health Insurance exam is 70%. Some jurisdictions require a score of 75%. Passing scores are calculated based on raw correct points or scaled scoring systems depending on the state's testing service provider.
How do employer-sponsored free insurance classes work?
Employer-sponsored classes are offered by agencies or brokerages seeking to recruit new producers. The company pays for access to an online pre-licensing course or provides classroom instruction. In return, the candidate typically agrees to work with the agency or meet specific sales targets upon receiving their license.
Recommended Next Steps for Learners
If you are beginning your journey toward understanding life and health insurance or earning your license, start by visiting your state's Department of Insurance website to confirm your local licensing requirements. Download the official Candidate Information Bulletin from your state's testing administrator to obtain the exam content outline. If you are pursuing a career as an agent, research local captive and independent agencies that offer pre-licensing sponsorships to cover training costs. For self-directed study, systematically work through each section of the exam outline using verified public educational resources and free practice questions.
Disclaimer: Insurance licensing rules, pre-licensing education mandates, and examination structures vary by state and jurisdiction. Always verify current administrative procedures directly with your state's Department of Insurance or authorized testing vendor.
Image Gallery
Select an image to open it in a new tab.


Mateo Castillo
Decentralized Finance and E-Payments Strategist
