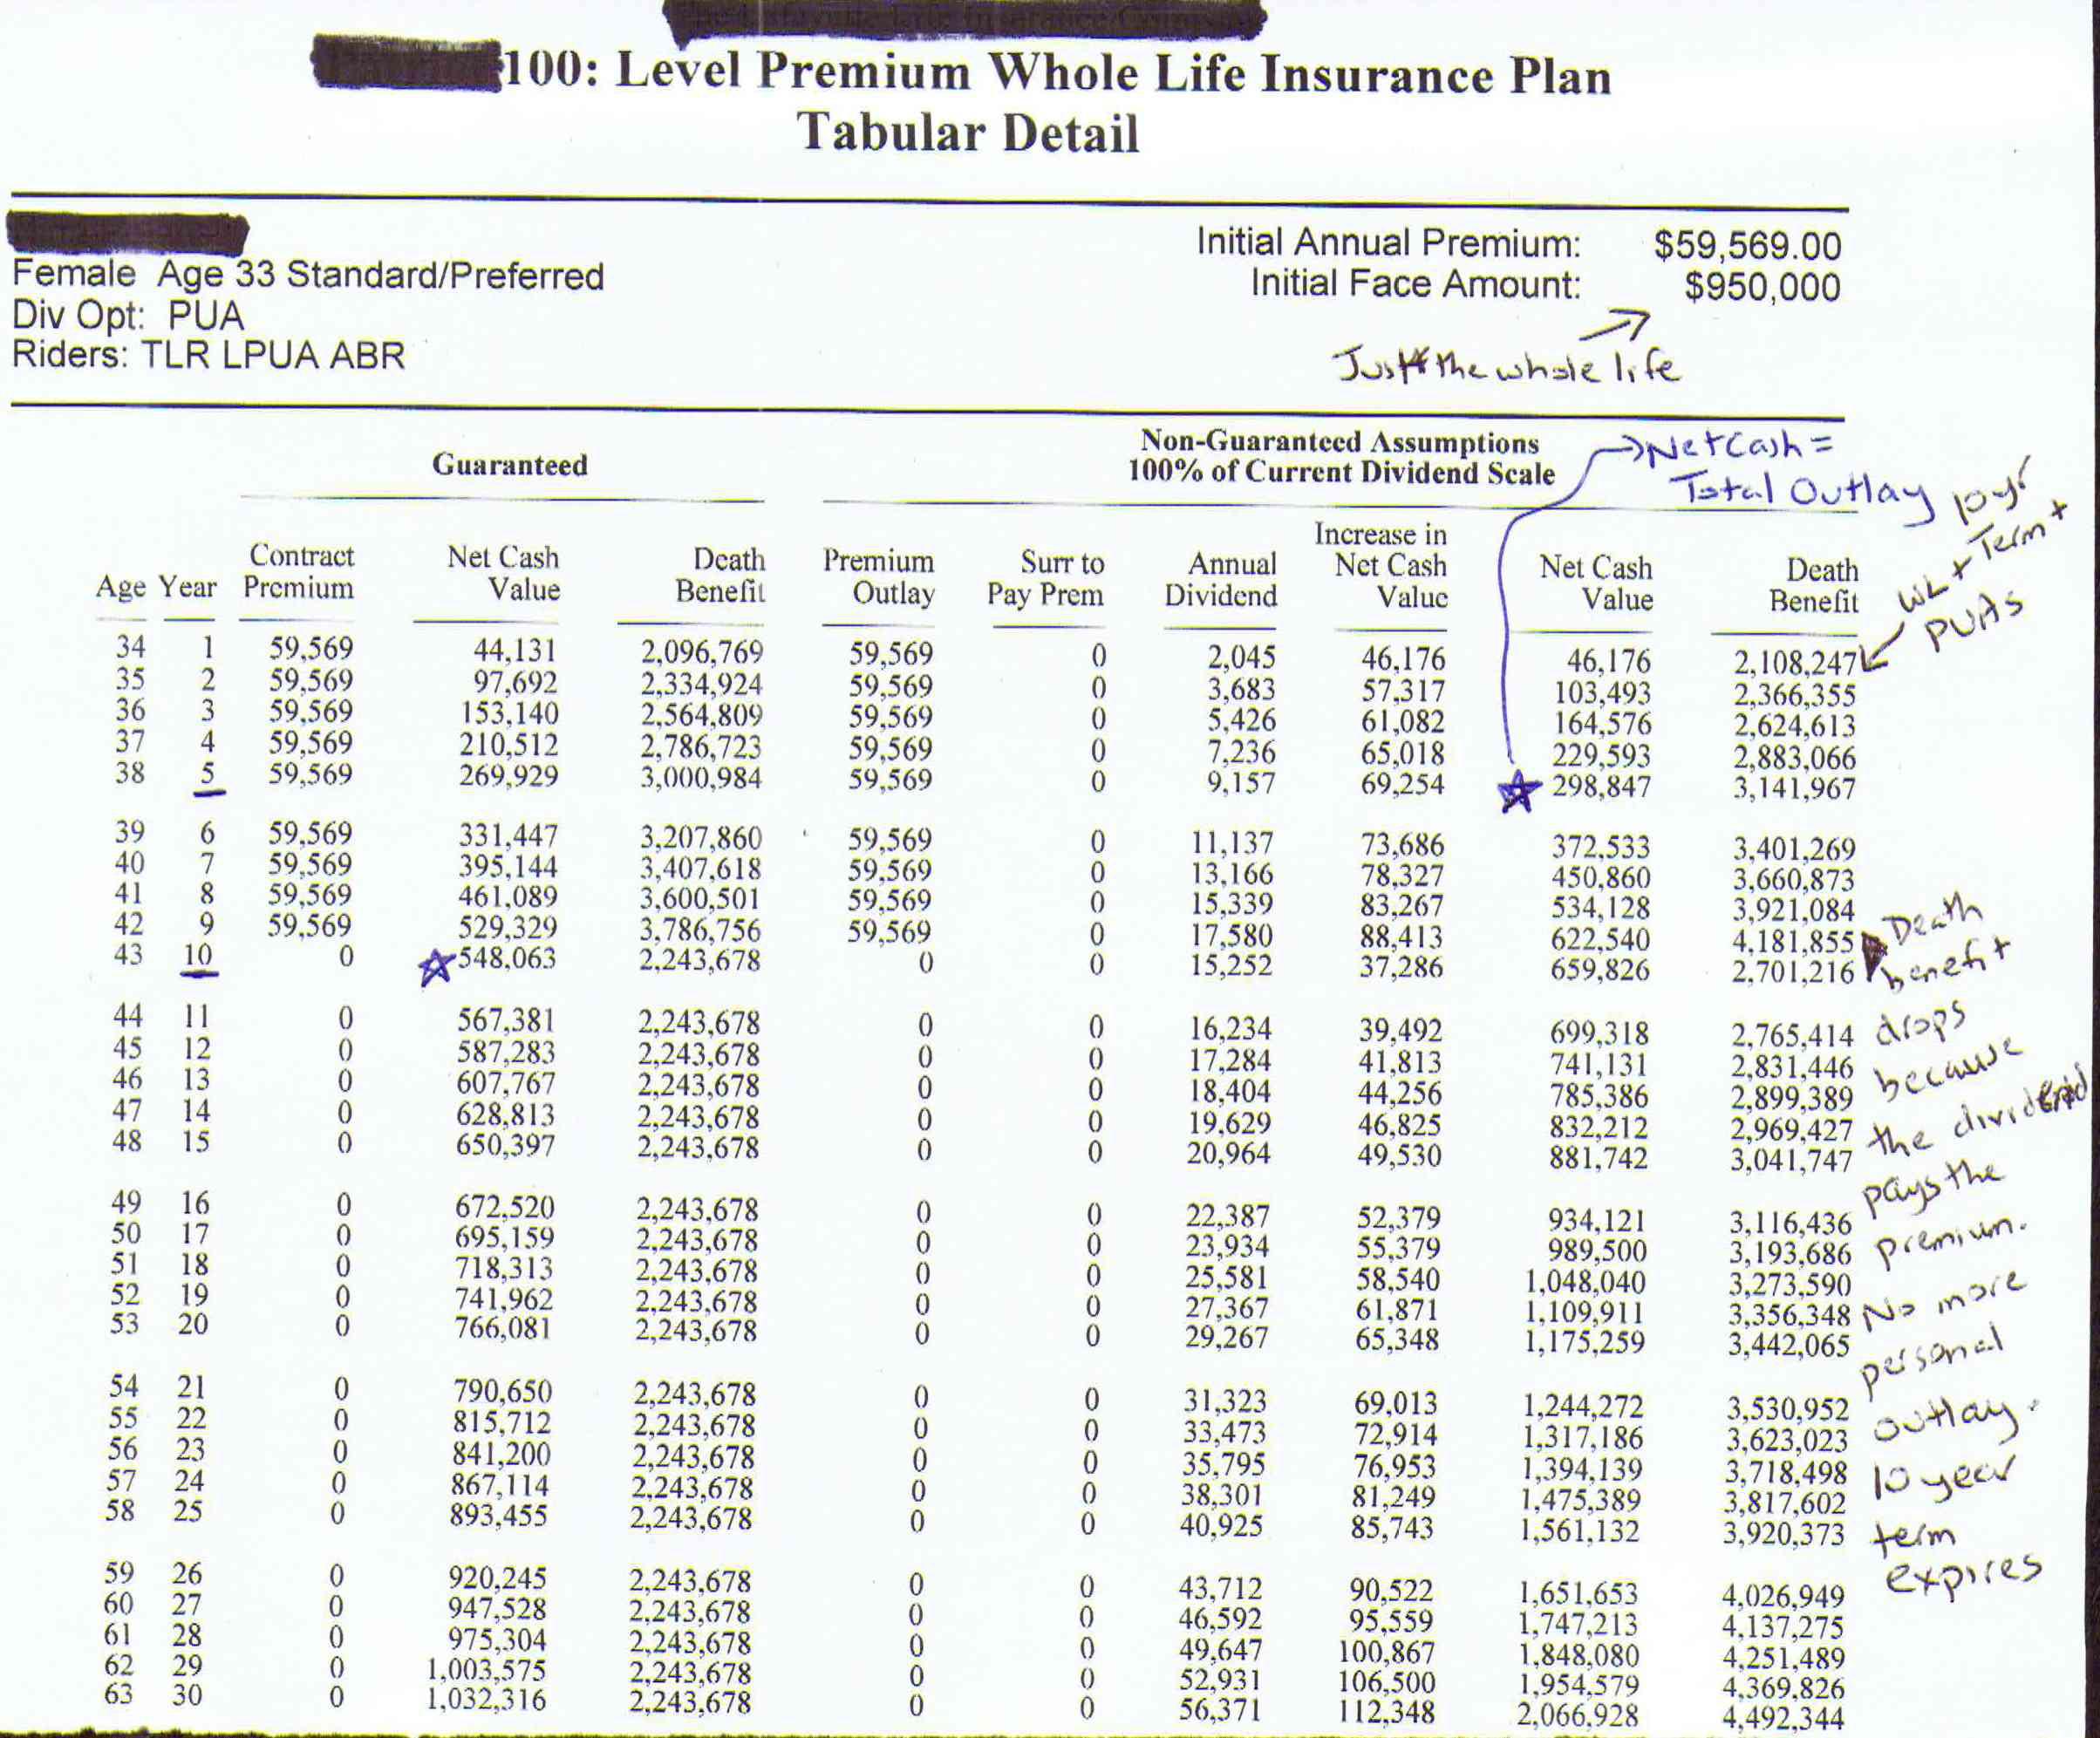
A billion-dollar life insurance policy is a specialized financial instrument, typically structured as a permanent, high-cash-value life insurance contract, designed to provide immense liquidity for estate tax mitigation, business succession, and philanthropic endeavors. These policies are not mass-market products but are bespoke arrangements constructed by private wealth managers, tax attorneys, and high-tier insurance underwriters.
The Mechanism of Ultra-High-Value Coverage
At the billion-dollar level, life insurance transitions from a simple protection product to a sophisticated asset class. These policies are almost exclusively structured as Universal Life (UL), Variable Universal Life (VUL), or Private Placement Life Insurance (PPLI). The primary objective is to create a tax-advantaged vehicle that provides a death benefit sufficient to cover estate taxes or to transfer wealth across generations without triggering immediate capital gains or income tax liabilities.
Unlike standard life insurance, which involves simple medical underwriting and basic health checks, a policy of this magnitude undergoes exhaustive "due diligence" underwriting. This involves the insurer auditing the applicant’s entire financial profile, legal structure, and often, independent medical reviews by specialists. Because no single insurance carrier will typically retain a billion dollars of risk on one life, these policies are syndications. A lead carrier underwrites the policy and then spreads the risk across a consortium of reinsurers, often involving major global entities like Munich Re, Swiss Re, and others.
Primary Drivers for Billion Dollar Policies
The primary catalyst for securing such extreme levels of coverage is the liquidity requirement at the time of death. For individuals with net worths exceeding several billion dollars, estate taxes—which can reach 40% in the United States—present a massive challenge. If a majority of an individual's wealth is tied up in illiquid assets, such as private equity stakes, real estate empires, or family-controlled corporations, the estate may face a forced liquidation to satisfy federal tax obligations.
A life insurance policy provides the "instant liquidity" needed to pay these taxes, allowing the heirs to maintain control over business assets without selling them under duress. Beyond tax mitigation, these policies serve several functional roles:
- Estate Equalization: Ensuring that heirs receiving non-liquid assets are balanced out by others receiving cash from the death benefit.
- Charitable Giving: Creating a "legacy gift" that provides a massive donation to a philanthropic foundation upon the policyholder’s passing, often structured to minimize the income tax burden on the estate.
- Business Succession: Funding buy-sell agreements for global conglomerates where the sudden loss of a key figure could cause a massive fluctuation in market valuation.
Underwriting and Eligibility Requirements
Qualifying for a billion-dollar policy is a rigorous, multi-year process. It requires more than just high income; it requires clear documentation of an insurable interest. Under current financial regulations as of 2026, an insurance company must verify that the beneficiary has a legitimate economic stake in the life of the insured.
Key Stages of the Underwriting Process
- Financial Justification: Applicants must provide comprehensive financial statements, including balance sheets, tax filings, and ownership structures of various holding companies. Underwriters must be convinced that the policy amount is proportional to the potential financial loss caused by the death of the insured.
- Medical Underwriting: This involves "concierge" medical examinations. It is not uncommon for insurers to require reports from multiple specialists, detailed genetic testing, and deep-dive analysis of medical history.
- Legal Review: Because these policies are often held within Irrevocable Life Insurance Trusts (ILITs) or Family Limited Partnerships (FLPs), the legal structure of the policyholder's entire estate must be reviewed to ensure it conforms with state and federal laws.
- Reinsurance Syndication: Once the primary carrier agrees to the policy, they begin the process of laying off the risk. This involves negotiating with global reinsurers, a process that can take six to twelve months to finalize.
Comparing Life Insurance Tiers
The following table differentiates between standard high-net-worth policies and the ultra-high-net-worth billion-dollar category.
| Feature | Standard Term/Whole Life | High-Net-Worth (>$10M) | Billion Dollar Policy |
|---|---|---|---|
| Underwriting | Standard Medical/Financial | Financial/Medical Audit | Forensic Audit/Syndicated |
| Primary Goal | Income Replacement | Estate Tax Liquidity | Succession/Tax Arbitrage |
| Holder | Individual | Trust / Family Office | PPLI / Multi-Entity |
| Risk Bearing | Single Carrier | Carrier + Reinsurance | Global Reinsurance Pool |
| Cost Basis | Fixed Premiums | Optimized/Managed | Leveraged/Premium Finance |
Common Financial Strategies: Premium Financing
It is a misconception that the owner of a billion-dollar policy pays the entire premium out-of-pocket annually. In many cases, these policies are funded through Premium Financing. In this scenario, the policyholder borrows the funds from a private bank to pay the premiums. The loan is collateralized by the cash value of the policy and other assets.
The strategy here is to arbitrage the interest rate on the loan against the long-term growth rate of the policy’s cash value. If the policy is structured correctly, the interest on the loan is tax-deductible (subject to specific 2026 tax codes), and the life insurance proceeds grow tax-deferred. This allows the ultra-wealthy to maintain their liquidity in their primary business ventures rather than tying it up in an insurance contract.
Risks and Operational Limitations
While a billion-dollar policy offers immense benefits, it is not without risk. The most significant is carrier insolvency. While the industry is heavily regulated, the concentration of risk in a single syndicate requires constant monitoring of the financial health of the participating insurance companies.
Additionally, regulatory change remains a persistent threat. Tax codes regarding the taxation of death benefits, the status of life insurance trusts, and the deductibility of premium finance interest are subject to political shifts. A policyholder must engage a "policy maintenance" team—usually a mix of CPAs, trust attorneys, and insurance consultants—to conduct annual reviews of the policy performance versus current market conditions.
Frequently Asked Questions
1. Who typically holds a billion-dollar life insurance policy? These are typically held by ultra-high-net-worth individuals, heads of multi-generational family offices, and owners of private conglomerates. The policy is rarely owned directly by the individual, but rather by an Irrevocable Life Insurance Trust (ILIT) to keep the death benefit proceeds out of the taxable estate.
2. Can an individual be turned down for this amount? Yes. Even if a person has the capital to pay the premiums, they can be declined due to "insurable interest" concerns, high-risk lifestyle factors, or because their financial situation does not adequately demonstrate a requirement for such a high death benefit.
3. Is the payout of a billion-dollar policy taxable? Under current law, the death benefit of a life insurance policy, when properly structured, is generally received by the beneficiary income-tax-free. However, if the policy is not structured within a trust or if ownership transfers occur incorrectly, the proceeds could potentially be included in the taxable estate.
4. How long does it take to secure a billion-dollar policy? The process from initial inquiry to policy issuance typically takes between 12 to 24 months. The complexity of the reinsurance syndication and the depth of the financial investigation necessitate a significant lead time.
5. What happens if the insurance company fails? This is why syndication is critical. A billion-dollar policy is usually backed by a pool of the world’s most secure reinsurers. If one carrier fails, the risk is spread across others. Policyholders also benefit from state insurance guaranty associations, though these are designed for standard consumer policies and would be insufficient to cover a billion-dollar claim, reinforcing the need for top-tier, global carriers.
Practical Next Actions
If you are evaluating the feasibility of a policy of this scale, the first step is not to contact an insurance agent, but to consult with a tax attorney and a fee-only wealth advisor. You must define your estate’s liquidity requirements first.
- Consultation: Request a "liquidity stress test" from your family office to determine exactly how much cash would be required to settle your estate if you were to pass away in 2026.
- Legal Review: Ensure your trust structure is robust enough to act as a beneficiary for a nine-figure payout.
- Audit: Perform a review of your current insurance portfolio; often, these large policies are meant to replace a fragmented series of smaller policies that have become administratively inefficient.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
