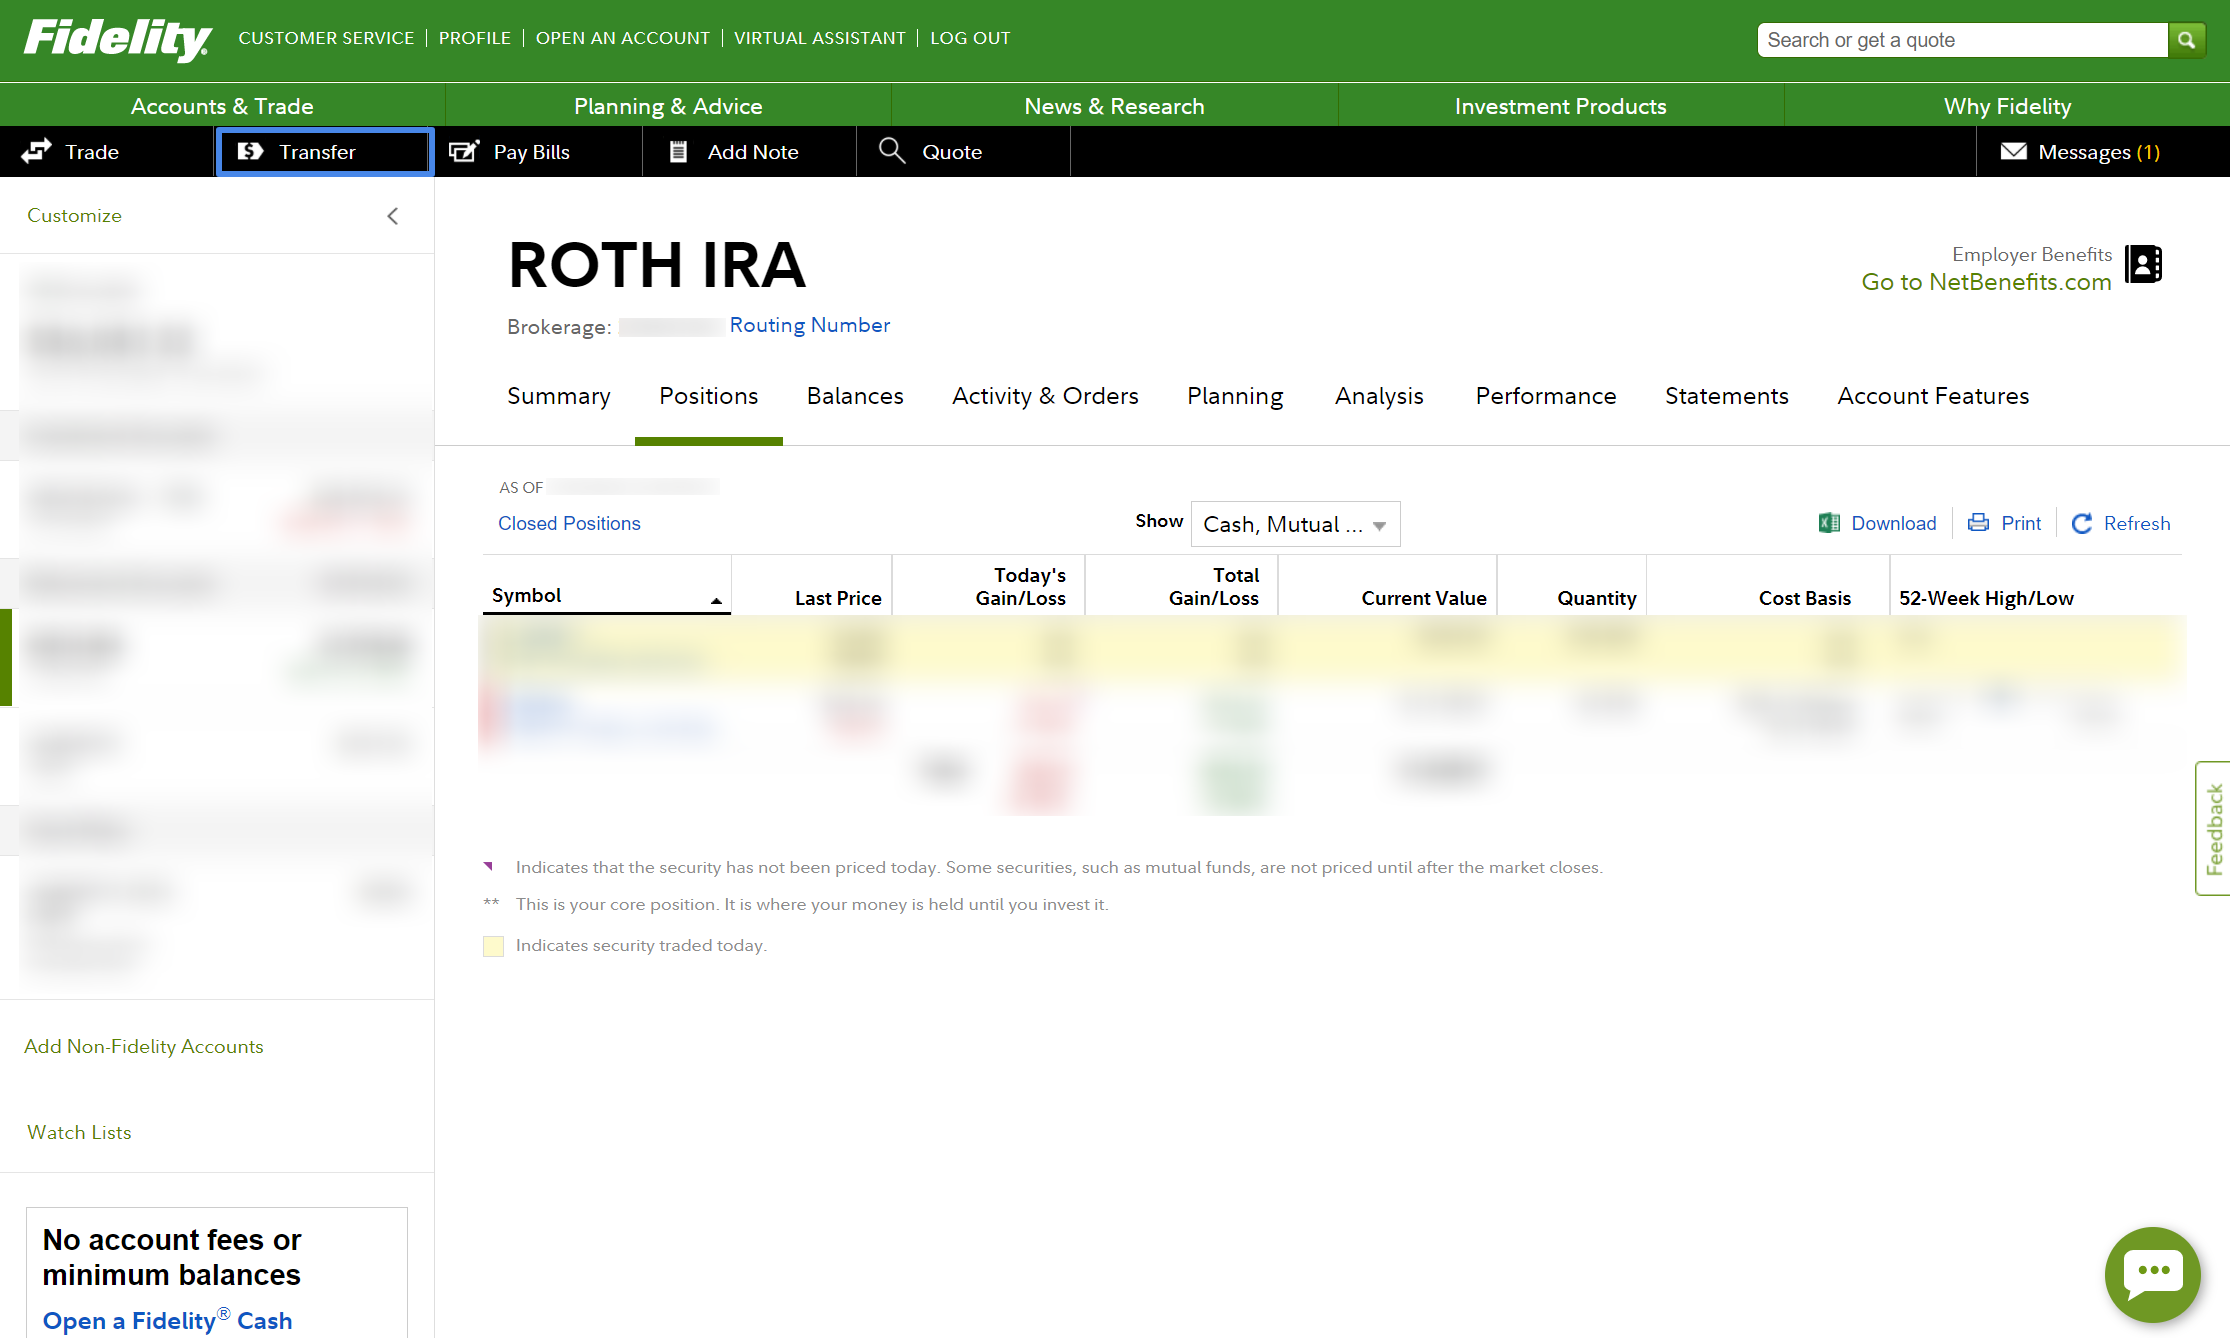
Navigating a Fidelity IRA transfer is often perceived as a daunting hurdle of paperwork, but in 2026, the process is primarily digital and streamlined through the Automated Customer Account Transfer Service (ACATS). While some legacy institutions still require physical forms and Medallion Signature Guarantees, most investors can complete a Fidelity Transfer of Assets (TOA) entirely online within three to five business days without ever touching a physical form.
The Landscape of Fidelity IRA Transfers in 2026
Moving retirement assets to Fidelity Investments remains one of the most common financial maneuvers for investors seeking lower fees, better technology, or consolidated portfolio management. However, the term "transfer form" is frequently misunderstood. In the current financial ecosystem, the "form" is usually a digital data set transmitted between broker-dealers.
When you initiate a transfer to Fidelity, you are essentially giving Fidelity the authority to "pull" assets from your current firm. This process is governed by industry-standard protocols designed to ensure security and tax compliance. Because IRAs are tax-advantaged accounts, the IRS has strict rules regarding how these funds move to avoid triggering "prohibited transactions" or unintended tax liabilities. Understanding the distinction between a Direct Transfer (Trustee-to-Trustee) and a 60-Day Rollover is the first step in separating myth from fact.
Myth vs. Fact: The Truth About Paperwork and Forms
The most significant source of confusion for investors is the requirement for physical documentation. Many believe that moving a retirement account requires a trip to a local branch or a complex mailing process.
Myth 1: Every IRA Transfer Requires a Physical Paper Form
The Fact: Most transfers to Fidelity are handled via the Digital TOA (Transfer of Assets) tool.
As of 2026, Fidelity has integrated most major financial institutions into its electronic "pull" system. If your current assets are held at a major brokerage like Charles Schwab, Vanguard, or E*TRADE, the entire process is paperless. You provide your account number and a recent statement, and Fidelity’s system generates the necessary electronic instructions.
However, there are exceptions. If you are moving assets from a local credit union, a small private bank, or an insurance-based annuity IRA, these "non-ACATS" institutions may still demand a paper form with a wet-ink signature.
Myth 2: A Notary Public Is Required for All Transfer Forms
The Fact: Financial transfers usually require a Medallion Signature Guarantee, which is different from and more rigorous than a standard notary.
Many investors mistakenly visit a notary to authorize their IRA transfer form. A notary only verifies that the person signing the document is who they claim to be. A Medallion Signature Guarantee (MSG), however, is a certification provided by a financial institution that accepts financial liability for the signature's authenticity. If your transfer involves physical certificates or specific high-value assets from a firm not on the ACATS network, Fidelity or the delivering firm may require an MSG. In 2026, many Fidelity Investor Centers can provide this service for customers, but it cannot be done by a standard notary.
Myth 3: You Must Manually Sell Everything Before Submitting the Form
The Fact: Most assets can be moved "In-Kind," meaning you do not have to liquidate your holdings.
A common fear is that submitting a transfer form forces a sale of stocks or ETFs, potentially leading to time out of the market. In reality, most common securities—stocks, bonds, and most ETFs—transfer exactly as they are. The "myth" persists because some proprietary mutual funds (funds owned and managed by your current firm that aren't available at Fidelity) must be sold before the transfer can occur. Fidelity’s digital form tool typically alerts you if a specific asset is ineligible for an in-kind transfer.
The Mechanics of a Fidelity TOA: Step-by-Step Fact-Checking
Understanding the actual timeline and requirements prevents the frustration that stems from unrealistic expectations.
1. The Initiation Phase
When you fill out the Fidelity IRA transfer request, you aren't just "opening an account"; you are signing a legal authorization. Fidelity uses this to communicate with the National Securities Clearing Corporation (NSCC).
- Fact: You will need your most recent account statement from the "delivering firm." The data on the statement must match your Fidelity account profile exactly (e.g., your name, Social Security number, and account type).
2. The Verification Window
Once the digital form is submitted, the delivering firm has a set period to verify the request.
- Fact: Under FINRA Rule 11870, the delivering firm generally has one business day to validate the transfer instruction and three business days to complete the transfer after validation.
3. The "Residual" Sweep
Investors often see a small balance left behind in their old account a few weeks after the transfer.
- Fact: This is not a mistake or a failed transfer. It is a "residual sweep." Dividends or interest payments that were earned but not yet posted at the time of the transfer are automatically swept to the new Fidelity account in subsequent waves, usually occurring weekly or monthly for a short period.
In-Kind Transfers vs. Liquidation Myths
One of the most critical decisions on a Fidelity transfer form is choosing between an "In-Kind" transfer and a "Total Liquidation."
| Feature | In-Kind Transfer | Total Liquidation |
|---|---|---|
| Market Exposure | You remain invested throughout the process. | You are "out of the market" (in cash) for several days. |
| Asset Compatibility | Stocks, ETFs, and most Mutual Funds move as-is. | Everything is sold to cash at the delivering firm. |
| Fees | May incur "per-line-item" transfer fees from the old firm. | May incur trading commissions or capital gains (if in a taxable account). |
| Best For | Long-term investors with standard brokerage assets. | Investors wanting to simplify or move proprietary assets. |
Note: Since this discussion involves IRAs, liquidating assets within the account does not trigger a taxable event as long as the cash remains within the IRA "umbrella."
Fee Structure and Hidden Costs: Fact vs. Fiction
A major point of contention in IRA transfers is the cost. Investors often ask if Fidelity charges a fee to "get their money in."
The Fact on Incoming Fees: Fidelity does not charge a fee to receive an IRA transfer. They do not charge an account opening fee or an annual maintenance fee for most retail IRAs.
The Fact on Outgoing Fees: Your current firm will almost certainly charge an ACAT Outbound Fee. This fee typically ranges from $50 to $125.
- The Reimbursement Myth: Many believe Fidelity will automatically pay this fee. In reality, Fidelity often reimburses transfer fees for accounts above a certain threshold (often $25,000 or more), but you usually have to request the reimbursement through a specific online form or by speaking with a representative after the transfer is complete.
Navigating Complex Transfers (Employer Plans and Non-ACATS)
Not all IRA transfers move through the "standard" form. If you are moving money from a 401(k), 403(b), or a government 457(b), the rules change significantly.
Employer Plan Rollovers
You cannot simply "pull" money from a 401(k) using a Fidelity TOA form.
- Fact: You must contact the administrator of your employer plan (e.g., Alight, Empower, or even Fidelity NetBenefits) to initiate a Direct Rollover. The employer plan administrator must "push" the funds to your Fidelity IRA. This often involves the mailing of a physical check, although some modern providers now support direct electronic transfers (wire or ACH) to Fidelity.
Non-ACATS Transfers
If you are moving a specialized asset, such as a physical gold IRA or a private equity holding within a self-directed IRA, a standard digital form will not suffice. These require specialized "Alternative Asset" forms and often involve manual processing that can take 3 to 6 weeks.
Common Pitfalls and Troubleshooting
Even with the advancements of 2026, errors occur. Most issues with Fidelity IRA transfer forms stem from three areas:
- Account Title Mismatch: If your old account is a "Joint Tenant" account and you try to move it into an "Individual IRA" at Fidelity, the transfer will fail. The ownership must be identical.
- Unsettled Trades: If you sell a stock on Monday and try to initiate the transfer on Monday afternoon, the form might be rejected because the trade has not "settled" (usually T+1 in 2026).
- Margin Balances: If you have a debit balance (money owed) in your old account, the delivering firm may block the transfer until the debt is cleared or until Fidelity agrees to take over the margin debt (which requires a margin-approved account at Fidelity).
FAQ
Does Fidelity provide a paper IRA transfer form if I prefer one?
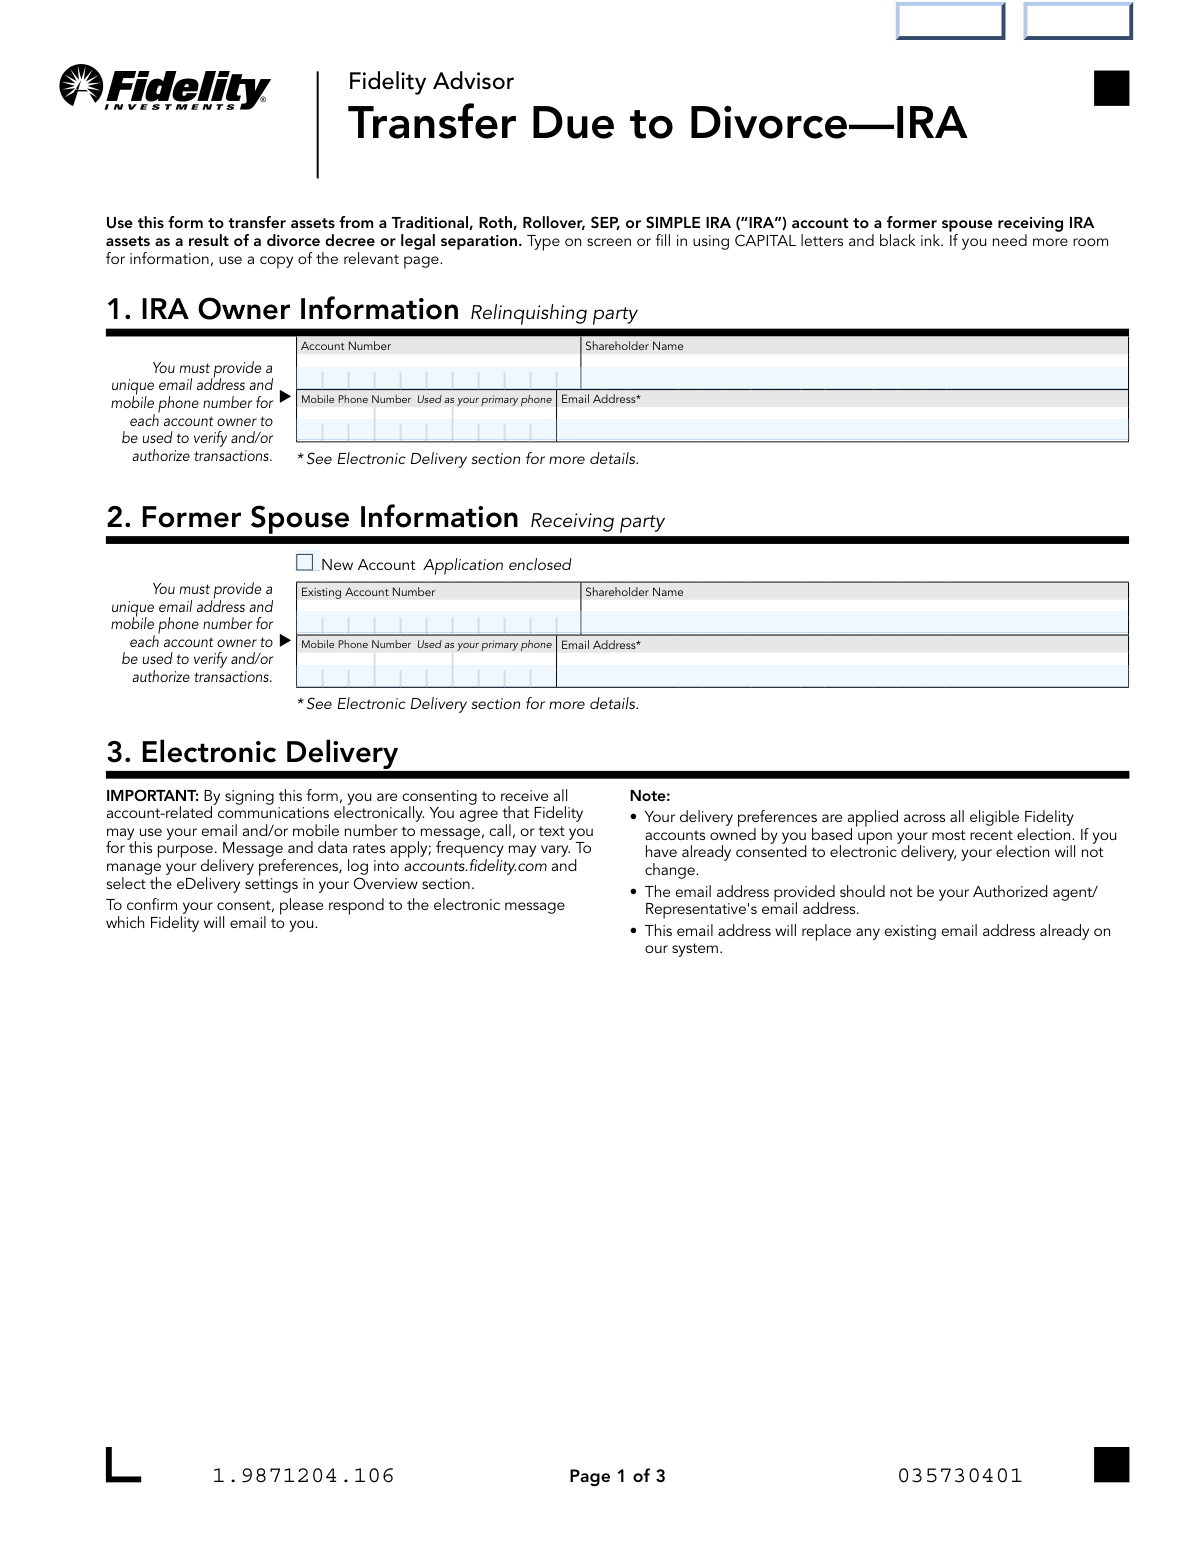
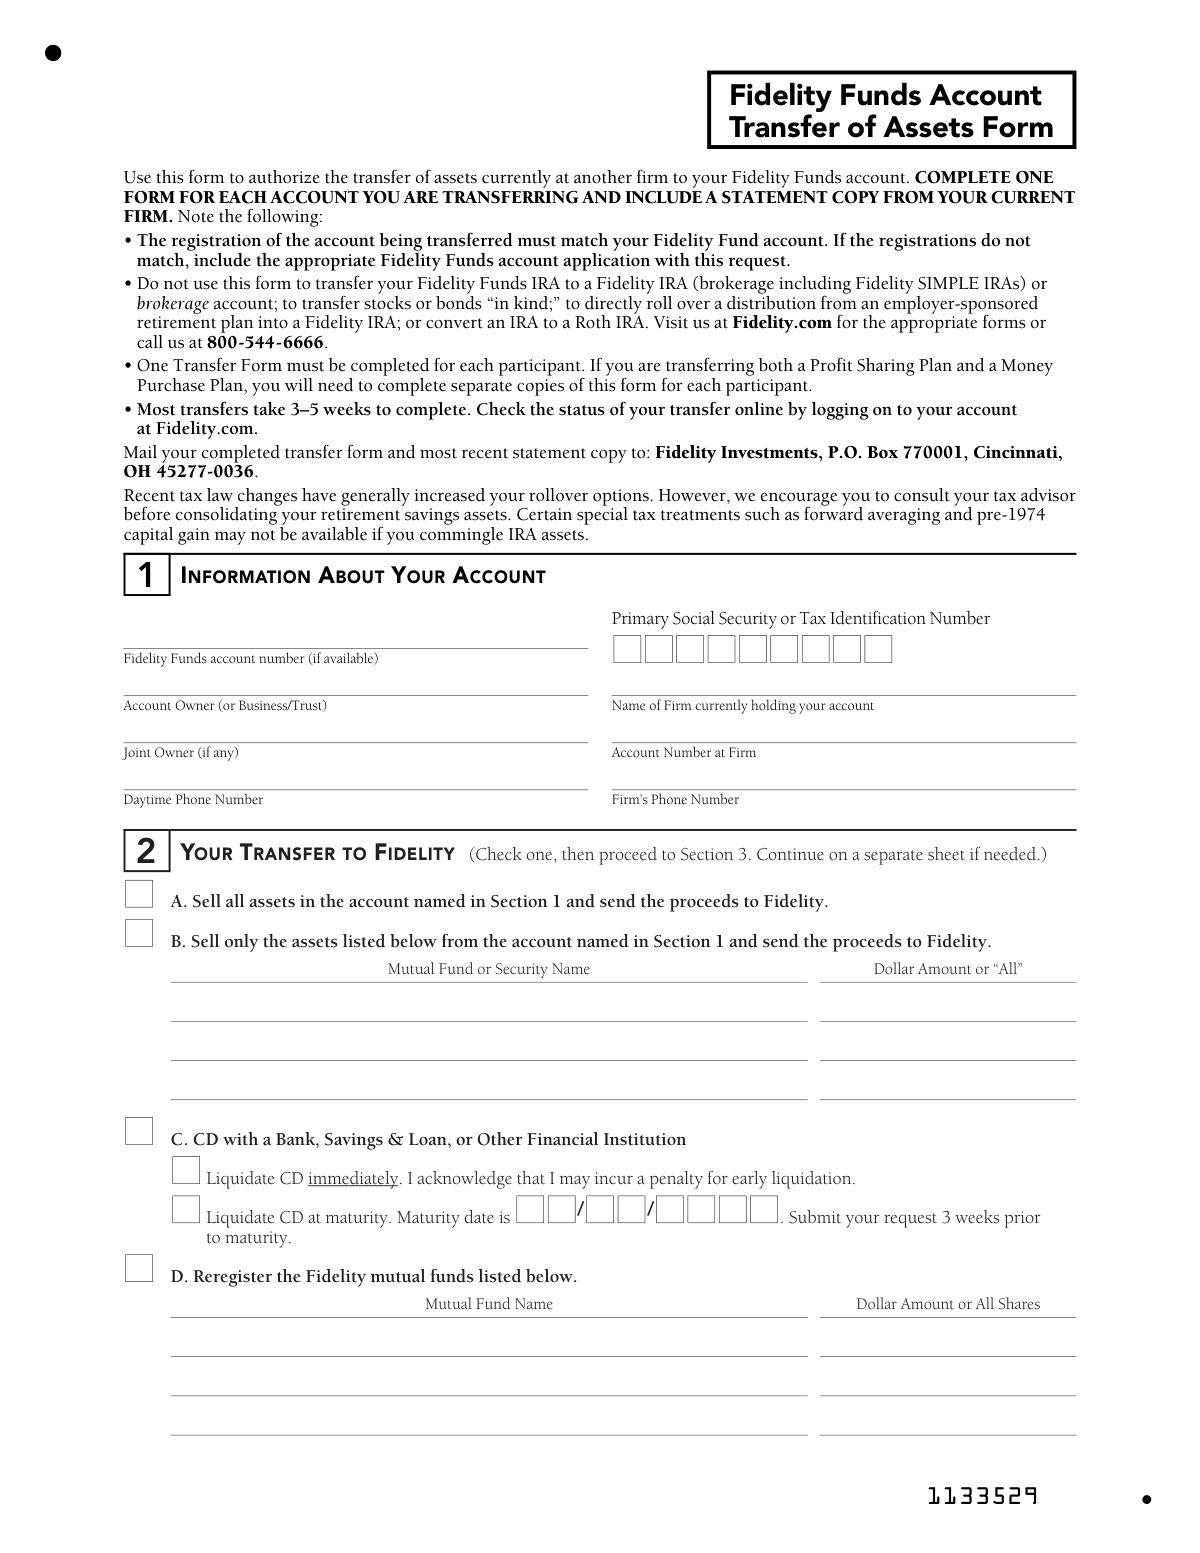
Yes. While Fidelity pushes the digital TOA process for speed and accuracy, you can still download a PDF version of the "Transfer of Assets" form from their official website. This is sometimes necessary if you cannot access the online portal or if the delivering firm requires a "wet-ink" signature.
How long does the Fidelity IRA transfer form take to process in 2026?
For standard ACATS-eligible brokerage accounts, the process takes 3 to 5 business days. For rollovers from employer-sponsored plans (like a 401k), it can take 2 to 4 weeks depending on whether the former employer mails a physical check.
Will I lose money during the transfer?
If you transfer "in-kind," your shares move without being sold, so you do not lose market exposure. If you liquidate to cash, you may "lose" money if the market rises while your funds are in transit as cash. Additionally, check for any "Account Closure Fees" from your current provider, as these are deducted from your balance.
Can I transfer a Roth IRA into a Traditional IRA?
No. This is a common misconception. You can only move "like-to-like" (Roth to Roth, Traditional to Traditional). If you wish to move money from a Traditional IRA to a Roth IRA, you must first transfer it to a Fidelity Traditional IRA and then perform a Roth Conversion, which is a taxable event.
What if my current firm is not in Fidelity's dropdown list?
If your firm is not listed in the digital TOA tool, it likely means they do not participate in the ACATS network. In this case, you will be prompted to print a paper form, sign it, and either upload it via Fidelity’s secure message center or mail it to their processing hub in Cincinnati or Salt Lake City.
Practical Recommendation
To ensure the fastest and most secure transfer, start by gathering your most recent statement from your current firm. Log into the Fidelity website and use the "Transfer an Account to Fidelity" tool rather than searching for a PDF form. The digital tool performs real-time validation of your account numbers and firm details, which significantly reduces the chance of rejection.
If your account balance is over $25,000, keep a record of any "Exit Fees" or "Closeout Fees" charged by your old broker. Once the assets arrive at Fidelity, contact their customer service or use the online "Fee Reimbursement" request tool to see if you qualify for a credit to cover those costs. Always opt for an "In-Kind" transfer to avoid unnecessary time out of the market unless you specifically intend to overhaul your investment strategy.
Disclaimer: This information is for educational purposes only and does not constitute financial, legal, or tax advice. Investment involves risk, and retirement account rules are subject to IRS regulations. Consult with a qualified financial advisor or tax professional regarding your specific situation. Internal Revenue Service (IRS) Publication 590-A provides official guidance on contributions and transfers.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
