Understanding Commerce Finance: A Comprehensive Overview of Modern Business Funding, Management, and Strategy

Commerce finance encompasses the structural framework of capital acquisition, cash flow management, risk mitigation, and strategic resource allocation that sustains modern commercial enterprises. By balancing debt, equity, liquidity, and operational expenses, businesses can maintain daily operations while investing in long-term expansion.
Defining Commerce Finance and Its Core Objectives
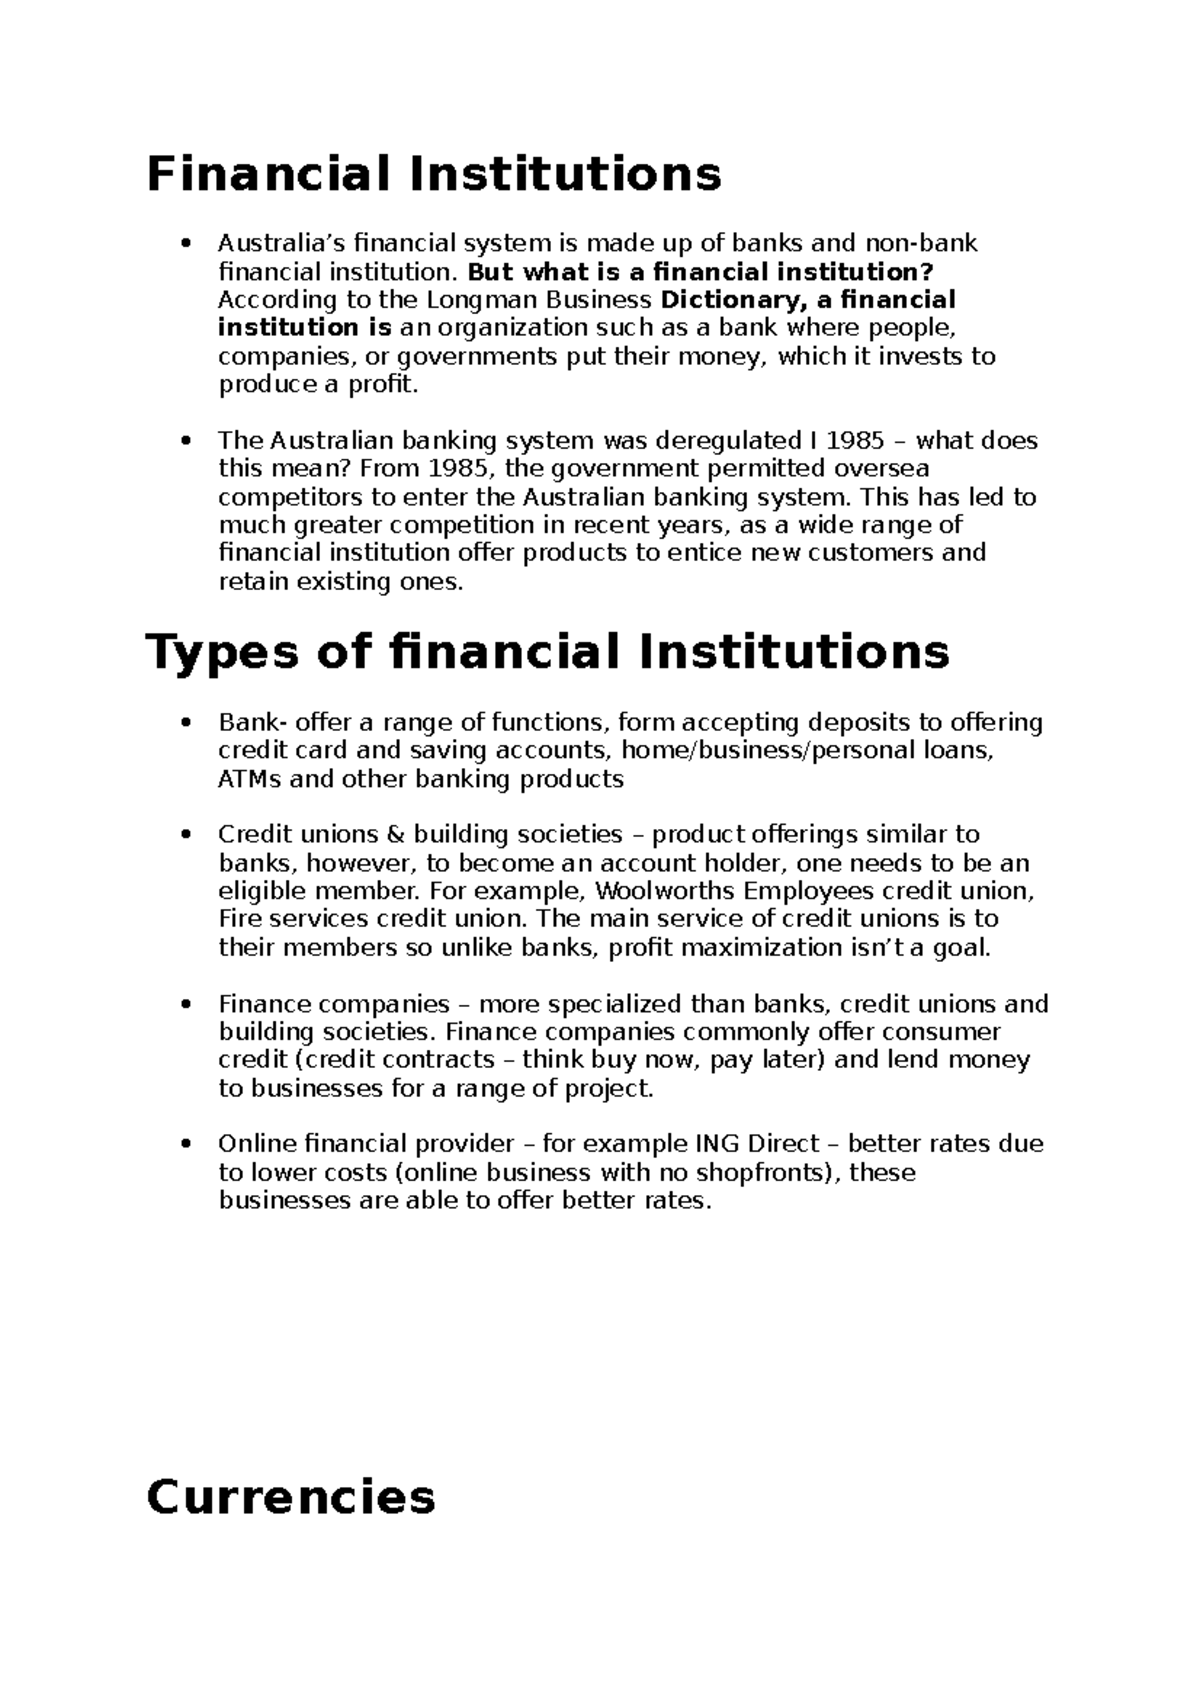
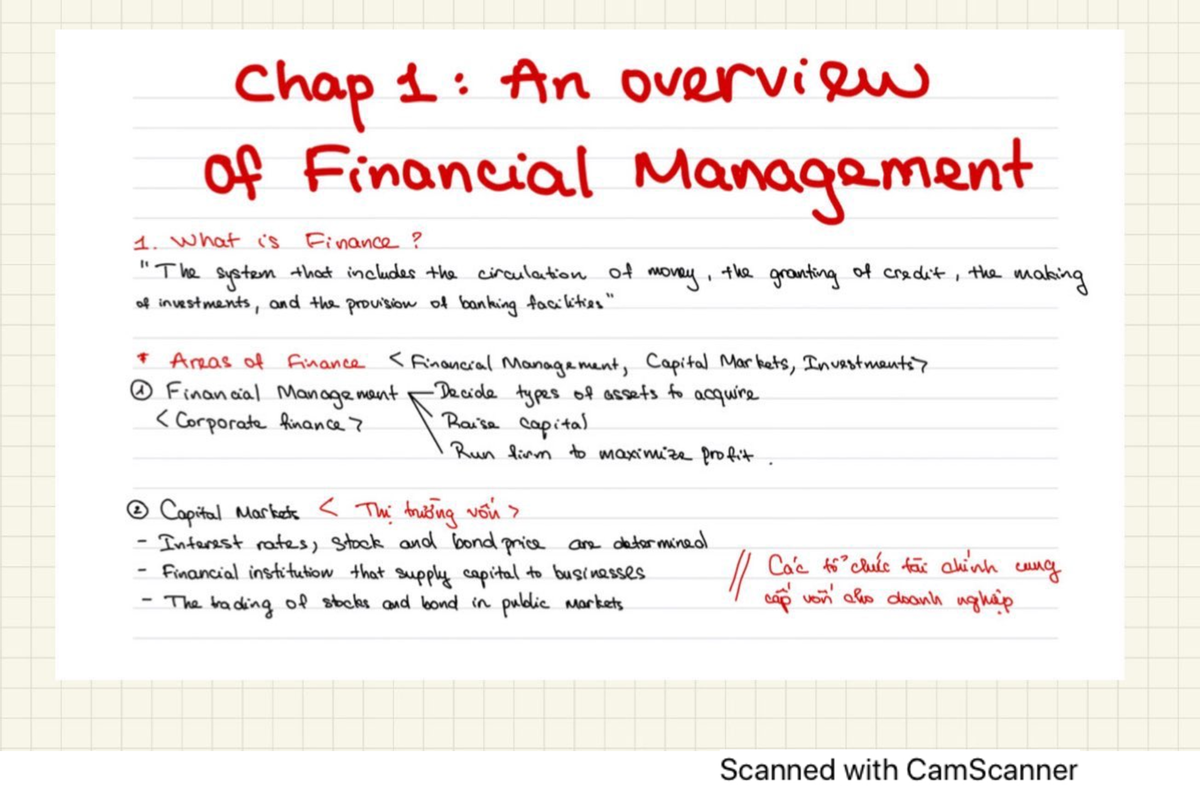
Commerce finance refers to the academic and operational discipline focused on how commercial enterprises raise, manage, and deploy monetary resources. Unlike personal finance, which centers on individual wealth accumulation and household budgeting, commerce finance is designed to maximize enterprise value, ensure systemic solvency, and optimize the return on invested capital for stakeholders.
At its foundational level, the discipline addresses three major financial decision categories:
- Capital Budgeting: Determining which long-term projects, equipment acquisitions, or market expansions justify the allocation of scarce financial resources.
- Capital Structure Management: Deciding the optimal balance between debt (borrowed capital) and equity (ownership shares) to fund operations while minimizing the cost of capital.
- Working Capital Management: Handling short-term assets and liabilities—such as accounts receivable, inventory, and accounts payable—to ensure the business maintains adequate liquidity for day-to-day operations.
The Pillars of Commercial Capital Structure
To understand how modern enterprises operate, one must examine how they fund their activities. The capital structure of a commercial entity determines its financial resilience during economic downturns and its agility when seizing new market opportunities.
Equity Financing
Equity financing involves raising capital by selling ownership stakes in the business, typically through common or preferred stock issuance in public markets, or through venture capital and private equity in private settings.
- Advantages: Equity capital does not require scheduled principal repayments or periodic interest charges, eliminating immediate debt-service pressure.
- Disadvantages: Founders and existing owners dilute their ownership percentages and voting control. Furthermore, equity investors typically expect a high return on investment via dividends or capital appreciation.
Debt Financing
Debt financing relies on borrowing funds from external creditors, such as commercial banks, bondholders, or alternative lenders, with a legally binding obligation to repay the principal alongside accrued interest over a specified timeframe.
- Advantages: Debt allows businesses to leverage existing assets to amplify returns without surrendering ownership equity. Interest payments are often tax-deductible under standard corporate tax codes.
- Disadvantages: Fixed debt-service obligations must be met regardless of monthly revenue fluctuations. High debt loads increase financial leverage risks, potentially leading to insolvency if cash flows contract sharply.
Managing Working Capital and Cash Flow
While long-term capital strategy shapes the trajectory of a company, working capital management dictates its daily survival. Cash flow timing often diverges from revenue recognition, making liquidity management paramount.
Working Capital Cycle Components:
- Inventory Acquisition -> Production/Holding -> Sales & Accounts Receivable
- Cash Outflow (Payables) <----------------- Cash Inflow (Collections)
The Cash Conversion Cycle (CCC)
The cash conversion cycle measures the time—in days—it takes for a company to convert its investments in inventory and other resources into cash inflows from sales. Shortening this cycle improves liquidity and reduces reliance on short-term borrowing. Key components include:
- Days Sales Outstanding (DSO): The average number of days it takes to collect receivables after a credit sale.
- Days Inventory Outstanding (DIO): The average number of days inventory sits on warehouse shelves before being sold.
- Days Payable Outstanding (DPO): The average number of days a company takes to pay its suppliers.
Short-Term Financing Options
When working capital gaps emerge due to seasonal sales dips or delayed customer payments, companies utilize short-term financial instruments:
- Trade Credit: Allowing delayed payment terms (e.g., Net 30 or Net 60 days) extended by suppliers.
- Lines of Credit: Flexible revolving credit facilities provided by financial institutions to smooth out cash flow volatility.
- Invoice Factoring: Selling accounts receivable to a third party at a discount to secure immediate cash.
Financial Risk Management in Commercial Operations
Commercial entities navigate a complex landscape of financial risks that can destabilize earnings and erode capital reserves. Comprehensive risk management strategies safeguard enterprise value against unexpected market shocks.
Market and Interest Rate Risk
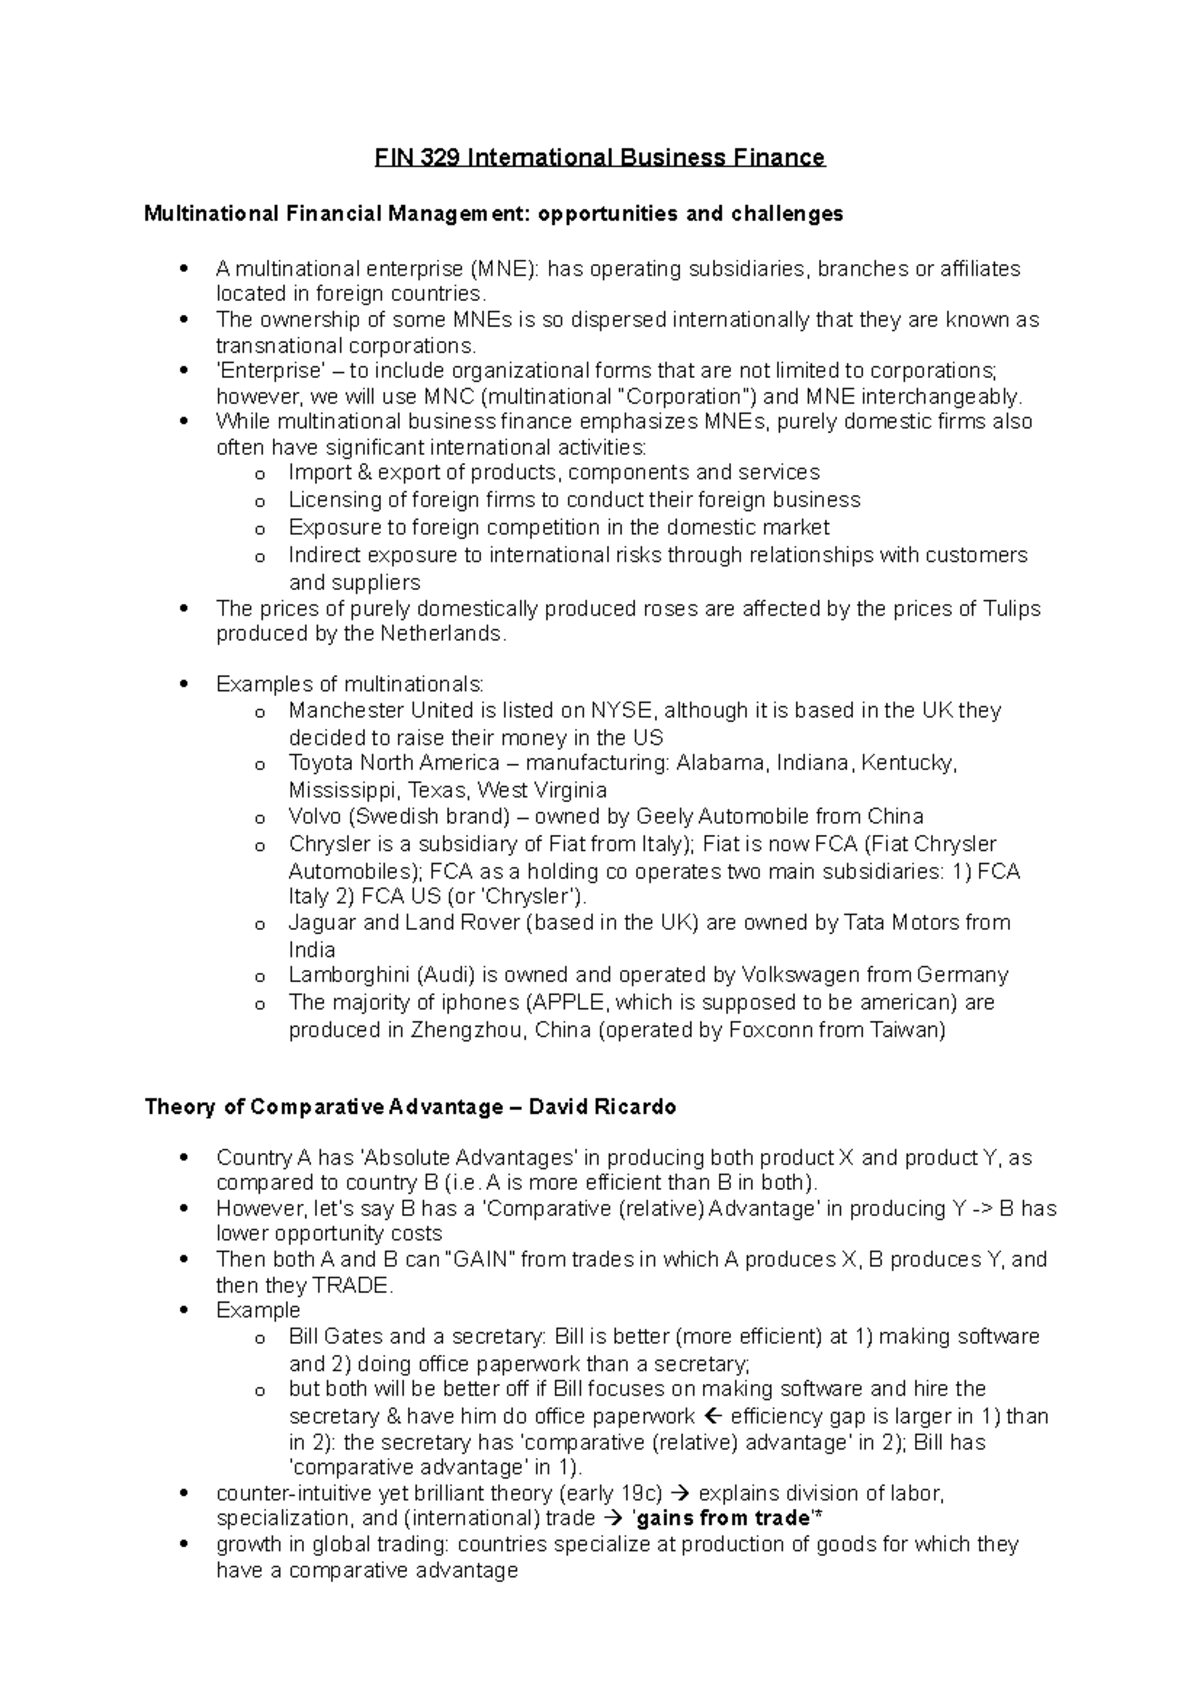
Fluctuations in foreign exchange rates, commodity prices, and benchmark interest rates directly impact profit margins. Enterprises utilize financial derivatives, such as futures contracts, options, and interest rate swaps, to lock in predictable pricing and hedge against adverse market movements.
Credit and Counterparty Risk
When businesses extend trade credit to customers or enter agreements with suppliers, they face the risk of default. Robust credit scoring models, credit insurance, and stringent collateral requirements help mitigate uncollectible accounts and counterparty failures.
Comparative Overview of Commercial Funding Instruments
Selecting the correct funding instrument depends on cost, maturity, control implications, and organizational scale. The following table contrasts primary commercial finance vehicles.
| Funding Instrument | Primary Purpose | Cost Profile | Control Impact | Typical Term |
|---|---|---|---|---|
| Commercial Bank Loan | Capital expansion, equipment | Moderate to High (Interest rates) | None (No equity dilution) | Medium-Term (3–7 years) |
| Corporate Bonds | Large-scale infrastructure, refinancing | Fixed Coupon Payments | None | Long-Term (5–30 years) |
| Venture Capital | High-growth startups, market entry | High (Implied equity return) | High (Board seats, dilution) | Long-Term Equity |
| Revolving Credit Line | Working capital, seasonal gaps | Variable Interest on drawn amounts | None | Short-Term (Renewable annually) |
| Trade Credit | Inventory acquisition | Implicit (Early payment discounts missed) | None | Very Short-Term (30–90 days) |
Frequently Asked Questions
What is the primary difference between commerce finance and personal finance?
Commerce finance focuses on maximizing enterprise value, managing capital structures, and optimizing commercial returns for stakeholders. Personal finance centers on individual or household budgeting, retirement planning, and wealth preservation.
How do rising interest rates affect commercial financing?
Rising interest rates increase the cost of variable-rate debt and new bond issuances, elevating corporate interest expenses. This compression in net margins often prompts companies to rely more heavily on internal cash generation or equity financing rather than new debt.
What constitutes a healthy working capital ratio?
A current ratio (current assets divided by current liabilities) between 1.2 and 2.0 is generally considered healthy for most commercial enterprises. However, optimal ratios vary significantly by industry sector, depending on inventory turnover and receivables norms.
How does supply chain finance improve cash flow?
Supply chain finance programs leverage credit ratings of creditworthy buyers to help suppliers secure early invoice payments at lower discount rates. This practice extends payment terms for the buyer while providing immediate liquidity to the supplier.
What is the weighted average cost of capital (WACC)?
WACC represents a firm's average cost of capital from all funding sources, including common stock, bonds, and other debts. Companies use WACC as a benchmark hurdle rate for evaluating new capital budgeting projects and investments.
Strategic Next Actions for Financial Management
To strengthen financial operations, organizations should conduct a comprehensive audit of their current capital structure and cash conversion cycle. Finance leaders must align short-term liquidity safeguards with long-term capital allocation goals, establishing rigorous variance reporting to monitor operational performance against strategic forecasts.
Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
