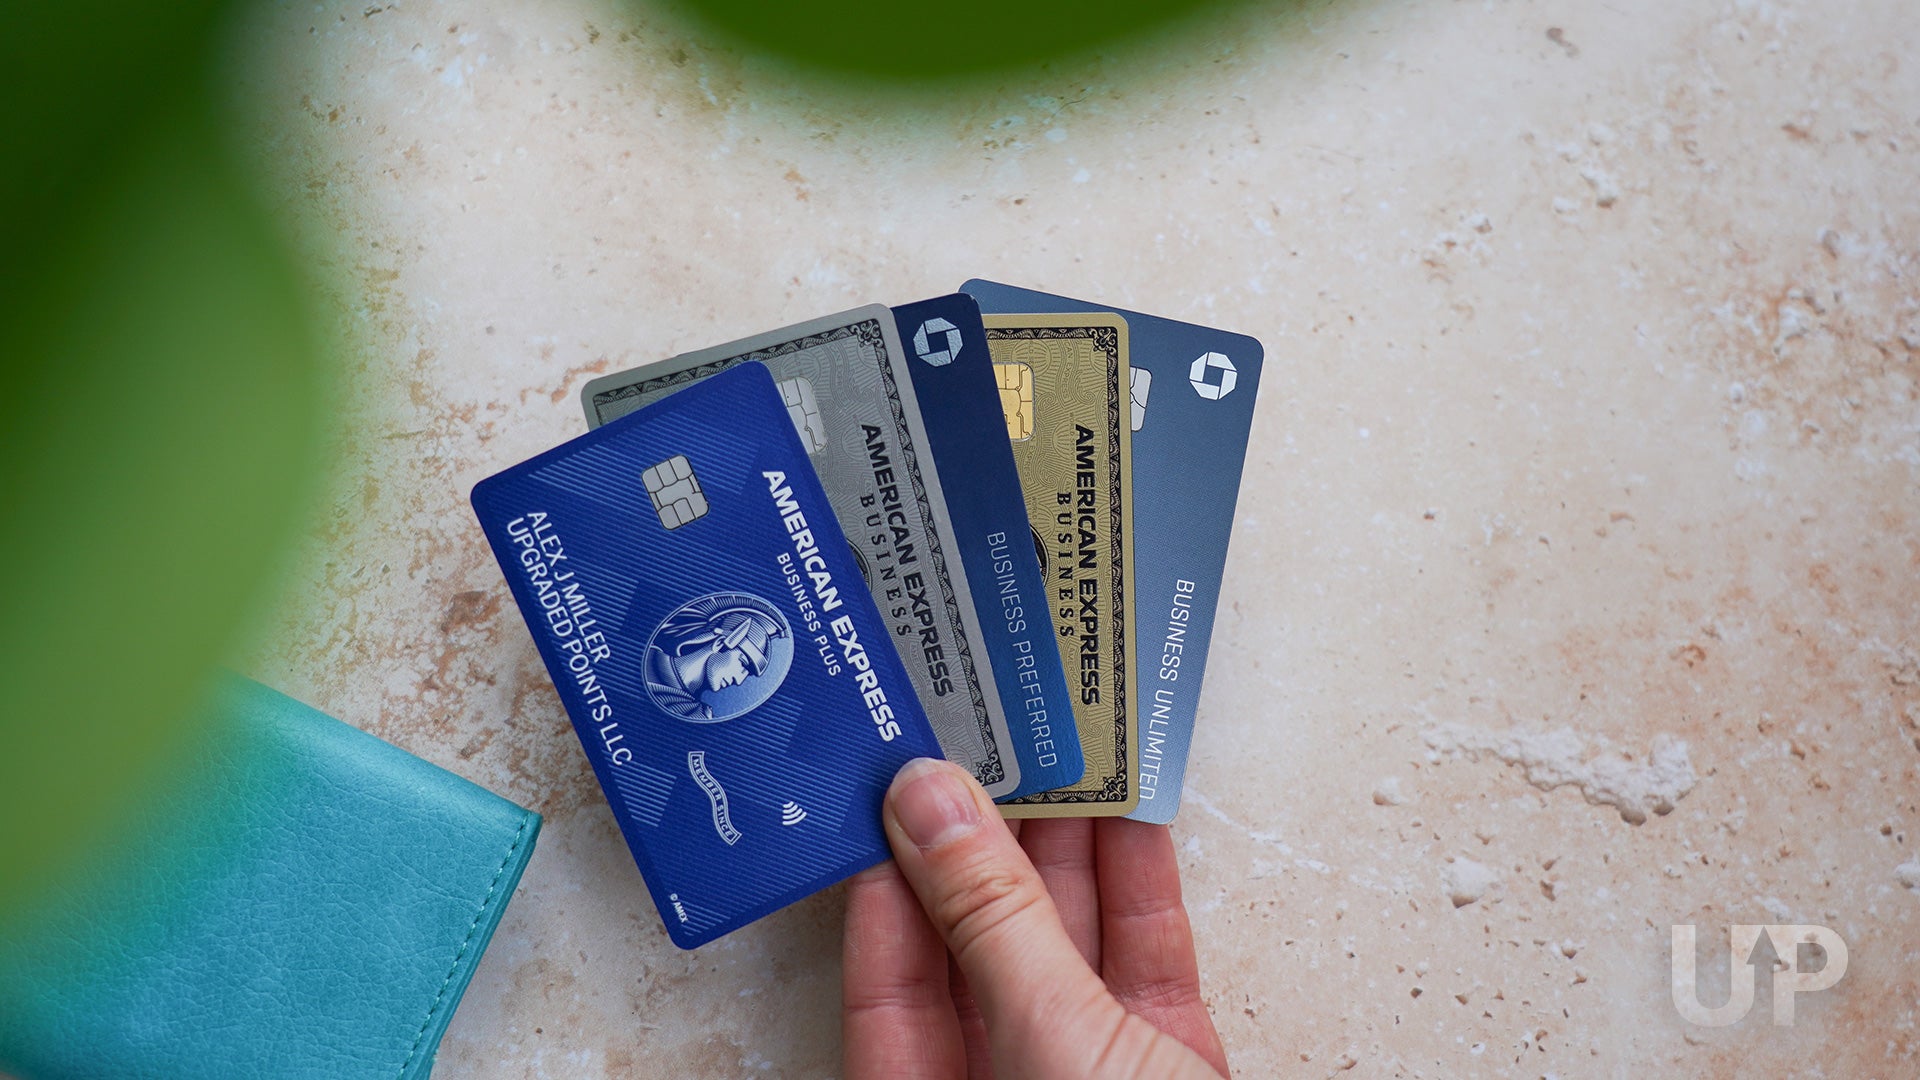
Choosing the best credit card for your business depends on your specific spending patterns, company size, and financial goals. For maximum value in 2026, the American Express Business Platinum Card remains the premier choice for frequent travelers, while the Chase Ink Business Preferred offers the best versatility for general high-growth expenditures.
Selecting the right financial instrument is no longer just about revolving credit; it is about integrating your accounts payable with rewards systems that fuel your company’s bottom line. In the current economic landscape of 2026, business credit cards have evolved into sophisticated spend-management platforms. They offer not only capital but also deep analytical insights, automated expense reporting, and tiered rewards that can offset significant operational costs.
The Evolution of Business Credit in 2026
The business credit card market has shifted significantly over the last few years. While traditional rewards like cashback and travel points remain staples, the "best" cards in 2026 are defined by their ability to integrate with Enterprise Resource Planning (ERP) software and provide real-time visibility into employee spending. For a business owner, the card in your wallet is now a tool for both liquidity and data management.
Financial institutions have responded to a more volatile interest rate environment by diversifying their offerings. We see a sharper divide between "charge cards," which require payment in full each month but offer massive purchasing power, and traditional "credit cards" that allow for carrying a balance at competitive APRs. Understanding which structure fits your cash flow is the first step in making an informed decision.
Top Business Credit Card Picks for 2026
1. Best for Luxury Travel: The Business Platinum Card® from American Express
For the business owner who spends a significant portion of their time in the air or at international conferences, this card remains the gold standard. As of 2026, the card has expanded its "Business Suite" of credits, making the high annual fee easier to justify for established firms.
- Rewards Structure: Earns 5x Membership Rewards® points on flights and prepaid hotels booked through AmexTravel.com. It also offers 1.5x points on large purchases (over $5,000) and in specific business categories.
- Key Perks: Access to the American Express Global Lounge Collection, which includes Centurion Lounges, Delta Sky Clubs, and Priority Pass locations. In 2026, the card’s digital tech credits have been updated to include more AI-driven productivity tools.
- Suitability: Best for high-revenue businesses with significant travel budgets and a need for high-limit "No Preset Spend Limit" capacity.
2. Best for High-Growth Versatility: Chase Ink Business Preferred® Credit Card
Chase has maintained its dominance in 2026 by offering a balanced rewards ecosystem. The "Ink" ecosystem allows business owners to pool points from multiple cards, maximizing the value of every dollar spent on infrastructure and marketing.
- Rewards Structure: Earn 3 points per $1 on the first $150,000 spent in combined categories including shipping, social media advertising, internet, cable, phone services, and travel.
- Point Valuation: Points are worth 25% more when redeemed for travel through Chase Travel℠. In 2026, the transfer partners remain some of the most valuable in the industry, including major international airlines and hotel chains.
- Suitability: Ideal for digital agencies, e-commerce brands, and startups that spend heavily on online advertising and logistics.
3. Best for Simple Cashback: Capital One Spark Cash Plus
Not every business owner wants to manage complex point systems. For those who prioritize liquidity and straightforward accounting, the Spark Cash Plus offers a "pay-in-full" model with an industry-leading flat rate.
- Rewards Structure: A consistent 2% cashback on every purchase, with no limits or category restrictions.
- Operational Benefits: As a charge card, it offers no preset spending limit, which is vital for businesses that need to make sudden, large inventory purchases without hitting a hard credit ceiling.
- Suitability: Best for professional services (lawyers, accountants) and contractors who have high, predictable monthly overhead and prefer cash back to travel perks.
4. Best for Startups and No Personal Guarantee: Brex Card
Brex continues to disrupt the space in 2026 by offering credit based on a company’s cash balance and backing rather than the owner’s personal credit score. This is a critical distinction for founders who want to separate their personal and professional liabilities completely.
- Rewards Structure: Scaled rewards for technology startups, including high multiples on rideshare, travel, and recurring software subscriptions (SaaS).
- The Brex Advantage: No personal guarantee is required for venture-backed or high-cash-reserve companies. The platform includes built-in expense management software that rivals standalone paid products.
- Suitability: Specifically designed for venture-backed startups and larger mid-market companies looking to automate their entire accounts payable process.
Key Features Comparison for 2026
| Card Name | Primary Reward Type | Annual Fee (2026) | Best Use Case |
|---|---|---|---|
| Amex Business Platinum | Membership Rewards Points | $695 | Frequent International Travel |
| Chase Ink Preferred | Ultimate Rewards Points | $95 | Marketing & Shipping Spend |
| Capital One Spark Cash Plus | Flat-rate Cashback | $150 | General Business Expenses |
| Brex Card | Brex Points | $0 | Tech Startups & Scalability |
| Blue Business Plus (Amex) | Points (2x up to $50k) | $0 | Small/Side Businesses |
Understanding Liability and the Personal Guarantee
One of the most misunderstood aspects of business credit cards is the personal guarantee. For most small business cards, the owner is personally liable for the debt if the business fails to pay. This means that a default can affect your personal credit score and assets.
In 2026, lenders have become more stringent with credit box requirements. However, "corporate liability" cards—which do not require a personal guarantee—are becoming more accessible to mid-sized companies with over $1 million in annual revenue or significant venture funding. When selecting a card, you must decide if the rewards of a small business card outweigh the risk of personal liability, or if your company's financials are strong enough to qualify for a true corporate card.
Integrating Credit into Your Financial Workflow
Modern business owners do not just use credit cards for the points; they use them to streamline operations. The best cards in 2026 offer:
- Direct ERP Sync: Seamless integration with QuickBooks, Xero, and NetSuite. This reduces the manual labor required for monthly reconciliations.
- Virtual Cards: The ability to issue unique, virtual card numbers for specific vendors. This enhances security and allows you to set hard spending limits on individual subscriptions.
- Employee Cards with Controls: You can set individual spending limits for employees, limiting their purchases to specific categories (e.g., only fuel or only office supplies).
- AI-Powered Insights: Many card issuers now provide monthly reports that use AI to identify duplicate subscriptions or suggest ways to optimize spending.
Tax Implications and Financial Management
While rewards and cashback are a significant "plus," they are generally not considered taxable income by the IRS; rather, they are treated as a reduction in the cost of the purchase. However, it is essential to maintain a strict separation between personal and business expenses. Using a dedicated business credit card is the most effective way to "pierce the corporate veil" and protect your personal assets in the event of a legal dispute or audit.
Note: For specific tax advice regarding your business structure, consult with a qualified CPA or tax professional. Financial regulations can vary by jurisdiction and business type.
Common Mistakes When Choosing a Business Card
Even the "best" card can become a liability if used incorrectly. Avoid these frequent errors:
- Ignoring the APR on Carrying Balances: If your business needs to carry a balance month-to-month, a rewards card is often the wrong choice due to high interest rates. Look for a low-APR business card instead.
- Underestimating the Value of Transfer Partners: 50,000 points might be worth $500 in cash but could be worth $1,200 when transferred to a high-value airline partner for a business-class seat.
- Missing the Spend Thresholds: Many of the best cards in 2026 offer massive sign-up bonuses, but they require spending $10,000 to $30,000 within the first three months. Ensure your organic spending meets these requirements before applying.
Frequently Asked Questions
Can I get a business credit card as a freelancer or sole proprietor?
Yes. In 2026, the "gig economy" is a major segment of the market. You can apply for most business credit cards using your Social Security Number (SSN) as a sole proprietor. You do not necessarily need a formal LLC or an EIN (Employer Identification Number), though having them can help build a dedicated business credit profile.
Do business credit cards affect my personal credit score?
Most issuers require a personal guarantee, which involves a hard pull on your personal credit during the application. While many business cards do not report monthly activity to personal credit bureaus (unless you default), some issuers, like Capital One and Discover, may report all activity. This can affect your debt-to-income ratio even if you pay in full.
What is the difference between a business credit card and a corporate card?
A business credit card is typically issued to small-to-medium businesses and requires a personal guarantee from the owner. A corporate card is designed for larger companies, usually with millions in revenue, and the company—not the individual—is liable for the charges. Corporate cards often have different fee structures and integrated expense management systems.
Are the annual fees on business credit cards tax-deductible?
In many cases, yes. Because the card is used exclusively for business purposes, the annual fee is generally considered an ordinary and necessary business expense, making it deductible. Always verify this with your tax preparer based on your specific situation.
How do I choose between cashback and travel points?
If your business expenses are mostly "un-categorized" (utilities, rent, inventory), a flat-rate cashback card is usually more profitable. If you spend heavily in specific categories like airfare or online advertising, a tiered points card will likely provide a higher "return on spend."
Practical Recommendation for Business Owners
For the year 2026, our recommendation is to follow a multi-card strategy. Use the Chase Ink Business Preferred for your primary digital spend (advertising and shipping) to capture the 3x points multiplier. Pair this with a Capital One Spark Cash Plus for all other miscellaneous expenses to ensure a floor of 2% cashback. Finally, if you travel more than three times a year for business, the Amex Business Platinum pays for itself through its travel credits and lounge access, serving as your primary card for bookings.
By diversifying your card portfolio, you ensure that no dollar of business spending goes unrewarded while maintaining the flexible credit lines necessary for modern business operations.
Image Gallery
Select an image to open it in a new tab.



Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
