RV insurance for auto owners provides specialized financial protection for motorized motorhomes and towable campers, bridging the critical coverage gaps left by standard personal auto insurance policies. While auto insurance liability may extend to towed trailers in transit, it fails to cover physical damage, campsite premises liability, or personal contents. Securing dedicated RV coverage—often bundled with an existing auto policy—ensures comprehensive protection against collision, theft, weather damage, and liability risks across all 50 states.
Understanding RV Insurance: How It Differs from Standard Auto Policies
Many vehicle owners naturally assume that their standard personal auto insurance policy automatically covers a recreational vehicle (RV). While there is minor overlap in liability when towing a trailer, standard car insurance is fundamentally inadequate for protecting an RV. Cars are primarily designed to transport people from point A to point B. Recreational vehicles, by contrast, serve dual purposes: they function as motor vehicles on the highway and as temporary or permanent living quarters when parked.
Because an RV acts as a home on wheels, the insurance risks associated with it extend far beyond typical traffic accidents. RV ownership introduces risks such as interior plumbing leaks, awnings tearing in strong wind gusts, campsite visitor injuries, fire hazards from propane appliances, and high-value personal belongings being stolen while parked at a state park or private campground.
- Standard Auto Policy
- Covers driving liability & physical damage for passenger cars
- Extends limited liability to towed trailers (in motion only)
- NO coverage for contents, parked liability, living expenses
- Dedicated RV Policy
- Motorized (Class A/B/C): Full auto liability + physical damage
- Towables: Comprehensive & Collision for the rig itself
- Campsite Liability (Premises Liability when parked)
- Personal Property / Belongings replacement
- Emergency Expense & Vacation Interruption coverage
Towable RVs vs. Motorized RVs
Understanding the distinction between motorized and towable RVs is essential when establishing appropriate policy structures with insurance carriers like Auto-Owners Insurance, Progressive, or State Farm:
- Motorized RVs (Class A, Class B, and Class C): Because motorhomes move under their own power, state motor vehicle laws mandate that they carry primary auto liability coverage (Bodily Injury and Property Damage). In addition to state-mandated liability, motorized RV policies include Collision, Comprehensive, Uninsured/Underinsured Motorist protection, and Medical Payments.
- Towable RVs (Travel Trailers, Fifth Wheels, Toy Haulers, Pop-Up Campers): Because towables lack an engine, liability coverage typically transfers from the tow vehicle’s auto insurance policy while the trailer is hitched and being driven on public roads. However, the tow vehicle’s insurance does not cover physical damage to the trailer itself, nor does it provide liability protection once the trailer is unhitched at a campsite. A dedicated RV policy is required to protect the physical structure of the towable rig.
Why Auto Insurance Alone Isn't Enough
Relying solely on a personal auto policy leaves severe gaps in financial protection. Standard car policies specifically exclude:
- Permanent or Portable Contents: Standard auto insurance provides minimal or zero coverage for clothing, electronics, outdoor gear, generator equipment, and kitchenware stored inside an RV.
- Premises/Campsite Liability: If a guest slips on your RV steps or trips over your awning guy-lines while visiting your campsite, your auto insurance policy will reject the claim because the vehicle was not in motion on a public roadway.
- Attached Accessories: Built-in awnings, solar panel arrays, satellite dishes, exterior kitchens, and leveling jack systems are rarely compensated adequately under standard vehicle policies.
- Loss of Use and Emergency Expenses: If an accident renders your RV uninhabitable while you are hundreds of miles from home, personal auto insurance will not pay for hotel stays, temporary transportation, or food costs.
Auto-Owners Insurance RV Coverage Options & Features
For policyholders insured through Auto-Owners Insurance—a premier regional mutual insurer operating across 26 states through independent agencies—or similar top-tier regional carriers, adding RV coverage to an existing personal auto account is straightforward and highly customizable. Auto-Owners offers robust endorsements specifically tailored for both weekend campers and full-time RVers.
- Auto-Owners RV Coverage
- Primary Liability
- BI/PD
- UM/UIM
- MedPay
- Physical Damage Valuation
- Actual Cash
- Agreed Value
- Total Loss
- Specialized Endorsements
- Vacation Liab.
- Personal Eff.
- Roadside Assist
- Full-Time Endorsement
- Sub. Home
- Med Pay
- Personal Liab.
- Primary Liability
Core Liability and Property Damage Coverages
Auto-Owners and major national insurers structure core RV insurance around essential vehicle protections:
- Bodily Injury and Property Damage Liability: Pays for medical bills, lost wages, legal defense fees, and property damage suffered by third parties if you cause an accident in a motorized RV.
- Collision Coverage: Pays to repair or replace your RV following a traffic crash, rollover, or collision with another vehicle or object, regardless of fault.
- Comprehensive Coverage: Covers non-collision physical damage caused by hail, windstorms, fallen tree branches, fire, theft, vandalism, animal strikes, or glass breakage.
Specialized Coverage Add-Ons
To bridge the gap between automobile coverage and home insurance, insurers offer specialized RV endorsements:
- Vacation Liability (Campsite Liability): Functions like temporary homeowners liability insurance. It protects you financially if a non-family member is injured in or around your parked RV while it is being used for recreational temporary living. Standard policy limits usually start at $100,000 and can be increased to $500,000 or higher.
- Personal Effects Protection: Reimburses you for replacement costs of personal property inside the RV—including laptops, camping gear, cookware, bedding, and apparel—lost to theft, fire, or covered accidents.
- Total Loss Replacement vs. Actual Cash Value (ACV):
- Actual Cash Value (ACV): Pays the depreciated market value of the RV at the time of loss.
- Agreed Value: Pays an agreed-upon dollar figure set when the policy was written, ideal for custom camper van conversions or vintage restoration rigs.
- Total Loss Replacement: Replaces an unrepairable RV with a brand-new, current-model-year equivalent if the loss occurs within the first few years of manufacture (typically 1 to 5 model years).
- Emergency Roadside Assistance: Provides 24/7 towing, battery jump-starts, flat-tire changes, fuel delivery, and lockout assistance. Because RVs require specialized heavy-duty tow trucks and flatbed transporters, standard auto roadside coverage is usually insufficient; dedicated RV roadside protection ensures proper equipment responds.
Full-Timer Insurance vs. Recreational Use Policies
Insurers clearly delineate between recreational RV use (e.g., camping 30 to 60 days per year) and Full-Timer Coverage (using the RV as a primary residence for 150 to 180+ days consecutive per year).
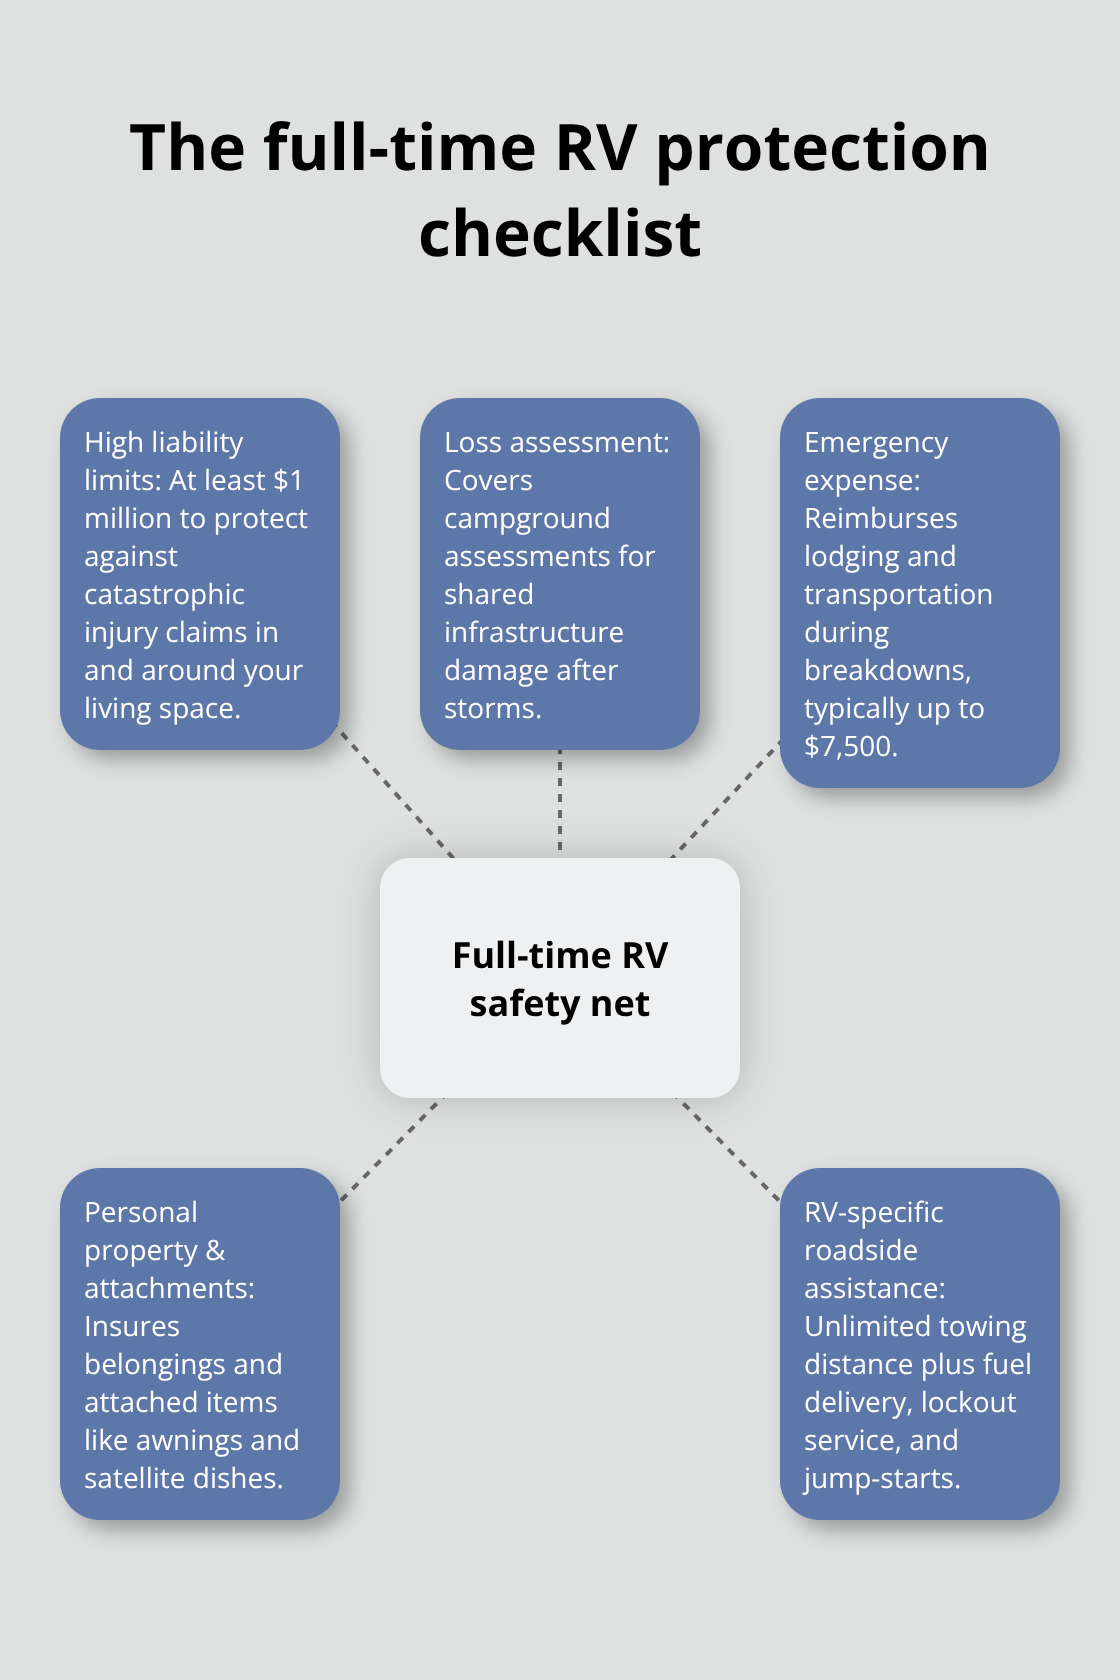
If you live in your RV full-time, standard recreational insurance will deny claims arising from long-term residency risks. A Full-Timer Endorsement replaces vacation liability with continuous personal liability protection (similar to a primary Homeowners liability policy), includes medical payments for guests, adds coverage for stored belongings in external storage sheds, and provides loss-of-use living expenses if your home on wheels undergoes repairs.
Benefits of Bundling RV Insurance with Your Auto Policy
Consolidating your motorhome or travel trailer policy with the same carrier that insures your personal cars (such as Auto-Owners Insurance) provides substantial financial and operational benefits.
- Existing Auto Policy Account
- Add RV Item
- Multi-Policy / Multi-Vehicle Discounts (5-20%)
- Single Deductible Claim Event (Single Incident)
- Consolidated Administration (One App / Bill)
- Add RV Item
Multi-Policy and Multi-Vehicle Discounts
Insurance companies reward account retention. Bundling auto and RV insurance under one carrier yields immediate cost savings through overlapping discount structures:
- Multi-Vehicle Discount: Applies when adding a motorized RV or travel trailer to an existing private passenger auto account.
- Multi-Policy Discount: Applies when you combine Auto, RV, Homeowners, or Life insurance with the same carrier (e.g., Auto-Owners' popular Life-Multi-Policy or Home/Auto/RV package discounts).
- Claims-Free Discounts: Carrying over an established history of safe driving from your auto policy can instantly qualify you for lower tier pricing on your new RV policy.
Overall, bundling RV insurance with your primary auto carrier typically reduces combined premium costs by 5% to 20% annually compared to purchasing standalone policies from separate specialty insurers.
Simplified Deductibles and Claim Procedures
A key technical advantage of maintaining auto and RV coverage under one insurer emerges during joint-vehicle incidents.
Scenario: A falling tree limb damages both your parked commuter car and your travel trailer parked in your home driveway. Alternatively, an accident on the highway involves damage to both your tow vehicle (truck) and your towed fifth-wheel trailer.
When both vehicles are insured through the same carrier under a unified account structure, insurers frequently offer a Single Deductible Endorsement. Instead of paying two separate deductibles ($500 for the truck + $500 for the trailer), the insurer waives the lower deductible or applies only one deductible toward the entire loss event. Additionally, claims handling is managed by a single adjuster team, eliminating multi-carrier disputes regarding fault allocation or boundary liability.
RV Insurance Cost Breakdown & Factors Influencing Premiums
RV insurance costs vary dramatically based on the vehicle type, size, value, usage frequency, and driver risk profile. A lightweight pop-up camper might cost under $200 per year to insure, whereas a luxury Class A diesel pusher motorhome valued at $400,000 can cost several thousand dollars annually.
Key Pricing Variables
- RV Classification & Value: Motorhomes cost significantly more to insure than towable trailers due to motorized mechanical risk, weight, and crash severity potential.
- Driving & Claims Record: Clean driving records on your primary auto policy directly lower RV liability premiums. Moving violations or DUI convictions on your auto record will elevate RV insurance rates.
- Usage Type: Seasonal/recreational use carries lower rates than full-time residency coverage.
- Storage Location & Safety Measures: Garaged or secured storage facility parking lowers rates compared to street parking in urban areas subject to vandalism or hail exposure.
- Deductible Selection: Higher deductibles (e.g., $1,000 or $2,500) substantially lower the annual physical damage (Collision/Comprehensive) premium components.
Insurance Comparison by RV Class & Coverage Integration
The following table summarizes typical policy structures, coverage integration with personal auto insurance, key features, and estimated annual premium ranges based on standard industry metrics for recreational use.
| RV Type / Class | Auto Policy Integration | Primary Coverage Included | Essential Add-Ons / Endorsements | Estimated Annual Premium Range |
|---|---|---|---|---|
| Pop-Up Camper | Tow vehicle liability extends on-road; Physical damage requires separate RV line. | Comprehensive, Collision | Personal effects, Storm/Hail damage | $125 – $350 |
| Travel Trailer | Tow vehicle liability extends on-road; Trailer physical damage requires separate RV line. | Comprehensive, Collision | Vacation liability, Emergency roadside, Personal property | $250 – $700 |
| Fifth-Wheel Trailer | Tow vehicle liability extends on-road; Physical damage requires separate RV line. | Comprehensive, Collision | Total loss replacement, Vacation liability, Cargo coverage | $400 – $1,100 |
| Class B Motorhome (Camper Van) | Separate motorized RV policy; Qualifies for multi-vehicle auto bundle. | Bodily Injury/PD Liability, Collision, Comprehensive | Custom equipment coverage, Roadside assistance, Medical payments | $600 – $1,500 |
| Class C Motorhome (Cab-Over) | Separate motorized RV policy; Qualifies for multi-vehicle auto bundle. | Bodily Injury/PD Liability, Collision, Comprehensive | Personal effects, Vacation liability, Emergency expenses | $800 – $1,800 |
| Class A Motorhome (Bus / Diesel Pusher) | Separate motorized RV policy; Qualifies for multi-vehicle auto bundle. | Bodily Injury/PD Liability, Collision, Comprehensive | Total loss replacement, Full-Timer endorsement, High-limit vacation liability | $1,200 – $4,000+ |
Note: Premium ranges are estimated for 2026 baseline rates for recreational users with clean driving records. Actual quotes vary based on location, state regulations, driver history, deductible choices, and carrier discounts.
Step-by-Step Guide to Adding RV Coverage to an Existing Auto Account
Adding an RV to your existing auto policy account—whether dealing directly with an independent agent from Auto-Owners Insurance or another regional/national insurance company—involves a clear, systematic process.
- Step 1: Gather RV Documents & Details
- VIN, Make, Model, Year, Bill of Sale, Hitch Specs, Upgrades List
- Step 2: Declare Usage & Residency Type
- Select Recreational (Seasonal/Weekend) vs. Full-Timer (150+ days/yr)
- Step 3: Choose Loss Settlement Method
- Actual Cash Value (ACV) vs. Agreed Value vs. Total Loss Replacement
- Step 4: Select Endorsements & Apply Bundle Discounts
- Add Campsite Liab., Personal Effects, Towing; Verify Multi-Policy Rate
- Step 5: Review Proof of Insurance & Buster Lease Requirements
- Issue Binder to Lienholder (if financed) and Store ID Card in RV
Step 1: Gather Required RV Documentation
Before requesting a quote, collect essential information regarding your recreational vehicle:
- Vehicle Identification Number (VIN) or Serial Number.
- Year, Make, Model, Length, and Floorplan edition.
- Purchase Price / Bill of Sale (and detailed receipts for custom conversions or aftermarket accessories like solar power systems or hydraulic levelers).
- For towables: Vehicle specs of the primary towing vehicle (to confirm towing capacity compliance).
Step 2: Establish Primary Usage Profile
Clearly define how you intend to use the RV. Declare whether the vehicle will be stored at your primary residence, a secure storage yard, or parked permanently at a seasonal campsite. State whether usage will be purely recreational (e.g., 20 to 40 days of annual vacation) or full-time living.
Step 3: Select Physical Damage Loss Valuation
Decide how total losses will be calculated in the event of a severe crash or theft:
- Opt for Total Loss Replacement if purchasing a new motorhome or trailer (protects against rapid early depreciation).
- Select Agreed Value for custom vintage rigs or high-end camper van conversions where market guides (such as J.D. Power / NADA Guides) understate true value.
- Select Actual Cash Value (ACV) for older, standard production trailers where minimizing monthly premiums is the main goal.
Step 4: Audit Endorsements and Maximize Discounts
Ensure the insurance representative incorporates all applicable discount structures:
- Confirm Multi-Vehicle or Multi-Policy discounts are linked to your existing private passenger auto account.
- Ask about Seasonal Storage Discounts (also called lay-up options), which allow you to temporarily suspend Collision and Roadside coverage during winter months when the RV is winterized and stored, retaining only Comprehensive coverage for theft and storm protection.
- Add specialized endorsements including Campsite/Vacation Liability and Personal Effects coverage.
Step 5: Issue Binder and Secure Documentation
If your RV is financed through a credit union or bank, the lender will require proof of comprehensive and collision coverage (usually requiring a maximum deductible of $500 or $1,000) before releasing funds. Have your agent send an insurance binder directly to the lender, and place paper and digital copies of your RV insurance ID card inside the RV glove compartment or document holder.
Common Pitfalls and Mistakes to Avoid When Insuring an RV
Securing adequate coverage requires avoiding common insurance mistakes that can lead to rejected claims or severe out-of-pocket expenses:
- Assuming the Tow Vehicle Auto Policy Covers Trailer Damage: This is the single most frequent mistake made by travel trailer owners. While liability transfers while driving, physical damage to the trailer itself is zero unless a dedicated endorsement or RV policy is activated.
- Underreporting Personal Effects Values: Owners frequently undercount the total value of clothing, cookware, outdoor power gear, bicycles, and electronics packed in their rig. Conduct a inventory audit with photos and receipts to set appropriate endorsement limits.
- Failing to Disclose Full-Time Usage: Misrepresenting a full-time residential RV lifestyle as "recreational camping" to lower premiums constitutes material misrepresentation. If a claim occurs, the insurer can rescind the policy and deny liability protection entirely.
- Neglecting Weight and Towing Limits: Operating an RV or towing a trailer that exceeds the tow vehicle's Gross Vehicle Weight Rating (GVWR) can compromise vehicle safety. In extreme cases involving gross negligence, insurers may investigate structural overload when settling high-dollar liability claims.
- Forgetting Storage-Period Coverage: Suspending all coverage during winter storage leaves your RV unprotected against roof collapses from heavy snow, falling branches, fire, rodent damage, or theft from storage yards. Always maintain active Comprehensive (Other-Than-Collision) coverage year-round.
Frequently Asked Questions
Does my personal auto insurance cover a travel trailer while driving?
Yes, but only for third-party liability. Your primary auto insurance policy's Bodily Injury and Property Damage liability typically extends to a towed trailer while attached to your vehicle. However, standard auto insurance will not pay for physical damage to your trailer if you crash, nor will it cover theft, fire damage, storm damage, or personal property stored inside. Dedicated RV coverage is necessary to protect the trailer structure itself.
Can I insure my RV on the same policy as my cars with Auto-Owners Insurance?
Auto-Owners Insurance allows policyholders to bundle recreational vehicles alongside their personal private passenger vehicles under a unified personal lines account structure. Motorized RVs and towable trailers can be added via dedicated vehicle schedules or linked policies, unlocking multi-vehicle and multi-policy discounts across your account.
What is Vacation Liability coverage, and do I need it?
Vacation Liability (also called Campsite Liability) pays for medical expenses and legal defense costs if a guest is injured inside your RV or within your designated campsite perimeter while the vehicle is parked and used as temporary living quarters. Standard auto policies do not cover parked premises liability, making this endorsement essential for recreational RV owners.
What happens if I live in my RV full-time?
If you live in your RV full-time (typically defined as more than 150 to 180 days per year without a permanent physical home structure), standard recreational insurance policies will not cover your risks. You must purchase a Full-Timer Endorsement, which provides continuous personal liability coverage (equivalent to Homeowners liability), guest medical payments, and personal property protections tailored for primary residences.
How does a seasonal storage option save money on RV insurance?
A seasonal storage option (or lay-up period) allows you to temporarily suspend driving-related coverages—such as Collision and Roadside Assistance—during months when your RV is parked in winter storage. You retain Comprehensive coverage to protect against fire, theft, falling trees, and weather damage while significantly reducing your premium during inactive months.
Practical Recommendation & Next Actions
If you currently own auto insurance and are purchasing or currently operating an RV, take these immediate steps to ensure complete coverage:
- Perform a Policy Audit: Review your existing car insurance policy declarations page to verify whether trailer physical damage or motorized RV endorsements are present.
- Contact Your Independent Agent: If insured through Auto-Owners Insurance or a similar regional carrier, contact your local independent insurance agent. Request a consolidated quote that applies Multi-Vehicle and Multi-Policy discounts to your existing account.
- Conduct a Contents Inventory: Create a written and photographic inventory of all personal belongings stored inside your RV to ensure your Personal Effects endorsement limit is set accurately.
- Select the Right Loss Settlement: For new rigs under five years old, elect Total Loss Replacement. For older or custom rigs, verify whether an Agreed Value appraisal is appropriate to protect your capital investment.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
