
When people search for a "prepay life insurance policy," they are typically looking to understand how they can pay off a permanent life insurance policy faster, eliminate future premium payments entirely, or fund a policy in advance using a lump sum. This financial strategy allows policyholders to accelerate cash value growth, secure lifelong coverage without ongoing monthly bills, and potentially maximize legacy wealth, though it requires careful navigation of tax regulations and insurer rules.
Defining the Concept of Prepaying Life Insurance
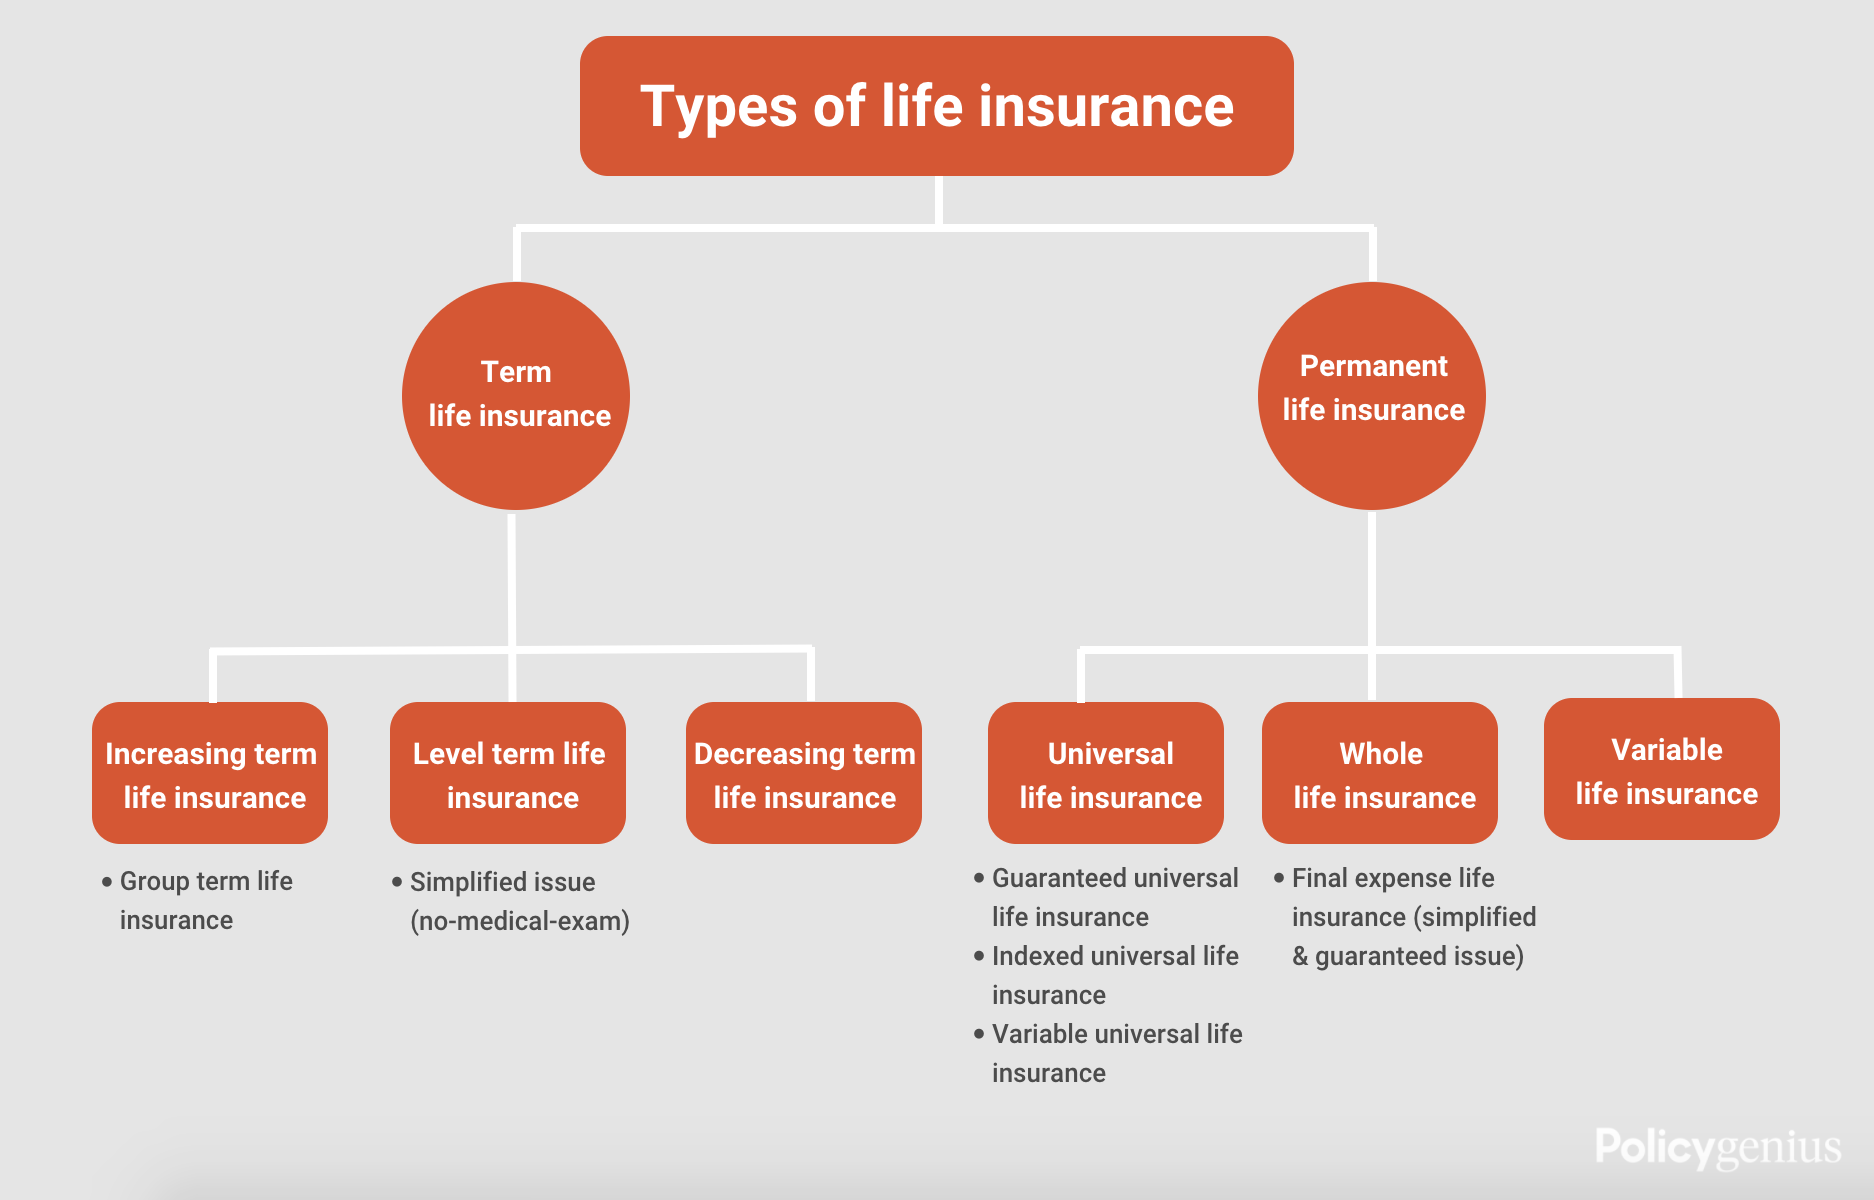
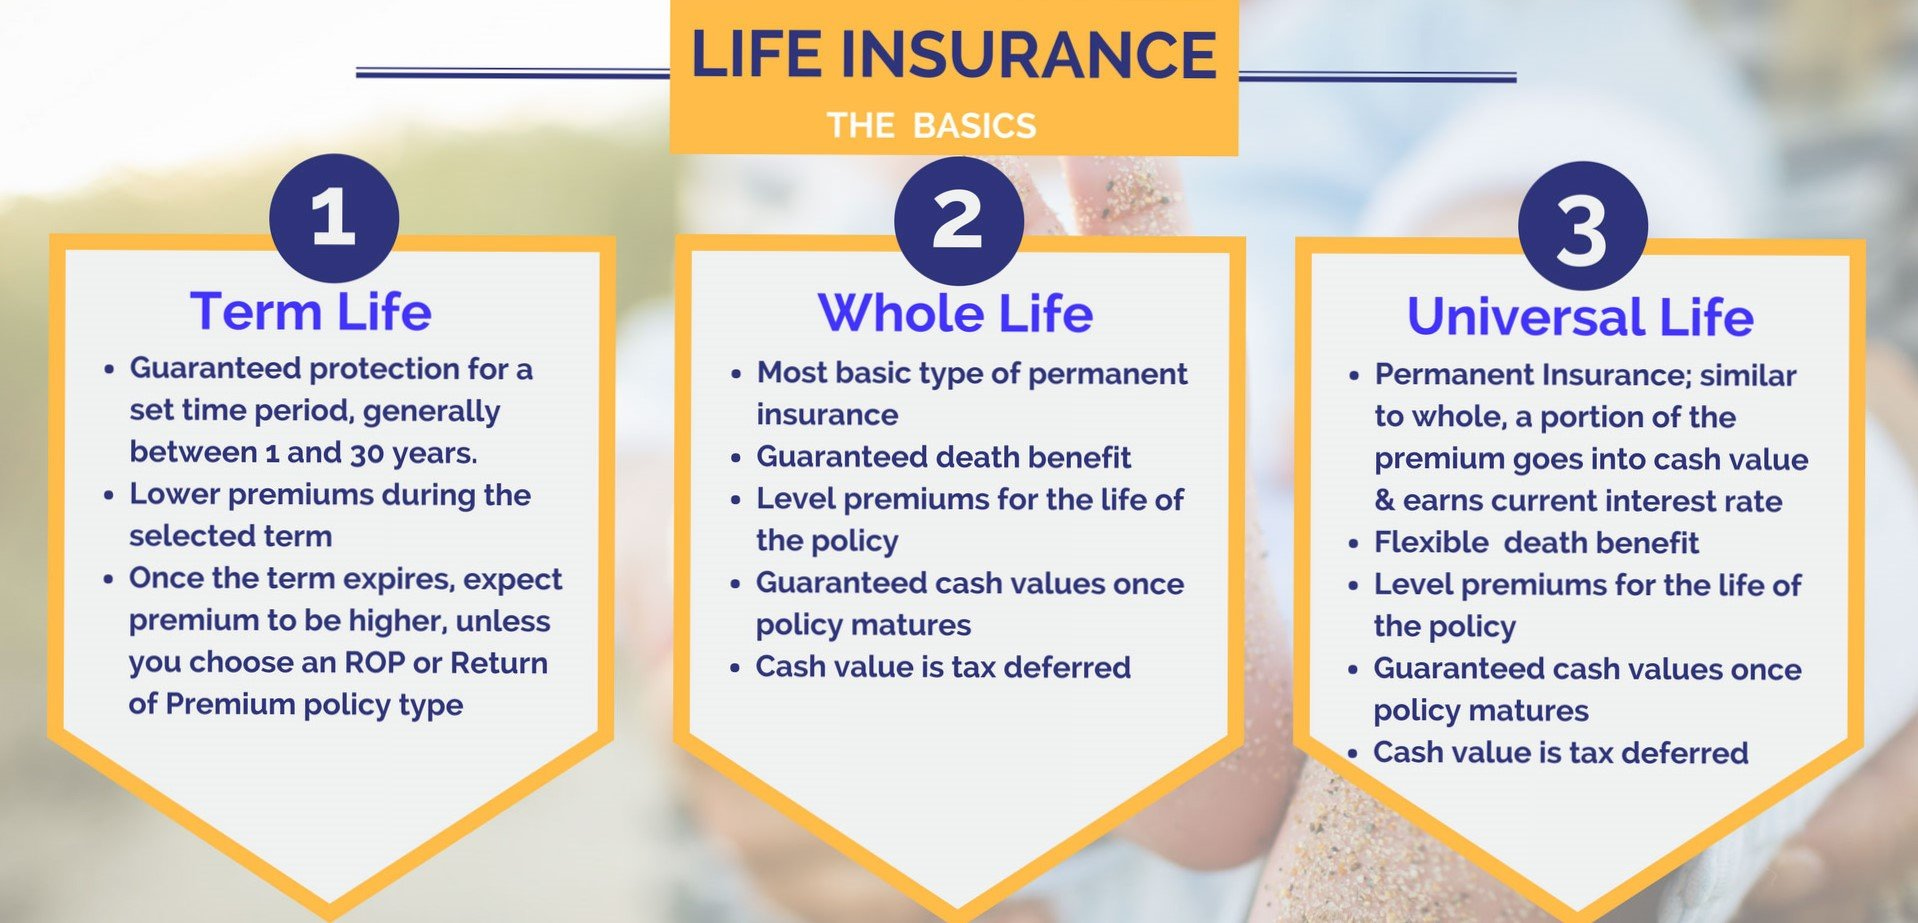
To understand what it means to prepay a life insurance policy, it is helpful to look at how different types of life insurance handle premiums. Term life insurance, which provides coverage for a specific period such as 10, 20, or 30 years, requires regular level payments to maintain coverage. If you stop paying, the policy lapses. Permanent life insurance—such as whole life or universal life—features a cash value component alongside the death benefit. In many permanent policies, you have the flexibility to pay more than the minimum required premium or even structure the contract to be fully paid up within a compressed timeframe.
Prepaying a policy does not mean buying insurance retroactively. Instead, it refers to front-loading funds into the policy's cash value or utilizing specific policy riders and design structures to satisfy the lifetime cost of the insurance contract ahead of schedule. When executed correctly, these extra funds compound tax-deferred within the policy, generating enough internal dividends or interest to cover future administrative fees and cost-of-insurance charges.
It is vital to distinguish between true whole life limited-pay contracts and unstructured overfunding. In a limited-pay structure (such as a 10-pay or 20-pay whole life policy), the contract is legally engineered from day one to be fully funded after a set number of years. Conversely, unstructured overfunding involves taking a flexible premium policy, like universal life, and injecting large sums of money into it later, subject to strict Internal Revenue Service (IRS) guidelines.
How Permanent Life Insurance Structuring Works
Permanent policies are designed to build equity over time. When you pay a premium, a portion covers the actual cost of insurance and administrative overhead, while the remainder flows into the policy's cash value account. This cash value grows based on fixed interest rates, dividends paid by mutual insurance companies, or index-linked performance, depending on the policy type.
When policyholders want to prepay or accelerate payments, they generally utilize one of two primary pathways: limited-pay schedules or paid-up additions (PUA) riders.
- Limited-Payment Policies: You choose a shorter payment horizon, such as 5, 10, or 20 years, or pay until a specific age like 65. The annual premiums are significantly higher than a lifetime-pay policy, but once the term concludes, you owe nothing further, and the policy remains active for life.
- Paid-Up Additions (PUA) Riders: Available primarily on whole life policies, a PUA rider allows you to inject lump sums of cash directly into purchasing small amounts of paid-up insurance. These additions instantly boost both your total death benefit and your cash value, accelerating the timeline to a fully funded status.
The Mechanics of "Paid-Up" Status
Achieving a "paid-up" status means that the internal cash value and its subsequent earnings are mathematically sufficient to sustain the policy until the insured's mortality, eliminating out-of-pocket premium bills. However, policyholders must monitor these accounts periodically. If market performance drops, interest rates decline, or loans are taken against the cash value, a policy that was once projected to be self-sustaining may experience a "lapse notice," requiring fresh capital injections to keep it afloat.

Benefits of Accelerating Life Insurance Payments
For individuals with high liquidity, business owners, or those looking to deploy estate-planning strategies, prepaying or accelerating life insurance payments offers several distinct advantages.
One of the primary benefits is mitigation against future financial shocks. By locking in a limited payment schedule or fully funding a policy early, you protect your future self from premium obligations during retirement, periods of unemployment, or declining health. This ensures that your estate protection or family income replacement vehicle remains intact regardless of shifting personal financial circumstances.
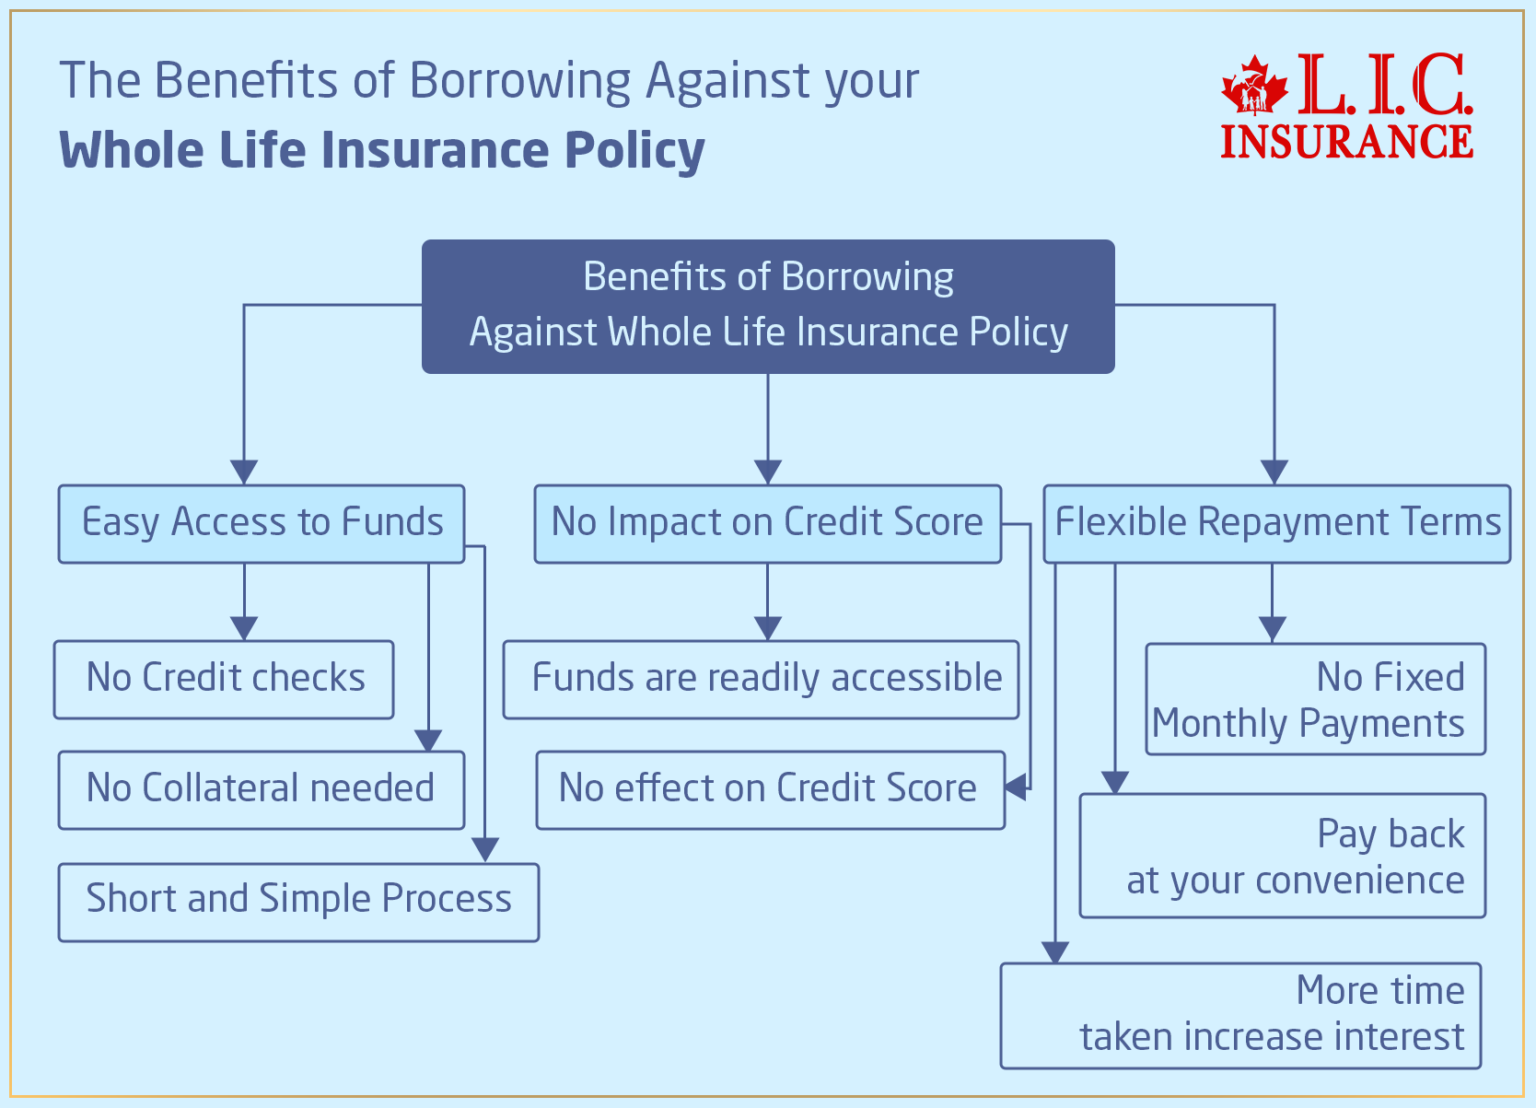
Furthermore, accelerating cash value growth allows the policy to act as a private asset container. The cash value inside a permanent life insurance policy grows on a tax-deferred basis. Policyholders can often access this cash value via tax-free policy loans or withdrawals to supplement retirement income, fund education expenses, or seize business opportunities. Front-loading the policy maximizes the compounding period for these funds.
Finally, prefunding or utilizing limited-pay structures provides psychological and budgeting peace of mind. Knowing that a major financial obligation is permanently settled removes the risk of accidental policy lapse due to missed payments—a common pitfall that often occurs among elderly policyholders managing multiple bills.
Regulatory Safeguards and Tax Implications
The IRS closely monitors cash value life insurance to prevent individuals from using these contracts merely as tax-sheltered investment vehicles. If a life insurance policy accumulates too much cash too quickly, it loses its tax-advantaged status and becomes classified as a Modified Endowment Contract (MEC).
Understanding the Modified Endowment Contract (MEC) Rule
Under federal tax law, the cumulative premiums paid into a life insurance policy cannot exceed the "7-pay test." This test determines the maximum amount of money you can pour into a policy over the first seven years while still retaining traditional life insurance tax benefits.
- Non-MEC Status: If your prepayments stay below the 7-pay limit, withdrawals are treated on a First-In, First-Out (FIFO) basis. This means your initial withdrawals are considered a return of your cost basis (tax-free) before dipping into gains. You can also take tax-free policy loans against the cash value.
- MEC Status: If you exceed the 7-pay limits, the policy becomes a MEC permanently. Tax treatment shifts to Last-In, First-Out (LIFO), meaning any withdrawals or loans are taxed as ordinary income first, subject to potential early-withdrawal penalties if the policyholder is under age 59½.
Therefore, anyone looking to prepay a life insurance policy must work closely with a financial professional to calculate exact MEC limits, ensuring the prepayment schedule achieves the desired accumulation without triggering unwanted tax penalties.
Comparing Premium Payment Approaches
To visualize how different payment strategies impact your financial commitment, cash value growth, and tax exposure, review the following comparison of common permanent life insurance funding methods.
| Feature / Strategy | Lifetime Pay Whole Life | Limited-Pay Whole Life (e.g., 10-Pay) | Universal Life with Overfunding (PUA / Lump Sum) |
|---|---|---|---|
| Payment Duration | Lifetime (until death or age 100/121) | Fixed period (e.g., exactly 10 years) | Flexible (discretionary lump sums or ongoing) |
| Annual Financial Commitment | Lower, predictable annual payments | Higher annual payments during the active term | Variable; depends on current interest rates and caps |
| Cash Value Growth Speed | Moderate and steady over a long horizon | Rapid accumulation during the active payment years | Highly customizable based on funding velocity |
| Risk of Policy Lapse | Higher if future income drops and premiums lapse | Lower after the limited payment term concludes | Moderate; requires monitoring against rate fluctuations |
| MEC Risk | Low, unless extra unscheduled cash is added | Generally engineered to stay just under the 7-pay limit | High risk if contributions exceed the IRS 7-pay test |
Common Mistakes and Pitfalls to Avoid
Navigating life insurance acceleration requires precision. Missteps can result in unexpected tax liabilities, insufficient coverage, or wasted capital.
- Triggering an Unintentional MEC: Many policyholders attempt to maximize their cash value by throwing large lump sums into a policy without consulting illustrations or compliance limits, accidentally converting their policy into a Modified Endowment Contract.
- Ignoring the Cost of Insurance (COI): As insured individuals age, the internal cost to insure their life increases. If a policy is prefunded but under-optimized, the rising COI can deplete the cash value faster than anticipated, causing the policy to lapse later in life.
- Failing to Review Policy Annual Statements: Permanent insurance is not a "set-it-and-forget-it" asset. Changes in insurer dividend scales, fluctuating market indexes in indexed universal life policies, or policy loans can alter the trajectory of a prefunded policy. Annual reviews with a licensed insurance professional are essential.
- Assuming All Riders Are Equal: Not all insurance companies offer the same flexibility for paid-up additions or lump-sum injections. Buying a rigid policy that penalizes early prepayments will severely limit your strategy.
Steps to Safely Prepay or Accelerate Your Policy
If you have decided that accelerating or prepaying a permanent life insurance policy aligns with your financial plan, follow these structured steps to execute the strategy safely:
- Audit Existing Coverage: Review your current life insurance contracts to determine whether you hold term or permanent insurance. Term policies cannot be prepaid; they must be converted to permanent coverage first if you wish to build cash value.
- Consult a Licensed Fiduciary or Agent: Request a formal in-force illustration from your insurance carrier. This document outlines exactly how different lump-sum payments or shortened payment schedules will affect your cash value trajectory and death benefit.
- Calculate IRS Limits: Have your advisor run the 7-pay test calculations to ensure your proposed prepayment amount will not inadvertently trigger Modified Endowment Contract status, unless that aligns with your specific tax planning goals.
- Execute and Monitor: Fund the policy according to the agreed-upon design structure—whether through a limited-pay schedule or strategic PUA rider utilization—and schedule annual reviews to monitor performance against initial projections.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial, tax, or legal advice. Life insurance policies involve complex rules, underwriting standards, and tax considerations. Consult a certified financial planner, tax advisor, or licensed insurance professional before making significant financial commitments.
Frequently Asked Questions
Can I prepay a term life insurance policy?
No, term life insurance policies cannot be prepaid to eliminate future payments. Term insurance is structured purely for temporary coverage with level premiums for a set duration. If you stop paying term premiums, the policy lapses. Prepaying is exclusively a feature of permanent life insurance products like whole life or universal life.
What happens if I stop making payments on a limited-pay life insurance policy?
If you have completed all required payments on a limited-pay policy (such as a 10-pay whole life contract), stopping payments will not cause the policy to lapse. The cash value accumulated and its internal dividends will fully sustain the policy for the rest of your life, provided no loans or withdrawals have destabilized the account.
Does prepaying a life insurance policy increase the death benefit?
It can, depending on how the prepayments are structured. If your prepayments purchase Paid-Up Additions (PUAs), both your cash value and your total death benefit will increase. However, if you simply overfund a flexible universal life policy without increasing the face amount, the death benefit may remain level while the cash value grows more rapidly.
Can I withdraw money from a prefunded life insurance policy?
Yes, permanent policies allow you to access your cash value through withdrawals or policy loans. If the policy is a non-MEC, withdrawals up to your total cost basis are generally tax-free, and policy loans are not treated as taxable income. However, taking money out reduces your cash value and can impact the long-term sustainability of the policy.
How do I know if my prepayment will trigger a Modified Endowment Contract (MEC)?
You must ask your insurance carrier or financial advisor to run a 7-pay test calculation before submitting any lump-sum payments. This calculation measures your cumulative payments against federal limits defined by the IRS to ensure the policy retains its standard tax advantages.
To ensure your estate and financial plans are executed properly, always verify your policy's current health and cash value performance directly with your insurance carrier before committing large sums of capital.
Image Gallery
Select an image to open it in a new tab.



Simon Caldwell
Enterprise Technology and Systems Editor
