Navigating the Highest Tax Rates in the World: A Comprehensive Global Analysis
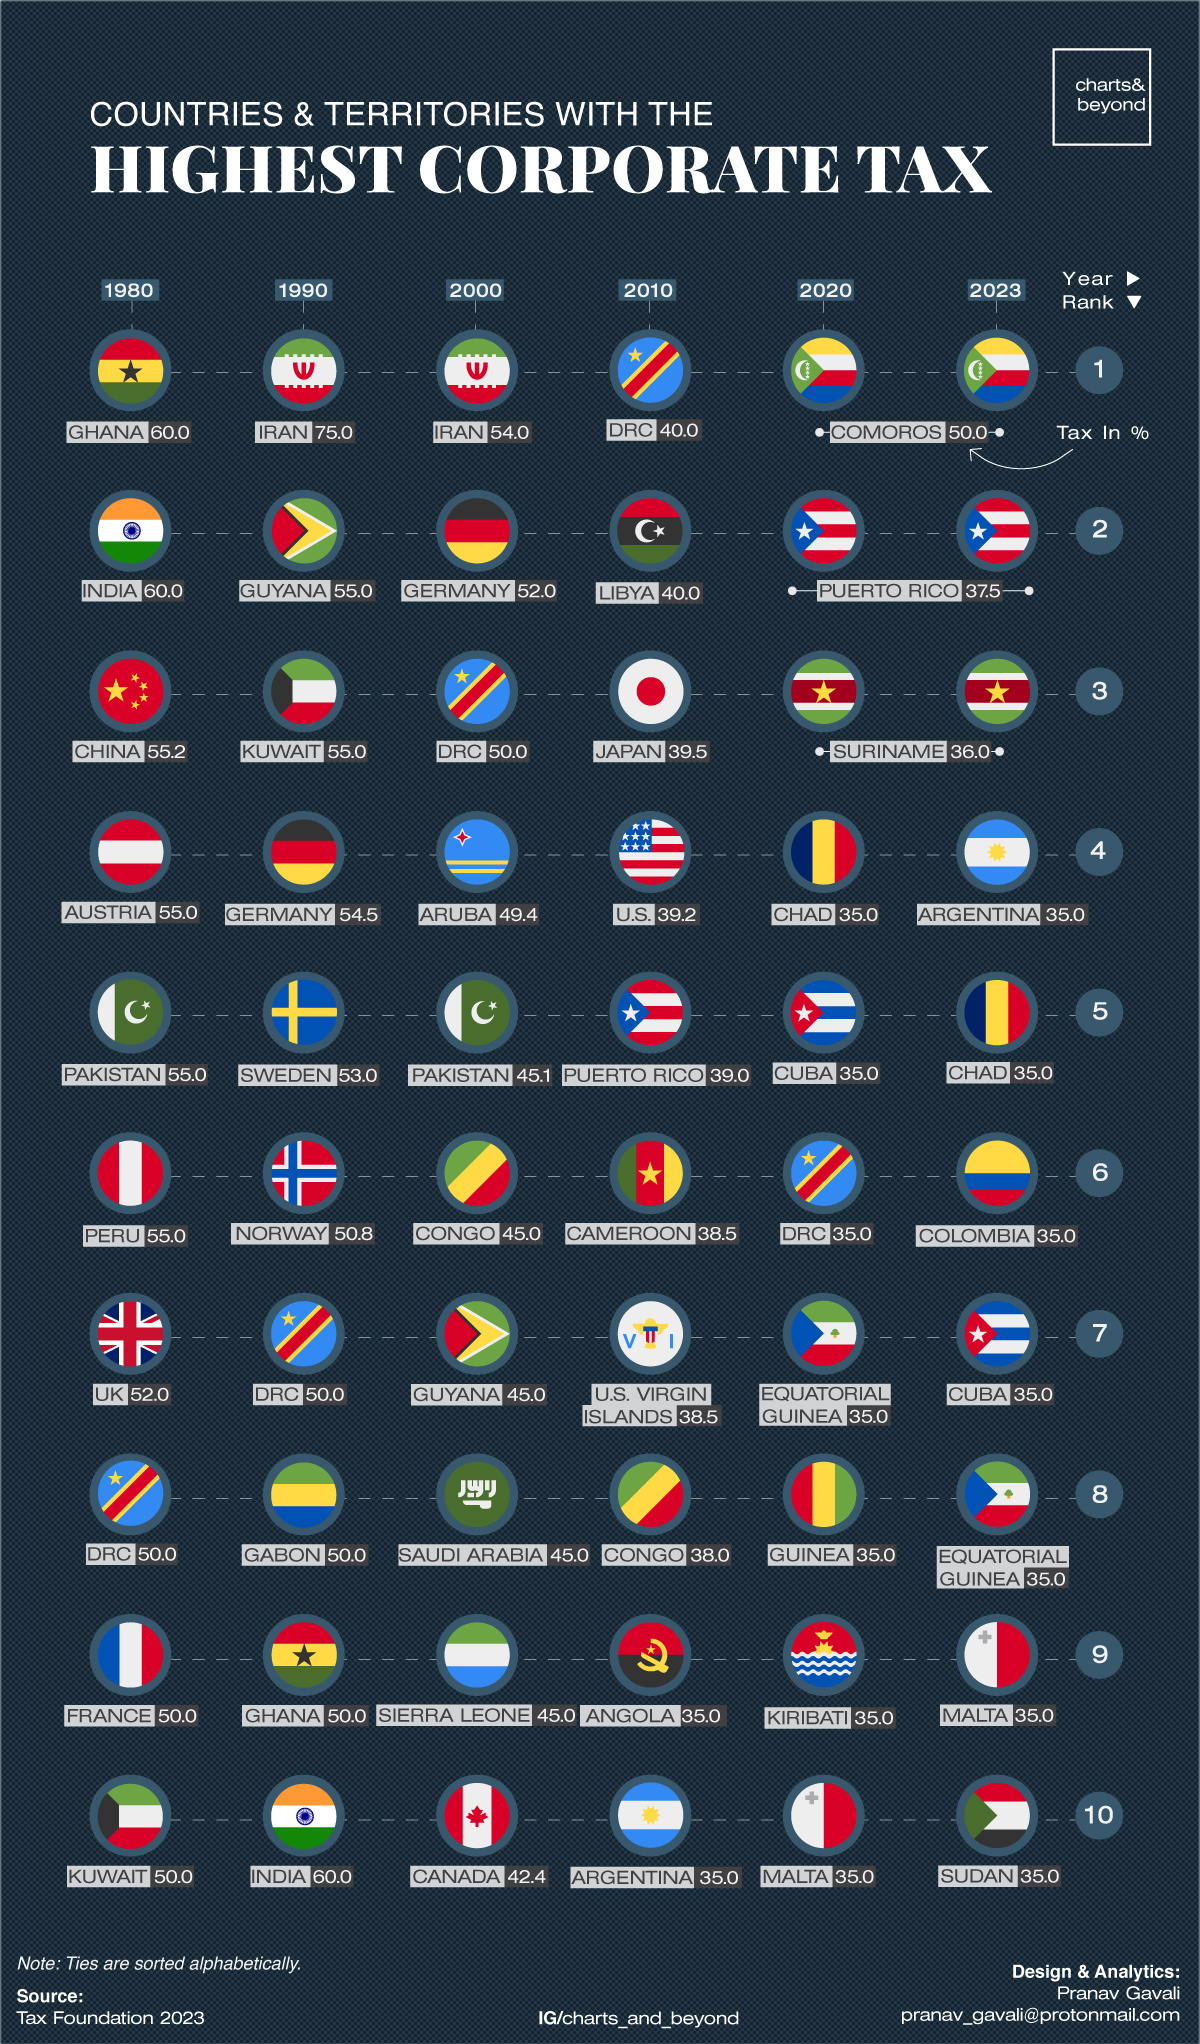
When evaluating the highest tax rates in the world, researchers and taxpayers look primarily at nations within the Organisation for Economic Co-operation and Development (OECD), where progressive income tax structures, robust social safety nets, and high value-added taxes converge. Côte d'Ivoire, Denmark, Japan, and Sweden frequently lead global indexes for top-tier statutory personal income tax rates, often exceeding 50% for high-income earners when combining national and local levies.
Understanding where the highest tax burdens fall requires looking beyond headline figures to examine how different nations structure their fiscal policies. Tax systems involve a complex interplay of personal income brackets, social security contributions, wealth taxes, consumption taxes, and corporate levies. For individuals, expatriates, and multinational corporations analyzing global mobility or compliance, deciphering these structures requires a clear breakdown of statutory limits, effective tax rates, and jurisdictional nuances.
The Framework of Global Taxation: How Top Rates Are Calculated
To understand why certain countries feature prominently on lists of the highest tax rates in the world, one must first examine the mechanics of taxation. A headline tax rate represents the statutory maximum percentage applied to the highest income bracket. However, the true tax burden experienced by an individual or corporation is shaped by a variety of distinct components.
Statutory vs. Effective Tax Rates
The statutory rate is the legal maximum marginal rate set by government legislation. For instance, if a country has a top statutory personal income tax rate of 55%, every dollar earned above a specific high-income threshold is theoretically subject to that 55% levy.
Conversely, the effective tax rate is the actual percentage of total income paid after accounting for deductions, exemptions, tax credits, and progressive bracket scaling. Because progressive tax systems apply lower rates to initial income tiers, even high earners in high-tax countries rarely pay their marginal rate on their entire gross income.
Key Components of High-Tax Regimes
Nations with heavy tax burdens typically rely on a combination of the following revenue streams:
- Personal Income Tax (PIT): Progressive brackets targeting wages, salaries, business income, and investment returns.
- Social Security Contributions (SSC): Mandatory payments levied on employers and employees to fund pensions, healthcare, and unemployment insurance.
- Consumption Taxes: Value-Added Tax (VAT) or Goods and Services Tax (GST) applied to nearly all commercial transactions, often ranging between 20% and 27% in high-tax jurisdictions.
- Wealth and Property Taxes: Periodic levies on net worth, high-value real estate, or specific luxury assets.
Spotlight on Personal Income Tax Leaders
OECD data and reports from financial institutions consistently highlight specific countries as having the highest statutory personal income tax rates. While specific thresholds shift annually to adjust for inflation, the structural leaders remain largely consistent.
Denmark and the Nordic Model
Denmark frequently tops or ranks near the top of global lists for personal tax burdens. The Danish tax system relies heavily on income taxes rather than corporate or property taxes.
- Top Marginal Rates: The combined state and municipal income tax can push the top marginal rate past 55%.
- The Trade-Off: High earners in Denmark contribute heavily to a comprehensive welfare state that provides universal healthcare, tuition-free higher education, and extensive childcare subsidies.
Japan’s Progressive Structure
Japan features a heavily progressive national income tax system supplemented by local inhabitant taxes.
- Top Marginal Rates: The national income tax rate tops out at 45% for earners exceeding specific high-income thresholds. When combined with the local inhabitant tax (typically a flat 10%), the maximum combined marginal rate reaches 55%.
- Complex Brackets: Japan’s tax code includes multiple tiers, requiring careful calculation for high-net-worth individuals and corporate expatriates.
Other Notable High-Tax Jurisdictions
Countries such as Sweden, Finland, Austria, and France also feature top marginal income tax rates hovering between 50% and 55%. In France, while the standard income tax top rate is 45%, additional high-income surcharges and extensive social contributions can significantly increase the total extraction rate on labor income.
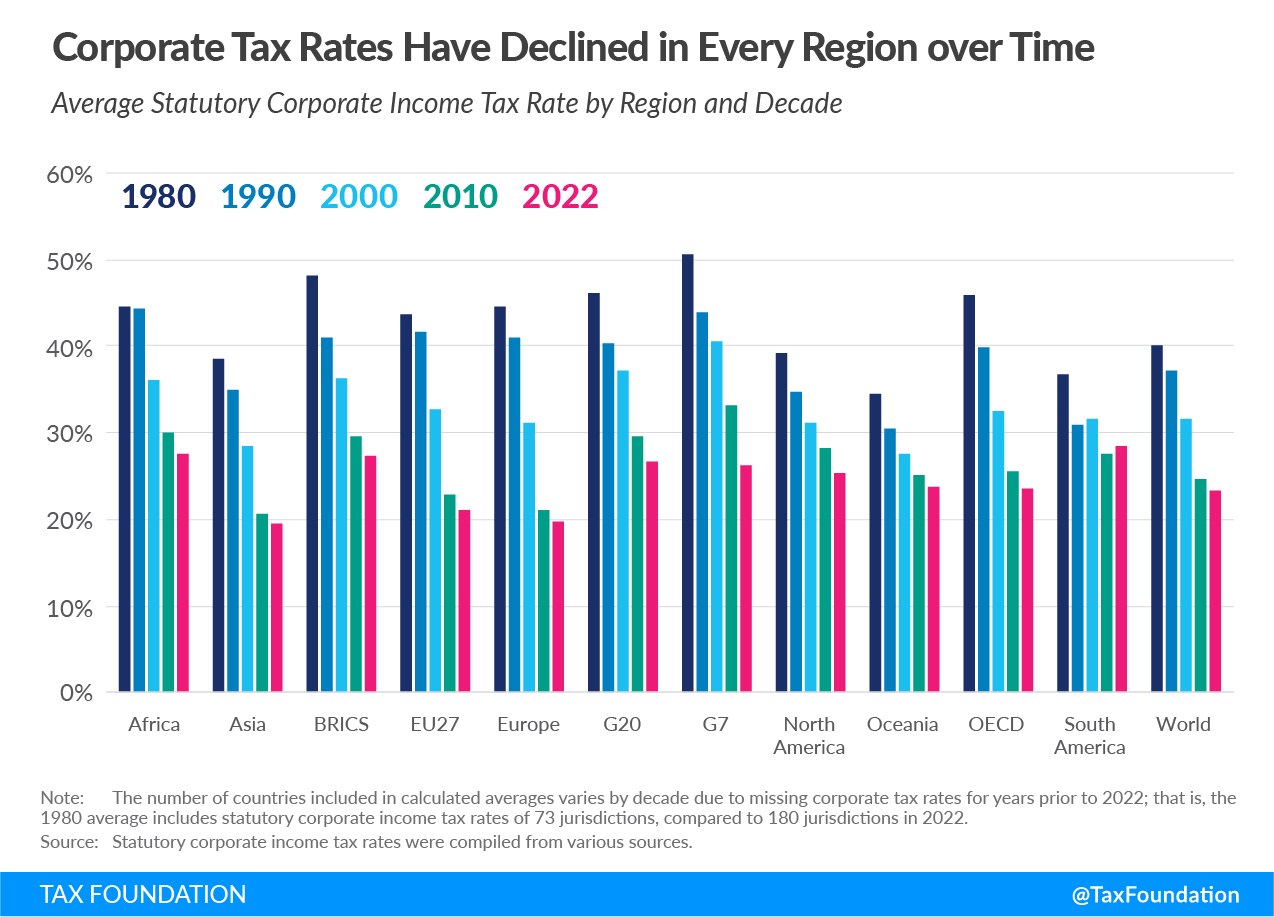
Comparative Overview of Global Tax Burdens
To illustrate how different nations balance fiscal policy, the following table compares key tax metrics across selected high-tax and benchmark economies.
| Country | Top Statutory Personal Income Tax Rate | Standard VAT Rate | Primary Structural Characteristic |
|---|---|---|---|
| Denmark | ~55.8% | 25% | High reliance on income tax to fund extensive universal public services. |
| Japan | ~55.0% (Combined) | 10% | Progressive national brackets paired with a mandatory 10% local inhabitant tax. |
| Sweden | ~52.3% (Average Top) | 25% | Significant municipal tax variation alongside robust social contributions. |
| France | ~45.0% (Plus Surcharges) | 20% | Heavy reliance on employer and employee social security contributions. |
| United States | ~37.0% (Federal) | None (State Sales Vary) | Lower federal income tax rates relative to Western Europe, offset by state taxes. |
Beyond Income: Social Contributions and Consumption Taxes
Focusing solely on personal income tax paints an incomplete picture. The highest tax rates in the world often manifest through cumulative taxation—where high income taxes are compounded by steep consumption and social security levies.
The Role of Social Security Contributions
In many European economies, mandatory social security contributions add a substantial layer to the cost of labor. These contributions are often split between the employer and the employee, though in some jurisdictions, the employer's share is exceptionally high. When evaluating total labor tax wedges—the total of income tax plus employee and employer social security contributions minus cash benefits—countries like Belgium, Germany, and France routinely record some of the highest figures among OECD nations, often exceeding 40% to 50% of total labor costs for average single workers.
High Consumption Taxes (VAT)
Consumption taxes are inherently regressive, taking a larger percentage of income from lower-income earners, but they serve as a primary revenue generator in high-tax welfare states. Countries utilizing the highest tax models frequently apply VAT rates of 20% to 27% (such as Hungary at 27% and several Scandinavian nations at 25%). These taxes apply universally to retail goods and services, ensuring that virtually all economic activity contributes to government revenue regardless of an individual's direct income tax bracket.
Compliance, Legal Limits, and Mitigation Strategies
High-tax environments naturally foster complex legal frameworks for tax planning, compliance, and residency restructuring. Navigating these jurisdictions requires strict adherence to local statutes and international tax treaties.
Residency and Territorial vs. Worldwide Taxation
Most high-tax nations operate on a worldwide taxation model, meaning residents are taxed on all global income regardless of where it is earned.
- Tax Residency Rules: Countries determine tax liability based on physical presence (typically the 183-day rule) or the maintenance of a permanent home.
- Exit Taxes: Several high-tax countries have implemented stringent exit taxes. These laws impose capital gains taxes on unrealized gains when a taxpayer attempts to renounce residency or citizenship, aiming to prevent capital flight.
Legal Deductions and Credits
High-tax jurisdictions frequently offer targeted deductions to encourage specific behaviors, such as contributions to private pension schemes, energy-efficient home renovations, or charitable donations. However, governments in these regions often cap deductions or implement high-income phase-outs to ensure that high earners maintain a substantial effective tax liability.
Frequently Asked Questions
Which country has the highest income tax rate in the world?
Denmark and Japan frequently vie for the highest top statutory personal income tax rates, with combined national and local rates reaching approximately 55% or higher for top-tier earners. The exact ranking fluctuates annually based on legislative adjustments to tax brackets and local surcharges.
Do high tax rates apply to all income earned in these countries?
No. High tax rates operate on a progressive scale. This means they apply only to income earned above specific high-income thresholds. Initial earnings are taxed at significantly lower rates, and various deductions or exemptions can reduce the overall effective tax rate.
How do consumption taxes affect the overall tax burden in high-tax countries?
Consumption taxes, such as Value-Added Tax (VAT) ranging from 20% to 27%, add a significant layer to the total tax burden. While income taxes target earnings, VAT applies directly to everyday purchases, ensuring that government revenue is collected at every point of retail exchange.
Are capital gains taxed at the same rate as labor income in high-tax nations?
Not always. While some high-tax countries apply progressive income tax rates to capital gains, many nations utilize separate, flat capital gains tax rates or provide specific exemptions to encourage domestic investment and capital market participation.
What is a tax wedge, and why is it important?
A tax wedge measures the total tax burden on labor income, calculated as the sum of personal income tax, employee social security contributions, and employer social security contributions minus benefits received, expressed as a percentage of total labor costs. It provides a more accurate picture of total taxation on employment than income tax rates alone.
Conclusion and Strategic Next Actions
Analyzing the highest tax rates in the world demonstrates that heavy taxation is typically a deliberate policy choice designed to fund extensive public infrastructure, universal healthcare, and social safety nets. For individuals and businesses navigating these jurisdictions, the primary objective is ensuring strict compliance while fully utilizing lawful deductions, credits, and international tax treaties. Taxpayers considering relocation, cross-border employment, or international asset structuring should consult qualified international tax professionals to evaluate both statutory liabilities and effective tax burdens accurately.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
