
Commercial auto insurance is essential in Downey, CA, because it ensures legal compliance with California’s financial responsibility laws and shields business assets from the escalating costs of litigation, medical expenses, and vehicle repairs. Since personal auto policies typically exclude coverage for business-related activities, Downey business owners without commercial coverage face significant out-of-pocket risks during routine operations, deliveries, or service calls.
The Intersection of Business Growth and Risk in Downey
Located in the heart of the Gateway Cities, Downey serves as a critical hub for logistics, manufacturing, and professional services. With its proximity to major transportation arteries like the I-5, I-105, I-605, and the 710 freeway, the volume of commercial traffic is exceptionally high. As of 2026, the density of traffic in the Los Angeles Basin has led to a statistical increase in minor and major collisions, making specialized insurance not just a suggestion, but a fundamental pillar of business continuity.
When a vehicle is used for business purposes—whether it is a florist delivering arrangements along Firestone Boulevard or a contractor hauling equipment to a job site near the Promenade at Downey—the risk profile changes. Insurance carriers distinguish between personal use and commercial use based on the frequency of travel, the weight of the cargo, and the specialized nature of the vehicle. For Downey entrepreneurs, understanding this distinction is the first step in avoiding catastrophic financial loss.
Legal Requirements and California State Mandates
California law is explicit regarding vehicle insurance. Every motor vehicle operated on state roadways must be covered by a policy that meets or exceeds the minimum financial responsibility limits. However, for commercial entities, the stakes and the requirements are often higher than those for individual commuters.
Minimum Liability Limits
In California, the statutory minimums for private passenger vehicles are often insufficient for commercial operations. While the state requires 15/30/5 coverage ($15,000 for injury/death to one person, $30,000 for injury/death to more than one person, and $5,000 for property damage), commercial vehicles—especially those with a high Gross Vehicle Weight Rating (GVWR) or those transporting passengers—are subject to much stricter federal and state filings.
For example, businesses involved in interstate commerce or those operating heavy trucks must comply with Federal Motor Carrier Safety Administration (FMCSA) regulations, which often demand liability limits of $750,000 to $5,000,000, depending on the cargo. Even for small local businesses in Downey, a $5,000 property damage limit is virtually useless in 2026, where the average cost of a modern electric or hybrid vehicle repair can easily exceed $10,000 for a minor bumper-to-bumper incident.
The Consequences of Non-Compliance
Operating without valid commercial insurance in Downey can lead to severe penalties:
- Suspension of Registration: The California DMV may suspend the vehicle’s registration if insurance information is not electronically reported.
- Fines and Penalties: Significant monetary fines that increase with subsequent offenses.
- Impoundment: Law enforcement in Downey and surrounding Los Angeles County jurisdictions has the authority to impound uninsured vehicles.
- Personal Liability: Perhaps most importantly, if an accident occurs, the business owner’s personal assets (homes, savings, and future earnings) can be seized to satisfy a judgment.

Protecting Assets Against "Social Inflation" and High Litigation Costs
By 2026, the insurance industry has seen a continued rise in "social inflation," a term referring to the rising costs of insurance claims resulting from increased litigation, broader jury awards, and more aggressive legal tactics. In a litigious environment like Southern California, a single accident involving a company vehicle can result in a multi-million dollar lawsuit.
Commercial auto insurance matters because it provides "Duty to Defend" coverage. This means the insurance company is obligated to provide legal representation and cover court costs if the business is sued following an accident. Without this, a Downey business owner would have to pay a retainer for a specialized defense attorney out of pocket, a cost that often exceeds $250 per hour in the Los Angeles market.
Key Coverage Components for Downey Businesses
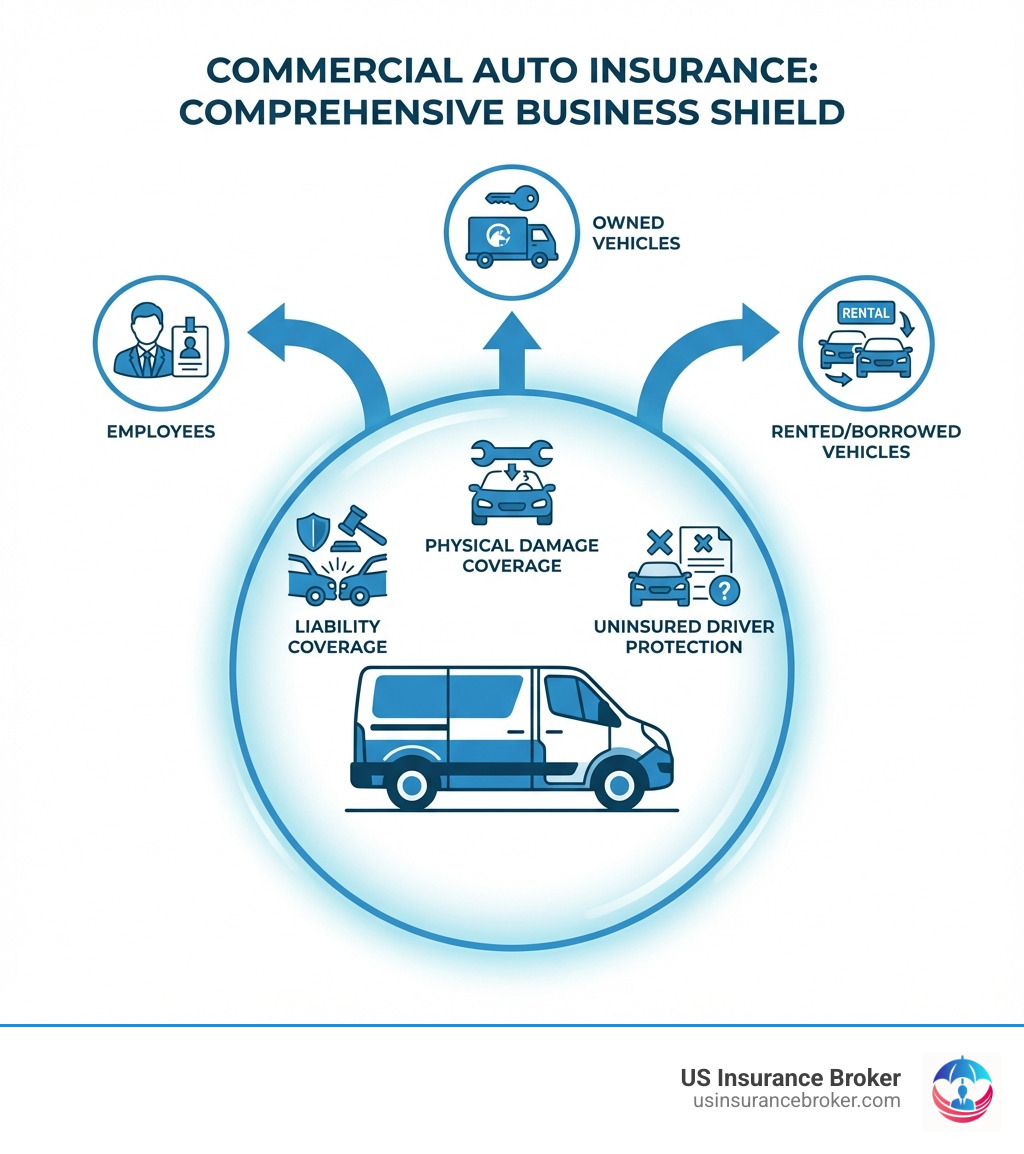
A comprehensive commercial auto policy in Downey is modular, allowing owners to tailor coverage to their specific operational risks.
Liability Insurance (Bodily Injury and Property Damage)
This is the core of the policy. It pays for injuries to others and damage to their property when your business driver is at fault. In Downey’s congested intersections, such as Lakewood Boulevard and Imperial Highway, the likelihood of multi-vehicle accidents is higher. Liability coverage ensures that if your driver rear-ends a luxury vehicle or causes a chain-reaction crash, the business is protected from the resulting claims.
Physical Damage Coverage: Collision and Comprehensive
While liability protects others, physical damage coverage protects your own investment.
- Collision: Covers damage to your business vehicle resulting from a crash with another vehicle or object.
- Comprehensive: Protects against non-collision events such as theft, vandalism, fire, or weather damage. Given the urban environment of Downey, comprehensive coverage is vital for protecting vehicles parked overnight in commercial lots where catalytic converter theft or vandalism remains a persistent risk.
Uninsured/Underinsured Motorist (UM/UIM) Coverage
A significant percentage of drivers on California roads either lack insurance or carry only the bare minimum. If a business vehicle is hit by an uninsured driver in Downey, the business would be left with the bill for repairs and medical expenses for the employee. UM/UIM coverage steps in to fill this gap, ensuring the business is not penalized for the negligence of others.
Hired and Non-Owned Auto (HNOA) Insurance
This is one of the most overlooked coverages for small businesses in Downey. HNOA provides liability protection when employees use their personal vehicles for business errands (like going to the bank or picking up supplies) or when the business rents a vehicle. Most personal auto policies have a "business use" exclusion; if an employee has an accident while performing a task for the employer, the employee’s personal insurer may deny the claim, leaving the business owner solely responsible for the damages.
Comparing Personal and Commercial Auto Insurance
Many new entrepreneurs in Downey attempt to save money by relying on their personal auto policies. This is a dangerous misconception. The table below illustrates the critical differences between the two types of coverage.
| Feature | Personal Auto Insurance | Commercial Auto Insurance |
|---|---|---|
| Primary Insured | Individuals or married couples. | Corporations, LLCs, Partnerships, or DBAs. |
| Typical Liability Limits | Generally lower ($15k–$300k). | Much higher ($500k–$1,000,000+). |
| Driver Eligibility | Limited to household members. | Covers any employee with a valid license. |
| Vehicle Types | Standard cars, SUVs, and light trucks. | Heavy trucks, vans, trailers, and specialized equipment. |
| Business Use Exclusion | Common for delivery, transport, or hauling. | Explicitly designed for business operations. |
| Cost | Lower premiums based on personal credit. | Higher premiums based on business risk and fleet size. |
The Geographic Risk Factor: Downey’s Transportation Infrastructure
Downey is geographically positioned in a way that increases commercial driving risks. The city is bisected or bordered by four of the busiest freeways in the United States.
- The 710 Freeway: A primary artery for trucks moving goods from the Ports of Los Angeles and Long Beach. Commercial vehicles in Downey often share the road with massive drayage trucks, increasing the severity of any potential collision.
- The 605 and 5 Freeways: These corridors are notorious for heavy congestion and "stop-and-go" traffic. Rear-end collisions are the most common type of accident in these areas, and for a business, even a minor "fender bender" can lead to a "whiplash" injury claim that can reach tens of thousands of dollars.
- Local Surface Streets: Busy thoroughfares like Firestone Boulevard and Paramount Boulevard feature high pedestrian activity and numerous commercial driveways. The risk of a "turning" accident or a pedestrian-related incident is a constant reality for local delivery drivers.
Operational Benefits Beyond Basic Protection
Commercial auto insurance offers several "hidden" benefits that help Downey businesses scale and operate more professionally.
Contractual Requirements
Most commercial contracts in Southern California require proof of insurance. If a Downey-based plumbing company wants to bid on a contract for a new housing development or a municipal project with the City of Downey, they will be required to provide a Certificate of Insurance (COI). This certificate must show specific commercial auto liability limits (typically $1 million) to ensure the hiring party is not held liable for the contractor’s transit risks.
Employee Retention and Safety
Providing commercial insurance protects the employees who drive for the company. When drivers know they are backed by a robust policy, it improves morale and reduces the personal financial stress associated with their job. Furthermore, many commercial insurers offer risk management tools, such as telematics or safety training programs, which can help Downey business owners monitor driver behavior and reduce the frequency of accidents.
Common Myths About Commercial Auto Insurance in Downey
Myth 1: "I only use my car for business occasionally, so I don't need it." In the eyes of an insurance adjuster, there is no "occasional" business use. If an accident occurs while you are delivering a product or traveling to a client meeting, it is a business claim. If you haven't disclosed this use to your personal insurer, they have the right to deny the claim and cancel your policy.
Myth 2: "Commercial insurance is too expensive for a small startup." While premiums are generally higher than personal policies, the cost is a tax-deductible business expense. Furthermore, the cost of a single uninsured accident could put a startup out of business permanently. In 2026, many carriers offer "usage-based" commercial insurance, allowing small Downey businesses to pay premiums based on the actual miles driven for work.
Myth 3: "My general liability policy covers my vehicles." General liability insurance covers third-party injuries and property damage at your place of business or caused by your products/services, but it almost always excludes "auto-related" incidents. You need a specific commercial auto policy or an endorsement to bridge this gap.
Frequently Asked Questions
Does commercial auto insurance cover my tools and equipment inside the vehicle?
Generally, no. Commercial auto insurance covers the vehicle itself and the liability arising from its use. To protect tools, equipment, or cargo being transported, you typically need Inland Marine Insurance or a "Motor Truck Cargo" endorsement. For a contractor in Downey, having both is essential to ensure that a stolen van doesn't also result in the loss of thousands of dollars in uninsured tools.
Can I add my employees to my personal auto policy instead?
Adding employees to a personal policy is usually not permitted if they are driving for business purposes. Personal policies are designed for "permissive use" (e.g., a friend borrowing your car), not for repetitive business tasks. A commercial policy is designed to cover a rotating list of drivers and provides the necessary legal protections for the business entity.
How are premiums calculated for Downey businesses in 2026?
Insurance companies look at several factors: the driving records of all listed employees, the radius of operation (how far from Downey the vehicles travel), the type of vehicles, and the claims history of the business. Because Downey is in a high-traffic zone, local rates may be slightly higher than in rural areas, but maintaining a clean "California Motor Vehicle Report" (MVR) for all drivers can significantly lower costs.
What is "Combined Single Limit" (CSL) coverage?
Many commercial policies in California use CSL. Unlike "split limits" (which have different caps for per-person and per-accident), a CSL policy provides one large pool of money (e.g., $1,000,000) that can be used for any combination of bodily injury and property damage. This provides greater flexibility and protection during a complex accident involving multiple parties.
Do I need commercial insurance if I use a trailer?
Yes. In California, while the liability from the towing vehicle often extends to the trailer, the physical damage to the trailer itself must be specifically scheduled on a commercial policy. If you are a landscaper or a hauler in Downey, failing to list the trailer could mean the insurance company will not pay to replace it if it is damaged or stolen.
Next Steps for Downey Business Owners
To ensure your business is adequately protected, the first step is to conduct a "Vehicle Use Audit." Identify every vehicle used for business tasks, who drives them, and what they carry.
- Consult a Local Agent: Work with an insurance professional familiar with the California Insurance Code and the specific risks of the Los Angeles Basin.
- Review Limits: Avoid the temptation to opt for state minimums. In 2026, a $1,000,000 liability limit is the standard recommendation for even small commercial operations.
- Verify Employee Licenses: Regularly check the MVRs of your employees. Your insurance company will do this, and a driver with a poor record could cause your premiums to spike or lead to a policy cancellation.
- Implement a Safety Policy: Documented driving safety standards can sometimes lead to premium discounts and, more importantly, reduce the likelihood of an accident occurring in the first place.
Commercial auto insurance is not just a monthly bill; it is a strategic asset that allows Downey businesses to operate with confidence on some of the busiest roads in the country. By securing the right coverage, you protect your employees, your reputation, and your financial future.
Image Gallery
Select an image to open it in a new tab.



Zara El-Hashem
Sociocultural Dynamics and Academics Writer
