
An auto insurance policy number is a unique alphanumeric identifier assigned by an insurance carrier to a specific customer's contract, typically ranging from 6 to 15 characters. This sequence is not just a random string; it contains encoded data regarding the state of issuance, underwriting company, specific coverage types, and unique risk classifications used by insurers to instantly retrieve your active coverage records.
Navigating the administrative aspects of motor vehicle ownership involves interacting with a wide array of documentation, database records, and unique identifiers. Among these, the auto insurance policy number is arguably the most critical piece of administrative data a driver possesses. Whether you are pulled over by law enforcement, involved in a roadside accident, renewing your vehicle registration at the Department of Motor Vehicles (DMV), or simply logging into your online insurer portal, this code serves as the primary key to your financial protection contract. Despite its daily importance, many policyholders view their policy number as an arbitrary sequence of digits, much like a random password. Understanding how these numbers are structured, where to locate them, and why they matter ensures that you can handle roadside emergencies, regulatory verifications, and insurance claims with absolute confidence.
The Anatomy of an Auto Insurance Policy Number
Insurance companies do not issue policy numbers by drawing random numbers out of a hat. Instead, every major carrier utilizes a structured, proprietary syntax that encodes critical administrative and underwriting details. While proprietary algorithms vary significantly between firms—such as Progressive, State Farm, GEICO, or Allstate—most policy numbers follow a standardized structural pattern that combines geographic data, company identifiers, and chronological sequencing.
Typically, an auto insurance policy number ranges from six to fifteen characters and may consist entirely of numbers, letters, or a combination of both (alphanumeric). Understanding the hidden architecture of these numbers helps policyholders decipher their insurance documents and ensures they provide accurate information when filing a claim.
Common Components Embedded in Policy Numbers
While proprietary formulas are closely guarded trade secrets meant to prevent fraud and maintain internal efficiency, industry standards dictate that most policy numbers break down into distinct segments:
- Company or Underwriter Code: The initial two to four digits frequently identify the specific corporate entity or underwriting company within a larger insurance group that issued the policy. For example, a national insurance holding company might use different prefix codes for its standard-risk subsidiary versus its high-risk or specialty-risk subsidiary.
- State or Regional Identifier: Many carriers embed a numeric or alphabetic state code corresponding to the jurisdiction where the policy was originated and underwritten. This ensures compliance with state-specific minimum liability limits and regulatory mandates.
- Product Line Indicator: Certain insurers include a marker denoting the line of business. For instance, a specific letter combination might designate a personal automobile policy, distinguishing it from a commercial auto policy, motorcycle insurance, or homeowners insurance.
- Sequential Account or Customer Identifier: A large block of the middle digits represents a unique counter assigned to the policyholder or the specific contractual agreement. This counter ensures that no two active policies share the same sequence.
- Renewal or Endorsement Counter: The final digits or suffix characters sometimes indicate how many times a policy has been renewed or whether specific riders and endorsements have been attached to the base contract.
Example Breakdown of a Simulated Policy Number
To visualize how these elements come together, consider a hypothetical auto insurance policy number: PA-489201-B2.
- PA: Represents the prefix or state code, indicating that the policy was written out of Pennsylvania or under a specific personal auto underwriting program.
- 489201: The core unique policy identifier, distinguishing this specific contract from millions of others within the database.
- B2: A suffix denoting the underwriting tier or the number of policy renewals the account has undergone.
Recognizing these structural nuances helps drivers verify the authenticity of their paperwork and communicate more effectively with insurance customer service representatives.
Where to Find Your Auto Insurance Policy Number
When you need your policy number on short notice—such as during a traffic stop or immediately following a fender bender—knowing exactly where to look prevents unnecessary panic. Insurance carriers print this identifier across multiple physical and digital mediums.
Physical and Digital Documents
Every driver should maintain easy access to their policy number through at least one physical and one digital source. The most reliable locations include:
- The Insurance ID Card: This is the primary physical document issued by your carrier. By law, drivers are required to keep proof of insurance in their vehicles. The policy number is prominently displayed near the top or middle section of the card, usually labeled explicitly as "Policy Number."
- The Declarations Page (Dec Page): This is the summary page of your insurance contract, typically arriving at the beginning of each policy term. It outlines your coverage limits, deductible amounts, premium costs, and lists your exact policy number at the very top.
- Billing Statements and Renewal Notices: Monthly or semi-annual invoices sent by mail or email will always display the policy number so payment processing systems can credit the correct account.
- Mobile Apps and Online Portals: Modern insurance carriers provide smartphone applications and web dashboards. Logging into your account via Face ID, fingerprint, or password instantly reveals your digital insurance card and policy number, even if you misplaced your physical paperwork.
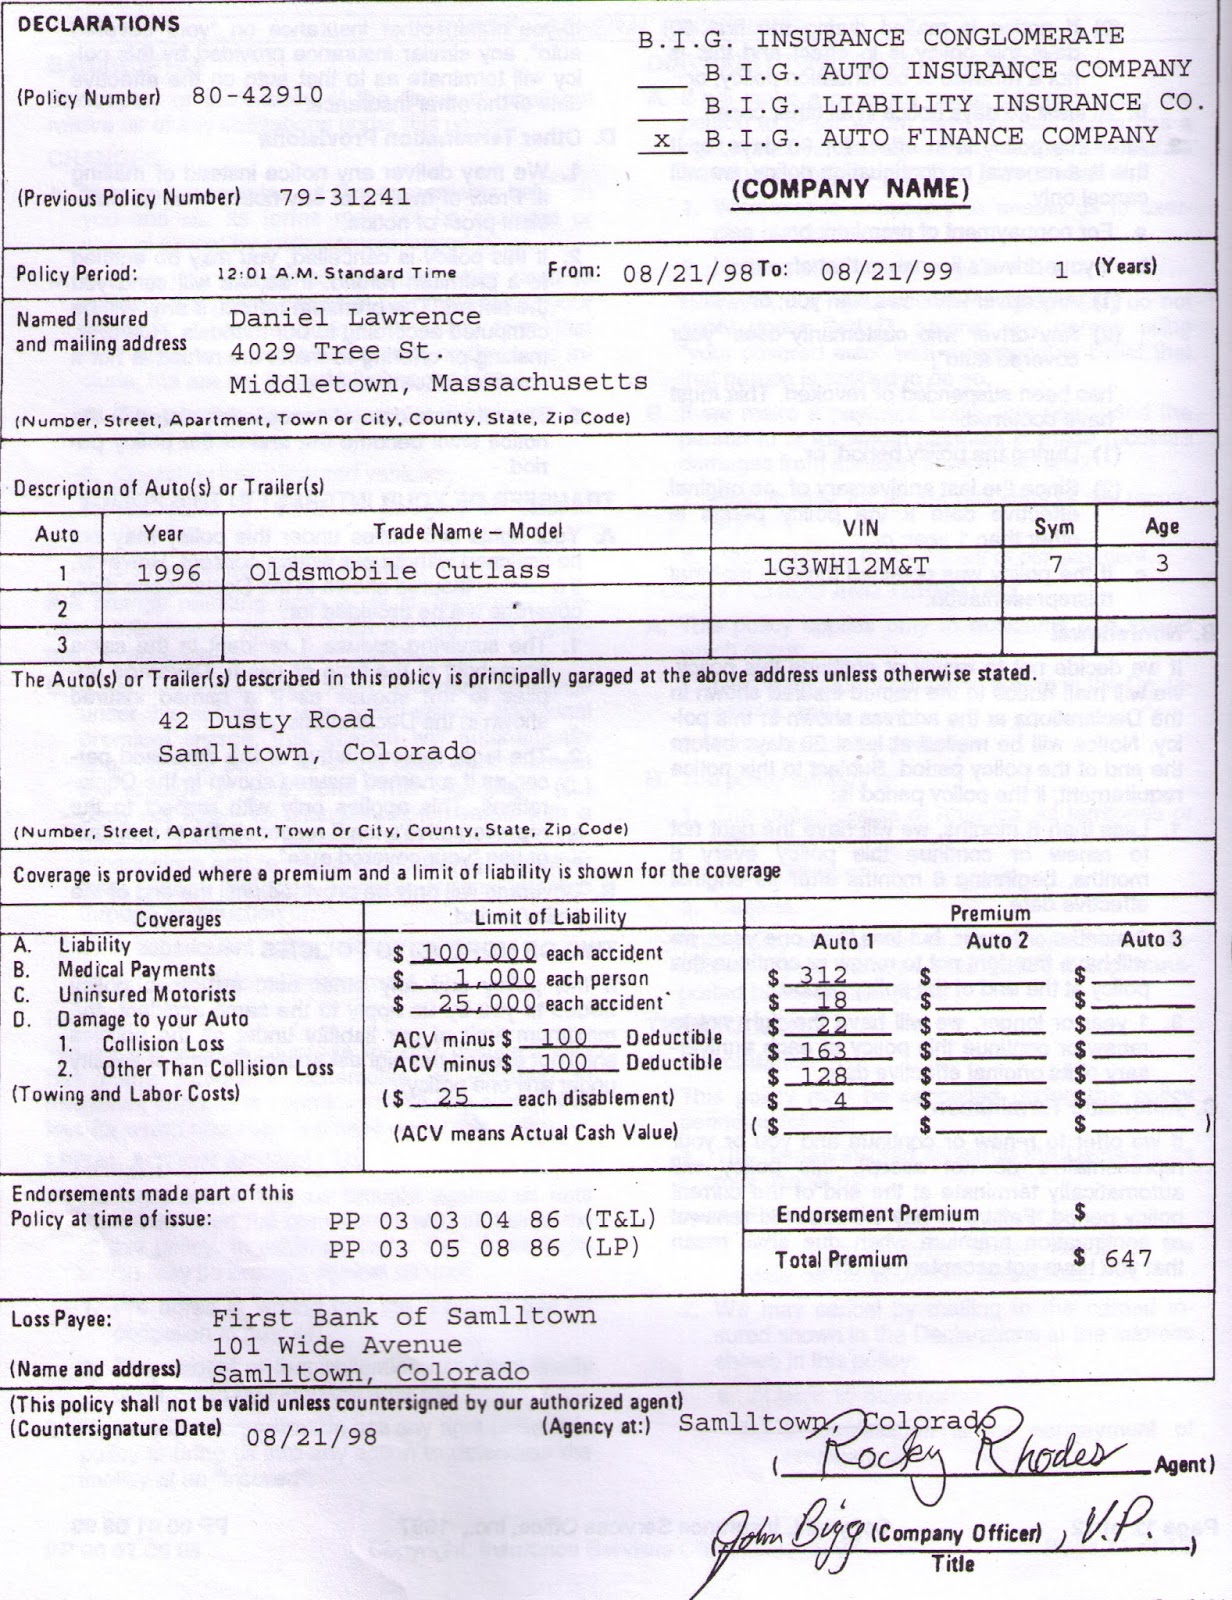
Policy Number vs. Other Insurance Identifiers
Drivers frequently confuse their auto insurance policy number with other alphanumeric codes found on their insurance documents. Using the wrong number can cause significant delays during claims processing or roadside verification. The table below outlines the key differences between these identifiers.
| Identifier Type | Primary Purpose | Where It Is Found | Who Uses It |
|---|---|---|---|
| Policy Number | Identifies the specific insurance contract and active coverage status. | Insurance ID Card, Dec Page, Billing Invoices. | Insurers, Law Enforcement, DMV, Policyholders. |
| Claim Number | Tracks a specific accident, damage report, or loss investigation. | Correspondence regarding an active accident claim. | Adjusters, Body Shops, Claimants, Policyholders. |
| Agency/Producer Code | Identifies the independent insurance agent or broker who sold the policy. | Top corner of policy documents or agency letterhead. | Insurance Carriers, Agents, Commission Trackers. |
| VIN (Vehicle Identification Number) | Uniquely identifies the physical motor vehicle itself (17 characters). | Vehicle dashboard, driver-side door jamb, vehicle title. | DMV, Police, Insurers, Mechanics. |
Why Your Policy Number Matters in Daily Operations
Beyond being a requirement for legal compliance, your auto insurance policy number is the fundamental key used by administrative systems to verify, process, and protect your interests.
Traffic Stops and Law Enforcement Verification
When a law enforcement officer pulls you over, they request your driver's license, vehicle registration, and proof of insurance. The officer inputs your policy number or insurance company details into state databases to verify that your liability coverage is active. If your policy has lapsed due to non-payment, an invalid or outdated policy number will immediately flag the record, potentially resulting in citation, vehicle towing, or license suspension depending on local statutes.
Accident Reporting and Claim Initiation
Following a motor vehicle collision, exchanging insurance information is standard practice. Providing the correct policy number to the other driver—and obtaining theirs—accelerates the claims process. When you contact your claims adjuster, reciting your policy number allows them to instantly pull up your coverage limits, deductible amounts, and optional coverages (such as roadside assistance or rental car reimbursement) without forcing you to explain your entire history from scratch.
Vehicle Registration and DMV Compliance
State Departments of Motor Vehicles increasingly utilize electronic verification systems (such as Insurance Verification Systems or IVP programs) to cross-reference registered vehicles with active insurance databases. When renewing your vehicle registration tags annually, the state DMV system queries insurance databases using your policy number and Vehicle Identification Number (VIN) to ensure mandatory financial responsibility laws are met. If a mismatch occurs, registration renewal can be blocked until proof of continuous coverage is established.
Common Mistakes and Troubleshooting
Mismanaging your auto insurance policy number can lead to administrative headaches. Being aware of frequent pitfalls helps you avoid coverage disputes and communication breakdowns with your provider.
Common Errors Made by Drivers
- Confusing Zeros and the Letter "O": Alphanumeric policy numbers often mix numbers and letters. Mistyping a zero for a capital letter in an online portal will result in login errors or system rejections.
- Using Expired Insurance Cards: Keeping an old insurance card in your glove box after renewing your policy means you are carrying an outdated policy number. Always discard old cards immediately upon receiving updated documentation.
- Mixing Up Multiple Vehicles: Multi-car households often have unique policy numbers for each vehicle or a single master policy number with individual sub-descriptions. Providing the wrong sub-number can delay claims handling for a specific vehicle.
Steps to Recover a Lost Policy Number
If you find yourself stranded on the roadside without your policy number or physical ID card, follow these steps to recover it quickly:
- Access Your Insurer's Mobile App: Even if you cannot find your paper card, logging into your insurer's app via cellular data will display your active digital card instantly.
- Call the Customer Service Hotline: Major insurance carriers maintain 24/7 roadside and claims hotlines. By providing your full legal name, date of birth, and Vehicle Identification Number (VIN), a representative can look up your policy number over the phone.
- Contact Your Independent Agent: If you purchased your policy through a local insurance agency, calling their office during business hours—or checking their mobile contact portal—will yield immediate assistance.
Best Practices for Managing Your Insurance Documentation
Maintaining organized records ensures that you are never caught unprepared during an emergency. Implementing a few straightforward digital and physical habits will streamline your interactions with insurers and regulatory bodies.
- Digitize Your Proof of Insurance: Download your insurer's mobile app and save a screenshot or PDF of your insurance card directly to your smartphone's photo gallery or digital wallet. This guarantees offline access even in areas with poor cellular service.
- Keep Your Contact Information Updated: Ensure your mailing address, email address, and phone number remain current with your insurance carrier. This prevents missed billing statements, renewal alerts, or cancellation notices.
- Review Your Declarations Page Annually: Take time each year to review your policy details, coverage limits, and deductibles to ensure they align with your current financial situation and driving habits.
Frequently Asked Questions
Can someone steal my identity if they have my auto insurance policy number?
An auto insurance policy number alone is generally not sufficient to steal your identity, as it does not contain sensitive financial data like your Social Security number or full banking credentials. However, it can expose your personal contact information, home address, and vehicle details. Treat your policy number with reasonable care and avoid sharing it publicly.
Is my policy number the same as my insurance ID card number?
In most cases, yes. The primary identifier printed on your insurance identification card is your active policy number. Some carriers may include a separate document tracking number for the physical card itself, but the policy number remains the primary contract identifier required for legal and administrative verification.
Will my policy number change when I renew my insurance policy?
Typically, no. Most insurance carriers keep the same policy number for the life of your customer relationship, appending a renewal suffix or simply updating the effective dates in their database. However, if you make major changes—such as switching underwriting companies within the same corporate group or rewriting a cancelled policy—you may be issued a brand-new number.
What should I do if my insurance card lists the wrong policy number?
Contact your insurance agent or carrier's customer service department immediately. Clerical errors during policy issuance or renewals can result in typographical mistakes on physical ID cards. Driving with incorrect documentation can cause complications during traffic stops or accident investigations until the carrier issues a corrected card.
Can I check if my auto insurance policy is active using only my policy number?
Yes. Law enforcement officers, DMV officials, and insurance verification representatives can use your policy number to query state and carrier databases to verify whether your policy is currently active, suspended, or cancelled.
Conclusion
Your auto insurance policy number is far more than a random sequence of letters and digits; it is the vital administrative link between you, your vehicle, your insurance provider, and regulatory authorities. By familiarizing yourself with where to find this number, understanding how it is structured, and keeping both physical and digital copies accessible, you protect yourself against roadside delays, registration blocks, and claims processing friction. Review your insurance documents today, ensure your digital wallet is up to date, and drive with the peace of mind that comes from total preparedness.
Image Gallery
Select an image to open it in a new tab.

Mateo Castillo
Decentralized Finance and E-Payments Strategist
