Navigating the Sample Letter to a Life Insurance Beneficiary: A Comprehensive Guide

When a policyholder passes away, the process of notifying beneficiaries often falls to the executor of the estate or the policy owner. Sending a formal, clear, and empathetic letter to a life insurance beneficiary is a vital step in initiating the claims process, ensuring the recipient understands their rights, and providing necessary administrative guidance during a difficult period. This documentation serves as a professional bridge between the financial institution and the individual who stands to receive the policy proceeds.
The Importance of Formal Notification
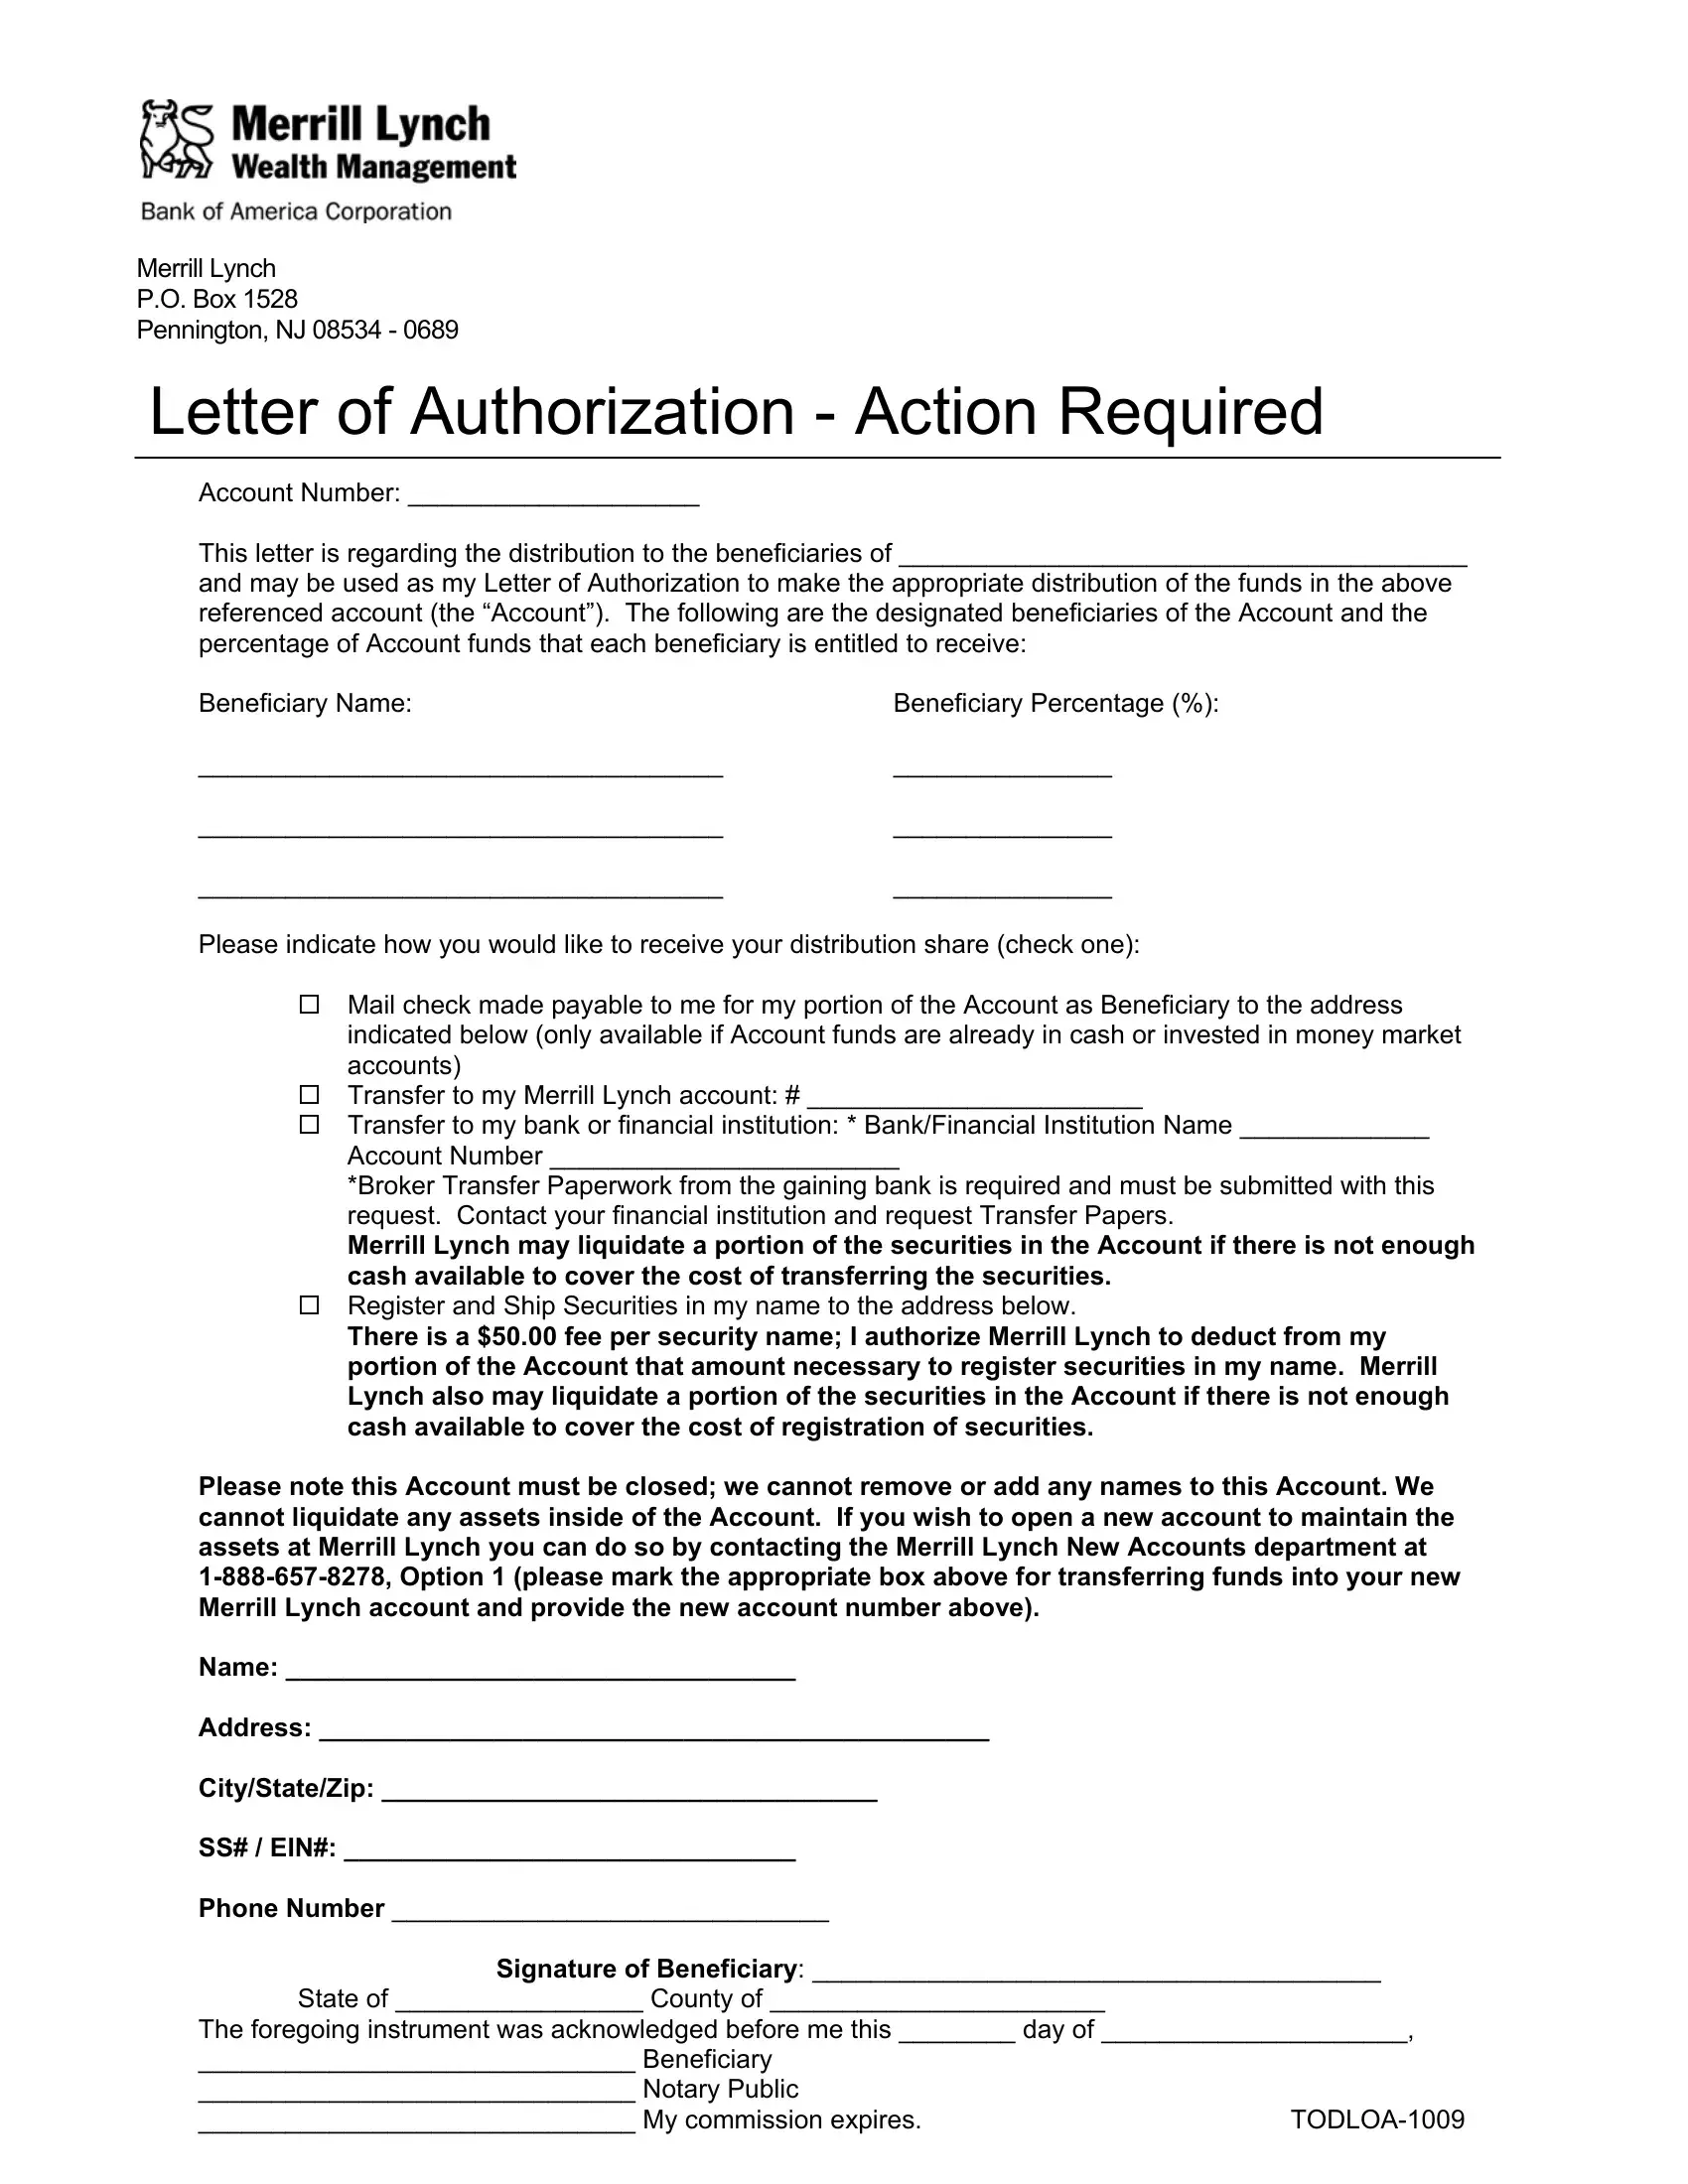
Life insurance claims are governed by specific legal and contractual frameworks. While insurance companies typically send their own official notices upon being notified of a death, a letter from an executor, trustee, or family member often arrives sooner and provides essential personal context. The primary intent of this communication is to provide clarity regarding the policy existence, the expected timeline for settlement, and the documentation the beneficiary will need to gather.
By formalizing the notification, you reduce the likelihood of miscommunication. Beneficiaries may be overwhelmed by grief or unfamiliar with financial terminology. A well-structured letter serves as a reference point they can return to when they have the mental bandwidth to process the requirements for filing a claim.
Key Components of an Informative Notification
A professional letter to a beneficiary should be concise but comprehensive. It is not intended to be a legal document that replaces the insurance company’s paperwork, but rather a guide to help the recipient take the next steps. Every effective letter should include the following core elements:
- Policy Identification: State the name of the insurance carrier, the policy number (if known), and the type of policy (e.g., term, whole life).
- Contact Information: Provide the details of the insurer’s claims department if you have them, or clear instructions on how the beneficiary can reach the company.
- Claim Requirements: List the documents usually required, such as an original certified death certificate, the policy document itself, and a claimant’s statement.
- Expectation Management: Briefly describe what happens next—typically the insurer will review the claim, verify the beneficiary’s identity, and process the payout.
- Professional Disclaimers: Clarify that you are providing this information for guidance and that the beneficiary must interact directly with the insurance provider to finalize the legal claim.
Developing the Content: A Structured Approach
When drafting your letter, maintain a tone that is professional yet compassionate. Avoid using overly dense legal jargon, as this can confuse a reader who is already managing significant stress.
Opening and Context
Begin with a brief expression of sympathy. Acknowledge that the letter is regarding the life insurance policy held by the deceased. This immediately sets the context so the beneficiary understands the nature of the correspondence before they dive into the financial details.
The Financial Details
Present the policy details clearly. If you have multiple policies or are communicating with multiple beneficiaries, be extremely precise about which policy relates to which beneficiary to avoid confusion. If you are the executor, note that you are fulfilling your duty to inform them of their potential entitlement.
Actionable Instructions
The middle section of the letter should focus on the "how-to." Do not assume the beneficiary has prior experience with insurance claims. Explain that they will likely need to contact the insurance company directly to request a "claim package."
| Document Type | Purpose in Claims Process |
|---|---|
| Certified Death Certificate | Official proof of death required by all carriers. |
| Policy Document | Assists the company in locating the account faster. |
| Claimant's Statement | The formal application form provided by the insurer. |
| Proof of Identity | Government-issued ID to verify the beneficiary. |
| Tax Forms (W-9) | Required for tax reporting on any interest earned. |
Understanding the Beneficiary’s Role
It is crucial to emphasize to the beneficiary that they hold the primary responsibility for initiating the claim. Insurance companies require the beneficiary to act because they must verify the identity and legal status of the person receiving the funds.
Explain that they should reach out to the insurance company via the company’s official claims department. Remind them to keep copies of all correspondence, including the date they contacted the insurer, the name of the representative they spoke with, and any reference numbers provided. This level of organization will be beneficial if there is a delay in the processing of the claim.
Legal and Financial Limitations
As a sender of this information, you must include a disclaimer that you are not providing legal or tax advice. Life insurance proceeds may have tax implications depending on the jurisdiction and the specific circumstances of the policy. Furthermore, some policies may have secondary beneficiaries, contingent clauses, or disputes regarding the status of the policy (e.g., if premiums were not paid).
If you are an executor or a trustee, ensure your letter does not commit the estate to any specific timeline. The insurance company's internal review—which includes a "contestability period" check—can vary in duration. Setting unrealistic expectations regarding when the funds will arrive can lead to frustration and potential legal friction later on.
Common Mistakes to Avoid
When writing to a beneficiary, simplicity is your best tool. Common pitfalls include:
- Providing outdated information: Ensure you are using current insurance contact details. If the policy is older, the company may have merged or been acquired.
- Assuming knowledge: Do not assume the beneficiary knows what a "certified" copy of a death certificate is or where to get one.
- Creating excessive urgency: While claim processing takes time, avoid making the process sound like a high-pressure deadline. This adds unnecessary anxiety to a difficult period.
- Including sensitive personal data: Avoid including full Social Security numbers or sensitive financial account numbers in a standard letter that might be intercepted. Keep the letter focused on the process, not the specific financial data.
Navigating the Claim Review Process
Once the beneficiary has been notified and has submitted their claim, the insurance company enters a validation phase. They will verify that the policy was in force at the time of death and that the beneficiary named on the policy matches the individual filing the claim.
In instances where the policy has been active for less than two years, the insurer may perform an investigation to ensure there were no material misrepresentations on the original application. This is a standard procedure and should be communicated to the beneficiary as a normal part of the process, rather than as a red flag, to ensure they do not become overly alarmed if the insurer asks for additional medical records or documentation.
The Role of Beneficiary Advocacy
Sometimes, beneficiaries may be incapacitated, elderly, or simply unable to navigate the administrative burden of filing a claim. If you have been appointed to assist them, your role is to facilitate the connection between the beneficiary and the insurer.
You can offer to help them organize the documents or provide them with the contact information for the insurer’s ombudsman if they encounter issues. However, always ensure that all sensitive submissions are handled by the beneficiary or their legal representative to protect privacy and adhere to the insurer's security protocols.
Addressing Unresolved Issues
Occasionally, a beneficiary may find that the insurance company denies a claim or requires further documentation that is impossible to retrieve. In such cases, the beneficiary should know their right to appeal. Encourage them to seek guidance from an attorney specializing in probate or insurance law if they feel that the claim process has hit an insurmountable barrier.
Providing a list of resources—such as the state department of insurance—can be a helpful final piece of information to include in your letter. These regulatory bodies often have consumer protection divisions that can assist beneficiaries who are struggling to get clear answers from insurance carriers.
Recommended Next Steps for the Sender
- Verify Policy Status: Before sending the letter, confirm through your own channels that the policy is indeed active and the beneficiary information is current.
- Draft a Professional Letter: Use the elements described in this guide to create a clear, empathetic, and informative document.
- Use Reliable Delivery: Send the notification via a traceable method if it contains sensitive but non-confidential information, or provide it via a secure, encrypted digital channel if both parties have consented to electronic communication.
- Maintain Records: Keep a copy of the letter you sent in your own files for the duration of the estate settlement process.
- Follow Up Gently: If you do not hear back within a reasonable timeframe, reach out to the beneficiary simply to ensure they received the information and to offer further assistance if needed.
By approaching the notification process with professional rigor and personal empathy, you ensure that the beneficiary is empowered to manage their financial affairs with confidence during a challenging transition. Clear communication is the most effective tool you can provide, setting the stage for a smooth and efficient resolution of the life insurance claim.
Frequently Asked Questions
Does a beneficiary need a lawyer to file a life insurance claim? No, in most cases, a lawyer is not required. The process is designed to be handled directly between the beneficiary and the insurance carrier. A lawyer is only typically necessary if the claim is contested, denied, or if there is a legal dispute regarding the beneficiary’s identity or rights.
What happens if the beneficiary has passed away before the policyholder? If a primary beneficiary has died, the insurance company will typically distribute the funds to the contingent beneficiaries listed on the policy. If no contingent beneficiaries are named, the proceeds often become part of the policyholder's estate, which then requires oversight by the executor according to the deceased’s will or state intestacy laws.
How long does it take for a life insurance company to pay out a claim? Timelines vary significantly based on the complexity of the policy and the insurer’s procedures. Once all required documentation is received and approved, many claims are settled within 30 to 60 days. Complex cases or those subject to contestability investigations may take several months.
Should I include a copy of the policy with the letter? It is helpful but not strictly necessary. If you have a copy of the policy, providing it can save the beneficiary time and help them identify the correct company contact details. Ensure that if you are mailing these documents, you use a secure method to protect the information contained within the policy.
What if the insurance company cannot be found? If a company has been acquired or has changed its name, you can search the National Association of Insurance Commissioners (NAIC) database or the state insurance department's website where the policy was originally issued. These resources are designed to help policyholders and beneficiaries locate the current entity responsible for outstanding policies.

Image Gallery
Select an image to open it in a new tab.



Zara El-Hashem
Sociocultural Dynamics and Academics Writer
