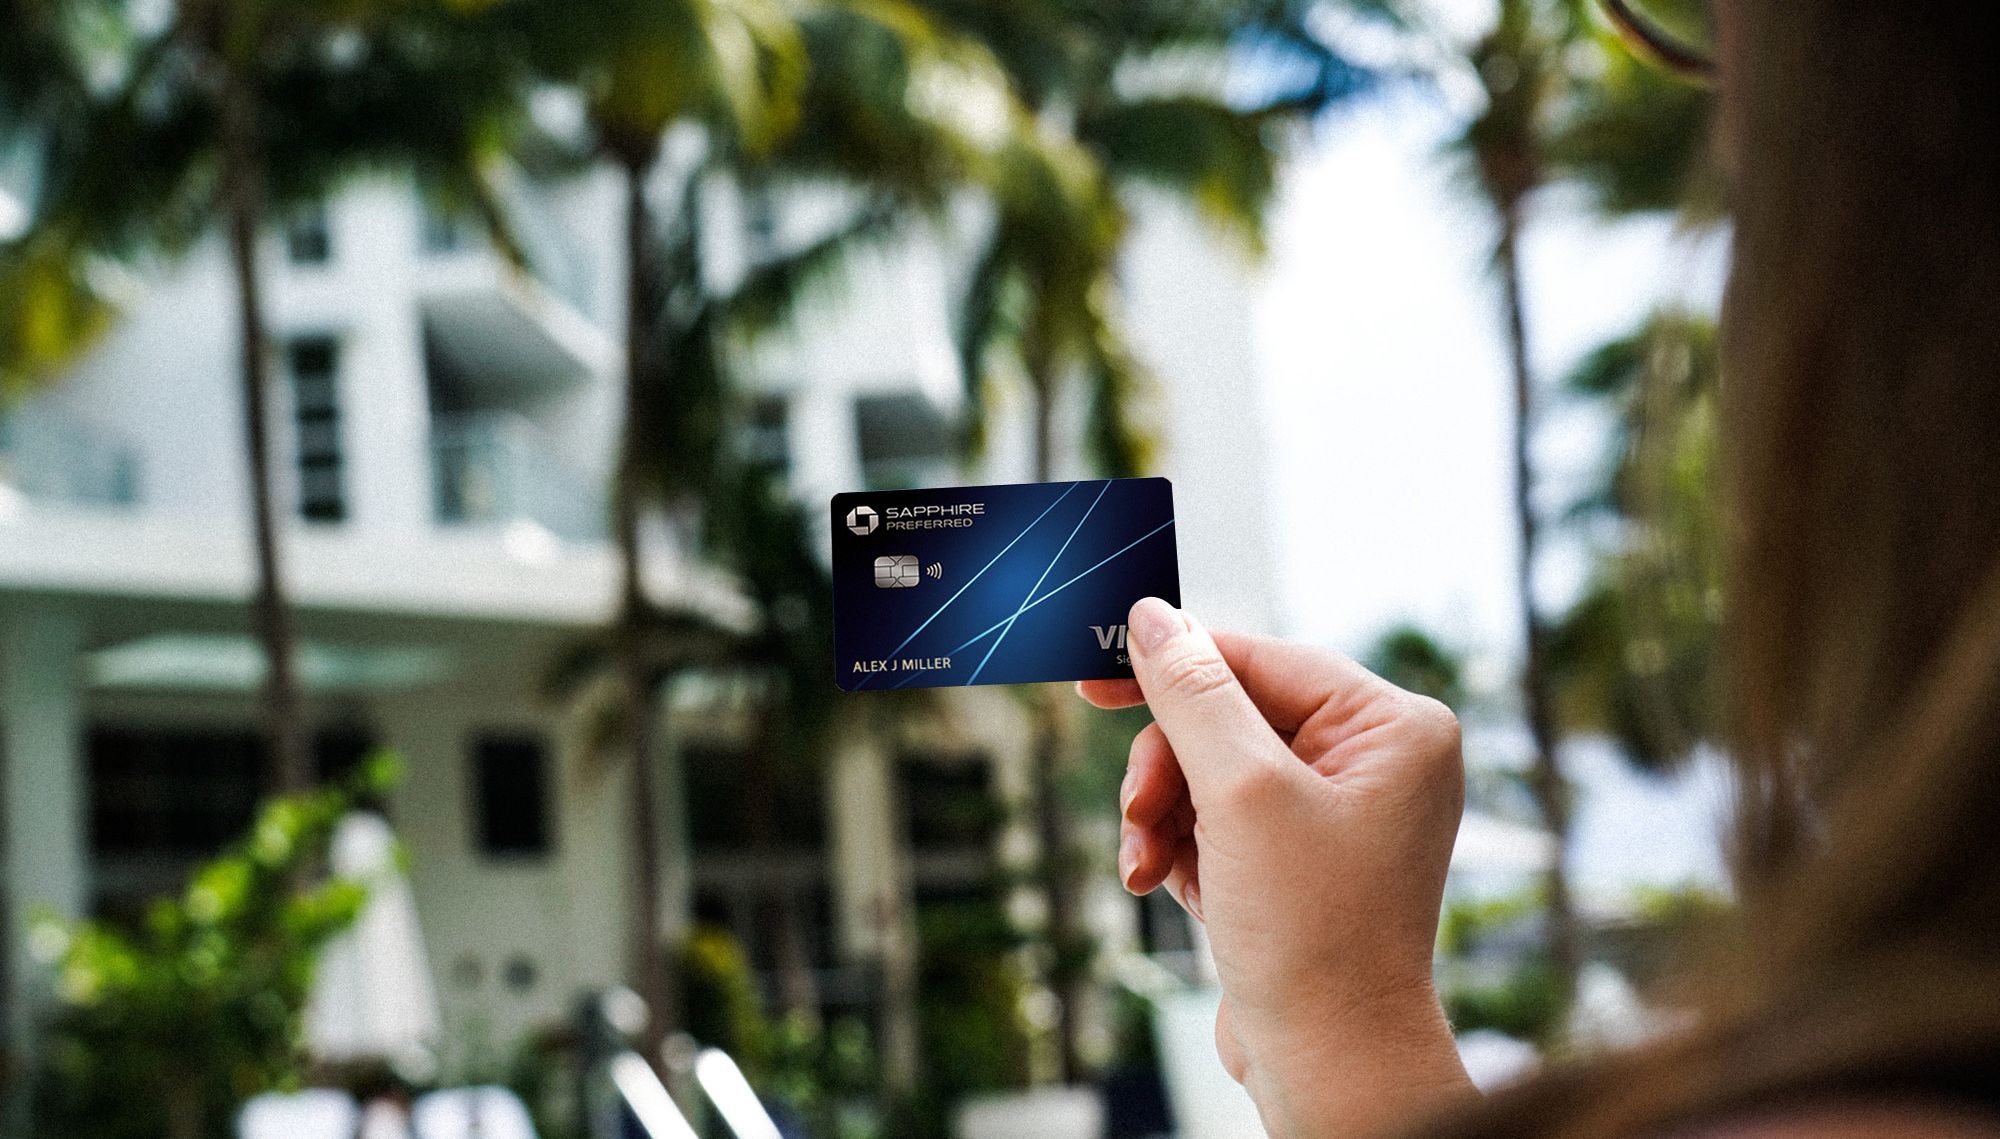
Chase Sapphire cardholders receive primary auto rental collision damage waiver (CDW) benefits when they use their card to initiate and pay for a rental agreement. This coverage acts as primary insurance, meaning it applies before your personal auto insurance policy, helping you avoid out-of-pocket expenses and potential premium increases following a covered theft or damage incident.
Understanding Primary vs. Secondary Rental Coverage
To effectively utilize the benefits provided by your Chase Sapphire Preferred or Sapphire Reserve card, you must first understand the fundamental difference between "primary" and "secondary" rental insurance. Most standard credit cards provide secondary coverage. In a secondary coverage scenario, you are required to file a claim with your personal auto insurance provider first. The credit card issuer only covers the remaining balance, such as your personal insurance deductible or damages that exceed your policy limits.
Primary coverage, which is a hallmark benefit of the Chase Sapphire line, bypasses this step entirely. If your rental vehicle is stolen or damaged, the Chase benefit provider processes the claim as the first line of defense. This is particularly advantageous because it prevents your personal auto insurance premiums from rising due to a claim involving a rental vehicle. Because the process is handled directly by the benefit administrator, you are often spared the administrative burden of coordinating between the rental agency and your personal insurer.
Eligibility and Prerequisites for Coverage
Accessing this benefit requires more than just holding the card in your wallet. The terms of the Chase Sapphire auto rental coverage are strict regarding how the transaction is initiated and completed.
- Payment Initiation: You must charge the entire cost of the rental transaction to your Chase Sapphire card. This includes the initial reservation and the final settlement at the return desk. If you use points to pay for the rental, the taxes and fees must still be charged to the card to qualify.
- Decline the Agency’s CDW: To ensure the Chase benefit remains primary, you must explicitly decline the rental company’s Collision Damage Waiver (CDW) or Loss Damage Waiver (LDW). If you accept the rental company’s insurance, you have effectively negated the primary nature of the Chase benefit, and the credit card coverage will generally not apply or will revert to a secondary position.
- Cardholder Responsibility: The cardholder must be the primary renter listed on the rental agreement. While additional drivers are typically covered if they are also listed on the rental agreement, the primary responsibility for the transaction remains with the Sapphire cardholder.
Geographical and Vehicle Limitations
While the benefit is expansive, it is not universal. It is essential to verify if your specific travel destination and vehicle type are covered before arriving at the rental counter.
- Excluded Countries: Coverage typically does not apply in countries where it is prohibited by law or where the rental company’s own insurance is mandatory. Always check the current list of exclusions in your Guide to Benefits, as certain nations (such as Ireland, Israel, or Jamaica) may have specific regulatory environments that preclude the use of credit card waivers.
- Excluded Vehicles: High-value, exotic, or specialized vehicles are frequently excluded from coverage. This category often includes antique cars, motorcycles, recreational vehicles (RVs), trucks with an open cargo bed, and certain luxury brands that exceed the maximum vehicle value threshold defined by the benefit administrator.
- Rental Duration: Most standard policies limit coverage to a specific number of consecutive days—often 31 days. If you are planning an extended rental period, you may need to arrange for supplemental commercial insurance.
Comparing Chase Sapphire Rental Benefits
The following table summarizes the core components of the rental coverage for Sapphire cardholders.
| Feature | Chase Sapphire Preferred | Chase Sapphire Reserve |
|---|---|---|
| Coverage Type | Primary | Primary |
| Max Coverage Amount | Actual Cash Value (up to limit) | Actual Cash Value (up to $75,000) |
| Theft/Damage | Included | Included |
| Loss of Use | Covered | Covered |
| Towing/Storage | Covered | Covered |
| Primary Requirement | Decline Agency CDW | Decline Agency CDW |
The Claims Process: Steps to Success
In the event of an accident or theft, immediate action is required to ensure your claim is eligible for reimbursement. The documentation process is rigorous, and failure to provide specific items can lead to a denial of coverage.
- Notify the Agency: Immediately report the incident to the rental company. Obtain a copy of the accident report or the incident document provided by the rental agency.
- Contact the Benefit Administrator: You must notify the Chase benefit administrator within a specific window—typically 60 days of the incident—to open a claim. Delaying this notification can jeopardize your eligibility.
- Document Everything: Gather all necessary paperwork. This includes the original rental agreement, the itemized repair bill from the rental company, the police report (if applicable), and the statement of charges from your Chase account showing the rental payment.
- Cooperation: Provide all information requested by the claim investigator. They will determine the "actual cash value" of the vehicle and assess the validity of the damages being claimed by the rental company.
Common Mistakes and Troubleshooting
The most frequent cause for claim denial is failure to properly "decline" the waiver. If the rental desk agent adds a charge for "LDW" or "CDW" to your bill because they insist it is mandatory, you must clarify that you are waiving it. If they force you to take it, call the number on the back of your card while at the counter to verify if the rental is still eligible or if you should seek an alternative rental provider.
Another common pitfall is the "Loss of Use" charge. Rental agencies often charge the cardholder for the time the vehicle is in the shop and cannot be rented to others. While Chase covers this, you must ensure the rental company provides a formal breakdown of these charges, as they are not always included in the initial damage estimate.
Practical Expert Advice
Before you travel, download the most recent version of your "Guide to Benefits" specific to your card. Benefit terms can be updated by the issuer periodically, and the specific limitations on vehicle types or countries can shift. Additionally, keep a digital or physical copy of the benefit summary with you during your trip. If you are questioned at the rental counter, having the document available to show the agent can help clarify that you have sufficient coverage and do not require their secondary insurance products.
Disclaimer: This information is for educational purposes and does not constitute professional legal or financial advice. Coverage is subject to the terms, conditions, and exclusions of your specific card member agreement. Always review the official Guide to Benefits provided by JPMorgan Chase for the most accurate and current information regarding your specific account.
Frequently Asked Questions
Does the primary coverage apply to liability insurance? No. Chase Sapphire primary auto insurance covers only physical damage to or theft of the rental vehicle itself. It does not provide liability coverage for bodily injury or property damage to third parties. You must ensure you have separate liability coverage through your personal auto insurance or by purchasing it from the rental agency.
Can I use this benefit if I rent a car through a third-party site? Yes, as long as the entire rental transaction is charged to your Chase Sapphire card. The key requirement is that the rental contract is in your name and you have paid for it using the eligible card.
What happens if the rental company claims the damage was pre-existing? Always conduct a thorough walk-around of the vehicle before leaving the lot. Take high-resolution photos or videos of the car’s condition, including any existing scratches or dents. If you are blamed for pre-existing damage, having timestamped evidence is your primary defense during the claim process.
Is it possible to use this benefit for luxury vehicle rentals? Most standard Sapphire policies have a limit on the total value of the vehicle, often set at $75,000. If you are renting a vehicle that exceeds this value—such as a high-end exotic sports car—the coverage may not apply to the full cost of the vehicle. Always confirm the specific vehicle valuation limits before booking.
How do I get a benefit letter for international rentals? If you are traveling to a country that requires proof of insurance, you can request a "Letter of Coverage" through the Chase online portal or by calling the benefits administrator number found on the back of your card. This document serves as official proof that you possess primary collision damage waiver benefits.
Final Recommendation
To maximize your protection, always ensure that your Chase Sapphire card is the only form of payment used for the entire duration of the rental. Before you leave the rental lot, verify that the Collision Damage Waiver has been formally declined on your contract. For the most secure experience, maintain a digital folder containing your rental agreement, photos of the vehicle’s condition upon pickup, and the emergency contact number for your benefits administrator. By treating your rental agreement with the same diligence as your travel bookings, you ensure that the primary auto insurance benefit functions exactly as intended, protecting your wallet from unforeseen damage costs.

Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
