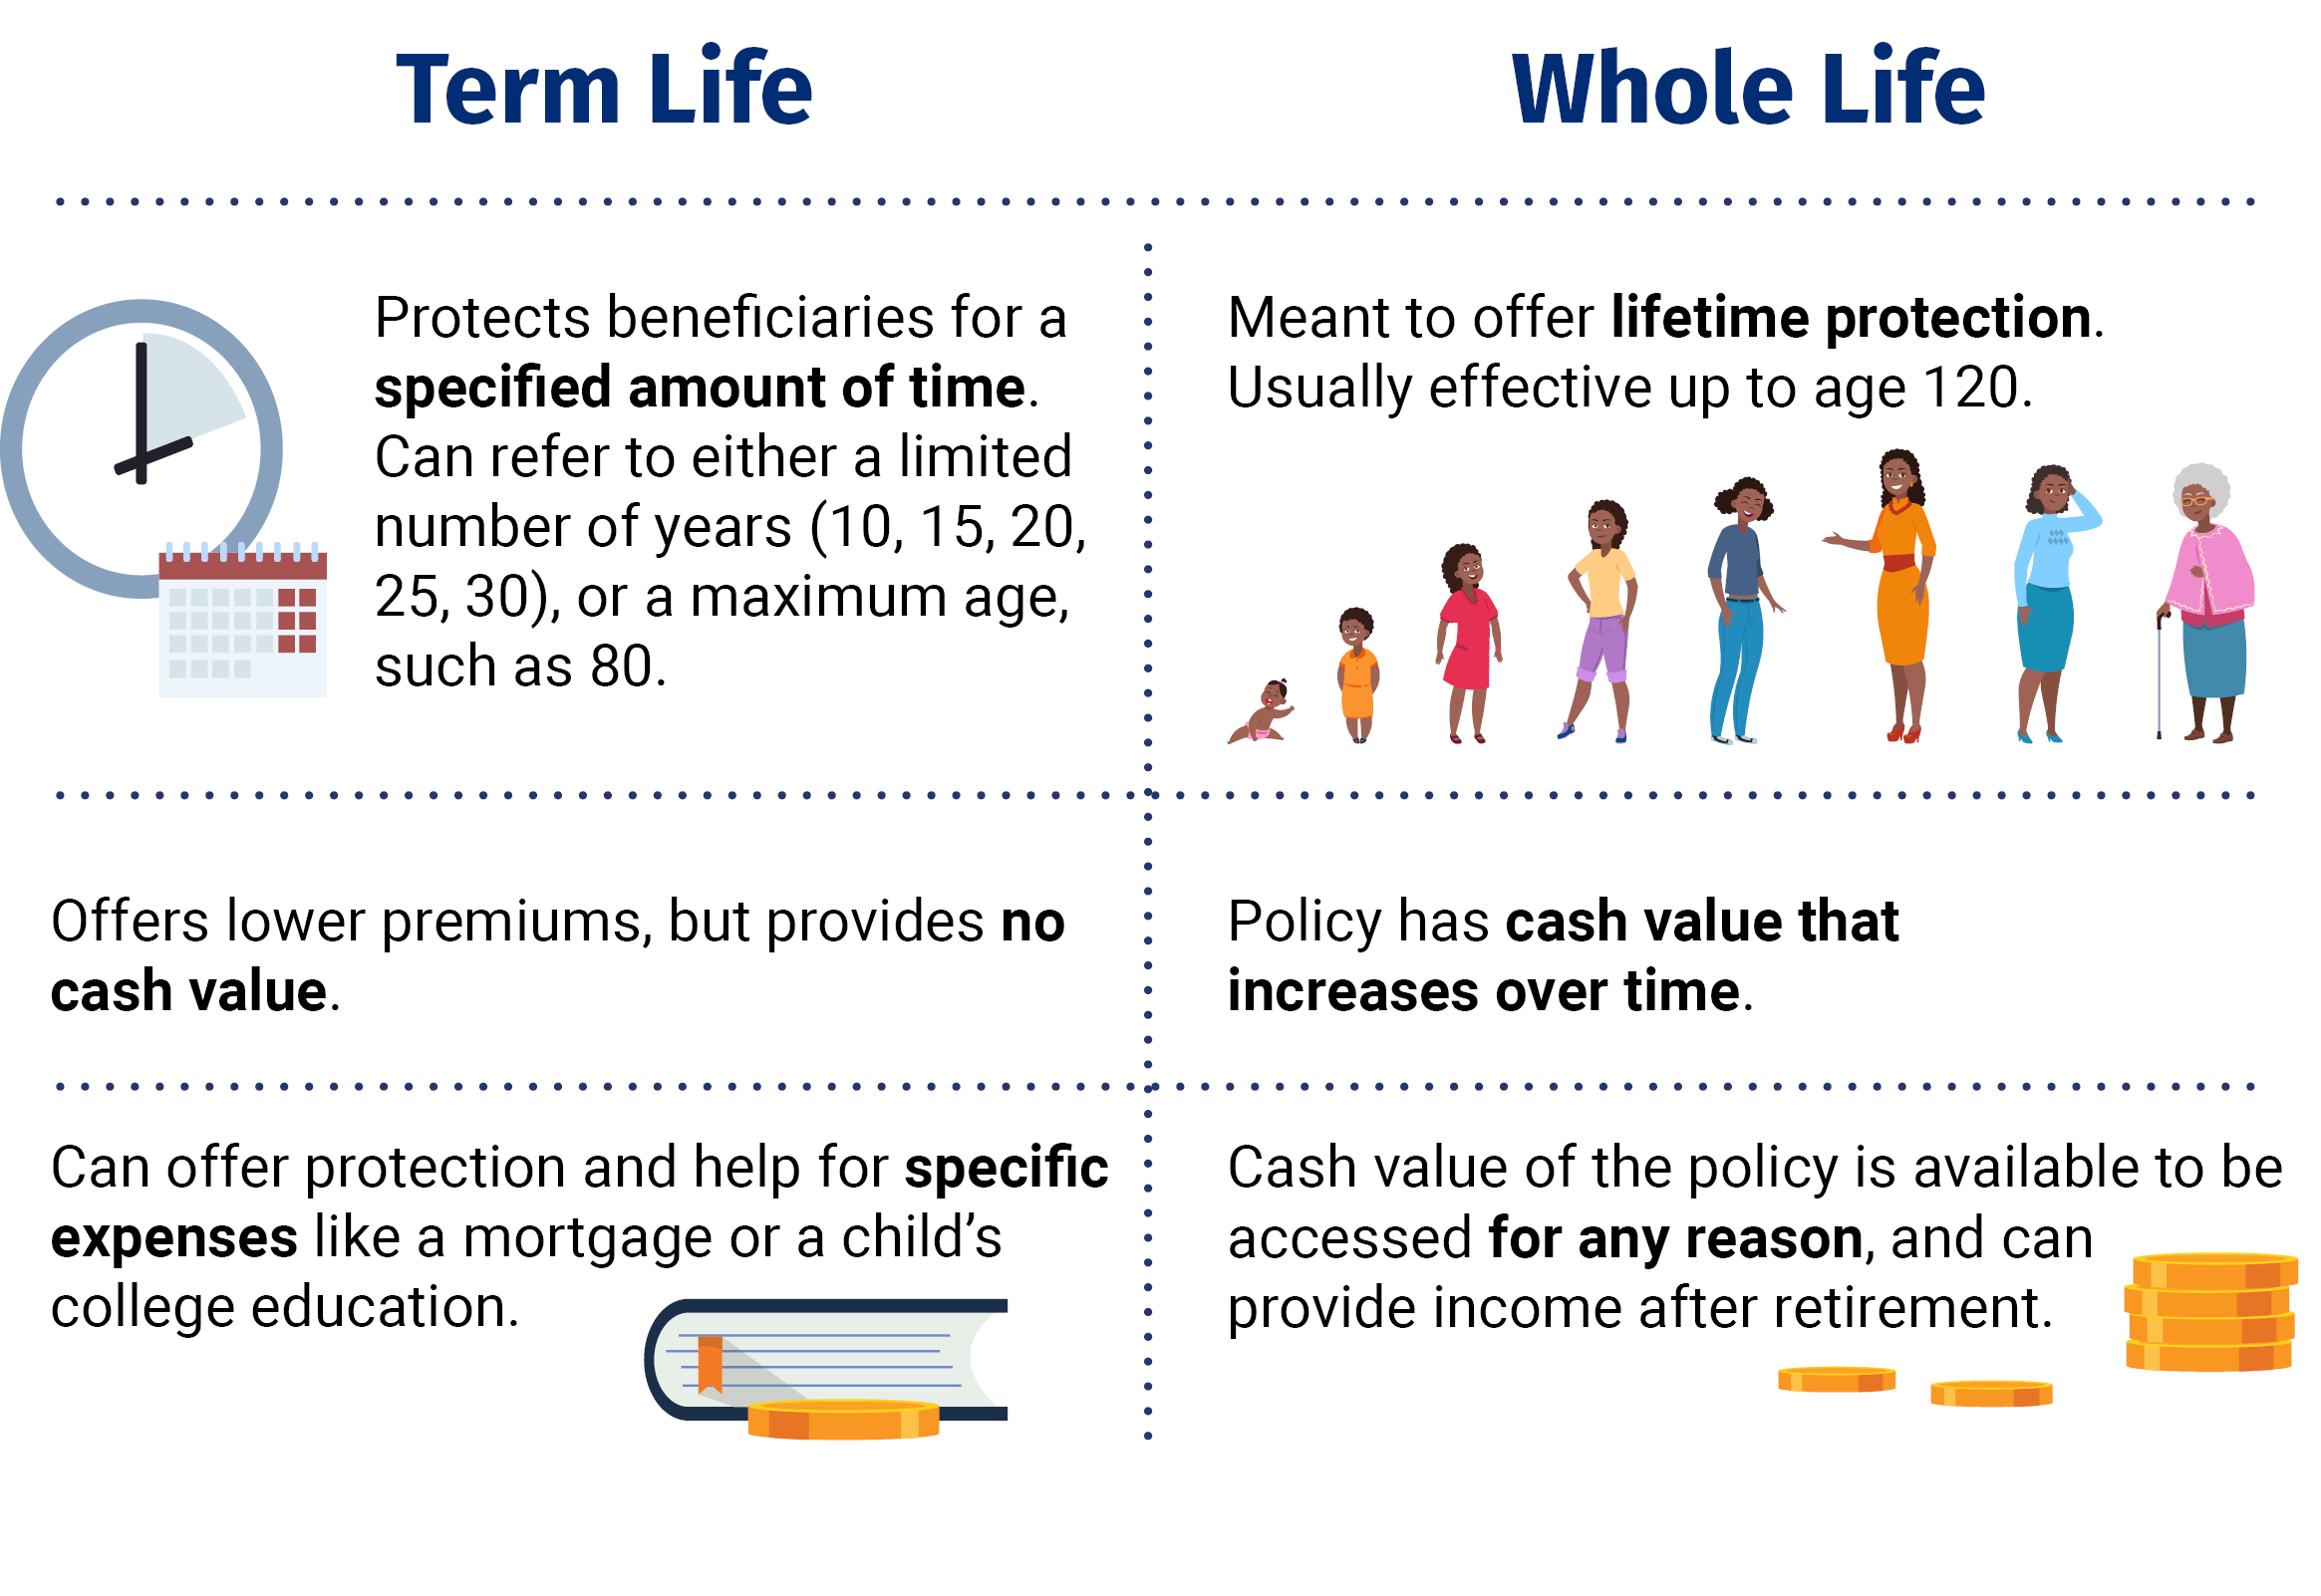
To get instant whole life insurance quotes, visit a reputable comparison website or a direct carrier’s digital portal. By entering your age, health data, and desired coverage amount, you can receive real-time premium estimates. In 2026, many providers use automated underwriting to offer firm, binding quotes online within minutes without requiring a medical exam.
Understanding the Instant Quote Landscape in 2026
The process of securing life insurance has undergone a significant transformation. In 2026, the traditional weeks-long underwriting process is no longer the only path to permanent coverage. Whole life insurance, known for its lifelong protection and cash value accumulation, is now accessible through sophisticated digital interfaces that provide immediate feedback.
When searching for "instant" quotes, it is vital to distinguish between a preliminary estimate and a firm offer. A preliminary estimate is a "ballpark" figure based on basic demographic data like age, gender, and tobacco use. A firm offer (or binding quote) is generated through "accelerated underwriting," where the insurance company's AI-driven systems verify your health history in real-time using third-party databases.
In the current 2026 market, the ability to get these quotes instantly is facilitated by the widespread integration of Electronic Health Records (EHR) and the MIB Group (formerly the Medical Information Bureau) data. This allows carriers to assess risk without the "needle and cup"—the traditional paramedical exam involving blood and urine samples. However, while the quote may be instant, the depth of the policy's financial structure remains complex, requiring a careful look at dividend projections and cash value growth.
Essential Information Required for an Accurate Online Quote
To ensure the "instant" quote you receive is accurate and not subject to drastic changes during the final application phase, you must have specific information ready. Accuracy at the entry stage prevents "premium shock," where the final price is significantly higher than the initial estimate.
Personal Identity and Demographic Data
Standard identity verification is the first step. You will need to provide your full name, date of birth, and social security number. In 2026, many portals use your SSN to pull "soft credit" reports and public records instantly. Your location is also critical, as insurance products are regulated at the state level, and certain whole life products or riders may not be available in all jurisdictions.
Comprehensive Health and Lifestyle History
This is the core of the underwriting engine. You should be prepared to answer detailed questions regarding:
- Medical Diagnoses: Recent surgeries, chronic conditions like diabetes or hypertension, and any history of cancer or heart disease.
- Prescription History: Digital quote engines often cross-reference your data with pharmaceutical databases to verify health claims.
- Family History: History of hereditary conditions in immediate family members (parents and siblings) before the age of 60.
- Lifestyle Choices: Tobacco or nicotine use (including vaping), alcohol consumption, and high-risk hobbies like SCUBA diving or private piloting.
Financial Details and Coverage Needs
Whole life insurance is often used as a financial tool rather than just a death benefit. You will need to determine the face amount (the death benefit) and how much you intend to pay in premiums. Since whole life premiums are fixed for life, deciding whether you want a "10-pay" (paid up in 10 years) or a "pay-to-age-100" structure will drastically change the instant quote results.
The Step-by-Step Process to Getting Quotes Instantly
Obtaining a quote involves a logical progression through a digital "funnel." Following these steps ensures you compare apples to apples when looking at different carriers.
Step 1: Selecting a Comparison Tool or Direct Carrier
You have two primary routes. You can use an aggregator site, which allows you to view multiple quotes from different companies side-by-side. Alternatively, you can go to a direct carrier's website (e.g., a major mutual insurance company). Aggregators are better for price discovery, while direct sites often provide more nuanced details on specific policy riders and cash value performance.
Step 2: Inputting Core Data and Policy Preferences
Enter your basic demographics and select the "Whole Life" option. Be careful not to confuse this with "Term Life" or "Universal Life." Ensure you select the correct death benefit amount. In 2026, most online "instant" whole life policies cap coverage at around $1,000,000 to $2,000,000 for no-exam options. If you require more coverage, the "instant" portion of the quote may remain an estimate until a full medical review is completed.
Step 3: Reviewing Initial Estimates and Adjusting Riders
Once the system generates quotes, look beyond the monthly premium. In 2026, digital portals allow you to toggle various riders (add-ons) to see how they affect the price in real-time. Common riders include:
- Waiver of Premium: Pays your premiums if you become totally disabled.
- Accelerated Death Benefit: Allows you to access a portion of the death benefit if diagnosed with a terminal illness.
- Guaranteed Insurability: Allows you to buy more coverage later without a medical exam.
Technical Depth: How Instant Underwriting Works
The technology behind the "instant" label is what makes the 2026 insurance market function. When you submit your information, the carrier's API (Application Programming Interface) connects to several data providers.
First, the MIB Group database is checked. This contains records of any previous life insurance applications you have made and the findings from those applications. Second, prescription drug databases (like Milliman IntelliScript) are queried to see what medications have been prescribed to you over the last 7 to 10 years. Third, Motor Vehicle Records (MVR) are pulled to check for DUI/DWI offenses or reckless driving, which are major indicators of mortality risk.
If your data "clears" these automated hurdles and fits within the company's preferred risk profile, the algorithm approves you instantly. If there is a discrepancy—for example, if you claim to be a non-smoker but the database shows a prescription for smoking cessation—the system will "flag" the application for a human underwriter, and the "instant" nature of the quote will transition into a standard manual review.
Comparison Table: Online Quote Methods and Accuracy
The following table outlines the different ways to obtain whole life quotes online in 2026 and what you can expect from each.
| Method | Speed | Accuracy | Best For | Verification Level |
|---|---|---|---|---|
| Quick Quote Tools | < 1 Minute | Low (Estimate Only) | Initial Budgeting | None; self-reported data only. |
| Comparison Aggregators | 2–5 Minutes | Moderate | Price Shopping | Soft credit pull; MIB check. |
| Direct Carrier (No-Exam) | 5–15 Minutes | High (Binding) | Speed and Convenience | Full EHR and Rx database query. |
| Captive Agent Portals | Variable | Very High | Complex Financial Planning | Full data integration + agent review. |
Pros and Cons of Online Whole Life Quotes
While the convenience of getting a quote from your smartphone is undeniable, there are trade-offs to consider, especially with a permanent product like whole life insurance.
Pros
- Efficiency: You can skip the traditional 45-day underwriting period.
- Transparency: You can see how different coverage amounts and riders impact the cost without feeling pressure from a salesperson.
- Privacy: Initial quote tools allow you to explore options anonymously before committing your SSN or medical history.
- Availability: Online tools are accessible 24/7, making it easier for those with non-traditional work schedules.
Cons
- Limited Customization: Complex "blended" whole life policies (which mix term and whole life to lower costs) are often not available through simplified instant quote tools.
- Higher Costs for Speed: "No-exam" instant policies may carry a slightly higher premium than fully underwritten ones because the insurance company takes on more "unknown" risk.
- Data Security: Providing sensitive health and identity data to multiple quote engines increases your digital footprint and potential exposure to data breaches.
Common Mistakes to Avoid When Seeking Online Quotes
The most frequent error is underestimating health issues. Many people believe that because a condition is "controlled" (like high blood pressure with medication), they should list themselves as being in "Preferred Plus" health. However, the presence of medication usually disqualifies you from the top-tier rate, leading to an inaccurate instant quote.
Another mistake is ignoring the financial strength of the carrier. An instant quote from a company with a poor "B" rating from A.M. Best is less valuable than a slightly higher quote from an "A++" rated carrier. Whole life insurance is a multi-decade commitment; the company must be solvent enough to pay the death benefit 40 or 50 years from now.
Finally, do not overlook the dividend history of mutual companies. Online quote tools often focus on the premium and the guaranteed cash value. However, many whole life policies are "participating," meaning they pay dividends. While dividends are not guaranteed, a company’s historical performance in paying them is a critical factor in the long-term value of the policy that a simple "instant quote" might not highlight.
Frequently Asked Questions
Can I get a whole life quote without giving my Social Security Number?
Yes, you can receive a preliminary estimate without an SSN on most aggregator sites. However, to receive a "firm" or "instant" quote that is binding, the carrier will eventually require your SSN to verify your medical and prescription history through authorized databases.
Is "Instant Whole Life" the same as "Guaranteed Issue"?
No. Instant whole life usually involves "accelerated underwriting," where you must still meet health requirements, but they are checked digitally and quickly. "Guaranteed Issue" involves no health questions at all but is typically much more expensive and has lower coverage limits, often designed for final expenses for seniors.
Does getting an online quote affect my credit score?
Getting a life insurance quote involves a "soft pull" of your credit report, which does not impact your credit score. Insurance companies use this data to verify your identity and look for financial stability, but it is not the same as a "hard inquiry" used for a loan or credit card application.
Why is my instant quote higher than the one I saw in an advertisement?
Advertised rates are usually "starting at" prices for the youngest, healthiest individuals in the "Preferred Plus" category. If you have any minor health issues, are older, or live in a state with higher insurance taxes, your personalized instant quote will be higher than the teaser rate.
How do I know if an online insurance site is legitimate?
Verify that the site is a licensed insurance agency. Legitimate sites will provide their license numbers (often in the footer) and will be affiliated with recognized carriers. You can verify a company's standing through the National Association of Insurance Commissioners (NAIC).
Practical Recommendation
When seeking instant whole life insurance quotes in 2026, the most effective strategy is to start with a broad comparison tool to establish a baseline for your age and health class. Once you have a target price, visit the direct portal of a highly-rated mutual insurance company to see if their dividend-paying products offer better long-term value. Always read the "Illustration" (the document showing projected cash values) before making your first premium payment, as this provides a clearer picture of the policy's performance than a simple quote screen.
Image Gallery
Select an image to open it in a new tab.

Mateo Castillo
Decentralized Finance and E-Payments Strategist
