Finding the Right Premium Life Insurance Company: A Comprehensive Guide for 2026
Finding the right premium life insurance company requires evaluating financial strength ratings, historical dividend performance, and specialized product offerings like Private Placement Life Insurance (PPLI). In 2026, the ideal carrier must demonstrate long-term solvency through high A.M. Best scores and offer flexible, high-limit death benefits tailored for estate liquidity and tax-advantaged wealth transfer.
Defining the "Premium" Life Insurance Landscape
In the context of 2026 financial planning, "premium" life insurance does not merely refer to the cost of the policy; rather, it identifies high-limit coverage and elite-tier carriers that cater to high-net-worth individuals (HNWIs) and ultra-high-net-worth individuals (UHNWIs). These policies typically involve death benefits starting at $5 million and can extend into the hundreds of millions. Selecting a carrier in this space involves more than a simple premium comparison; it requires a deep dive into the company’s institutional stability and its ability to honor claims decades into the future.
The premium market is dominated by two types of entities: mutual insurance companies and stock insurance companies. Mutual companies, such as Northwestern Mutual or MassMutual, are owned by their policyholders. This structure often aligns the company’s long-term interests with those of the insured, frequently resulting in the payout of annual dividends. Stock companies, such as Prudential or Lincoln Financial, are owned by shareholders and may prioritize quarterly earnings, though they often offer more aggressive or innovative universal life products. Understanding this distinction is the first step in identifying which institutional philosophy aligns with your financial goals.
Critical Criteria for Evaluating Top-Tier Carriers
When your financial legacy is at stake, you cannot rely on brand recognition alone. The "right" company must meet rigorous technical benchmarks that verify its ability to manage massive tranches of capital through various economic cycles, including the inflationary periods and market shifts observed leading up to 2026.
Financial Strength Ratings and the Comdex Score
The primary tool for verification is the financial strength rating provided by independent agencies. A premium carrier should ideally hold "Superior" or "Excellent" ratings from at least three of the major four agencies:
- A.M. Best: Focuses specifically on the insurance industry’s ability to pay claims. Look for A+ or A++ ratings.
- Standard & Poor’s (S&P): Evaluates the overall financial might and creditworthiness of the insurer. Look for AA- or higher.
- Moody’s: Assesses the credit risk and long-term stability. Look for Aa3 or higher.
- Fitch: Provides an additional layer of credit analysis.
A more streamlined metric often used by senior advisors is the Comdex Ranking. The Comdex is not a rating itself but a composite score (on a scale of 1 to 100) that averages the ratings from all the major agencies. For a premium policy, you should generally target companies with a Comdex score of 90 or higher.
Historical Dividend Performance
For those seeking participating whole life insurance, the dividend interest rate (DIR) is a vital metric. While dividends are never guaranteed, a company’s track record over the last 20 to 50 years provides a "stress test" of their management. The right company is one that has consistently paid dividends through the 2008 financial crisis, the 2020 pandemic, and the interest rate volatility of the early 2020s. In 2026, look for carriers that have maintained a stable dividend scale even as bond yields fluctuated.
Underwriting Sophistication for Complex Cases
Premium applicants often have complex medical histories or unique lifestyle risks (such as private aviation or international business travel). The right carrier for you is often the one whose underwriting department has a "niche" for your specific profile. Some companies are more "liberal" with cardiovascular history, while others specialize in "jumbo" cases where reinsurance is required to cover a $50 million+ death benefit.

Strategic Policy Structures for High-Value Coverage
Choosing a company also depends on which products they excel at. Not every top-rated carrier offers the best version of every policy type. Your choice should be dictated by the primary intent of the coverage: estate tax liquidity, cash value accumulation, or executive benefits.
Participating Whole Life
This is the "gold standard" for stability. Premium whole life provides a guaranteed death benefit, guaranteed level premiums, and a guaranteed increase in cash value. High-net-worth individuals often use these policies as a "volatility buffer" in their portfolios. If your goal is a conservative, non-correlated asset class, look for mutual companies with the highest Comdex scores.
Indexed Universal Life (IUL) and Variable Universal Life (VUL)
If you are seeking higher growth potential, IULs and VULs allow the policy’s cash value to be linked to market indices or sub-accounts. In 2026, the "right" IUL company is one that offers transparent "participation rates" and "caps" without a history of frequent internal cost-of-insurance (COI) increases. VULs, meanwhile, require a carrier with a robust platform of investment options managed by reputable third-party fund managers.
Private Placement Life Insurance (PPLI)
For the ultra-wealthy, PPLI offers a highly customized, institutional-pricing structure. PPLI is often "unbundled," meaning the investment management is separated from the insurance coverage. Only a handful of specialized premium companies (often domestic branches of global firms or specialized boutique carriers) handle PPLI. This requires a carrier with a sophisticated legal and compliance framework to ensure the policy meets IRS Section 7702 standards for tax-free growth.
2026 Comparison of Leading Premium Life Insurance Carriers
The following table compares key metrics for prominent carriers in the 2026 premium market. Note that these figures represent institutional averages and historical performance.
| Carrier Name | Ownership Structure | A.M. Best Rating | Comdex Score | Primary Strength | Best For |
|---|---|---|---|---|---|
| Northwestern Mutual | Mutual | A++ | 100 | Highest financial strength; consistent dividends. | Long-term whole life; conservative growth. |
| MassMutual | Mutual | A++ | 98 | Strong dividend history; robust disability integration. | Estate planning; complex business cases. |
| New York Life | Mutual | A++ | 100 | Massive surplus; conservative management. | Legacy planning; guaranteed income. |
| Prudential (Pruco) | Stock | A+ | 93 | Specialized underwriting for medical risks. | Term conversion; universal life innovation. |
| Pacific Life | Mutual | A+ | 95 | Leader in Indexed Universal Life (IUL) technology. | Cash value accumulation; market-linked growth. |
| Guardian Life | Mutual | A++ | 99 | Flexible "riders" and specialized policy design. | High-income professionals; DI integration. |
The Role of Concierge Underwriting and Reinsurance
For policies exceeding $20 million, a single insurance company often cannot carry the entire risk on its own books. This introduces the concept of Reinsurance. When you apply to a premium carrier, they may "shop" your risk to global reinsurers like Swiss Re or Munich Re.
The right company for a large case is one with "automatic binding authority." This means the carrier has such a strong relationship with its reinsurers that it can approve a $50 million policy without waiting weeks for the reinsurer's independent medical review. Furthermore, premium carriers often provide "concierge underwriting," where a dedicated underwriter is assigned to your case, allowing for direct communication between your medical team, your financial advisor, and the insurer’s medical director.
Avoiding Common Pitfalls in Premium Selection
Even with a top-rated company, high-value policies can fail if they are structured incorrectly. Prospective policyholders should be wary of the following:
- Illustrations vs. Reality: Many brokers show "illustrations" based on a 6% or 7% interest rate. However, if the carrier has the right to increase internal charges, that 7% growth may be eroded. Look for a carrier with a history of maintaining low Cost of Insurance (COI) charges.
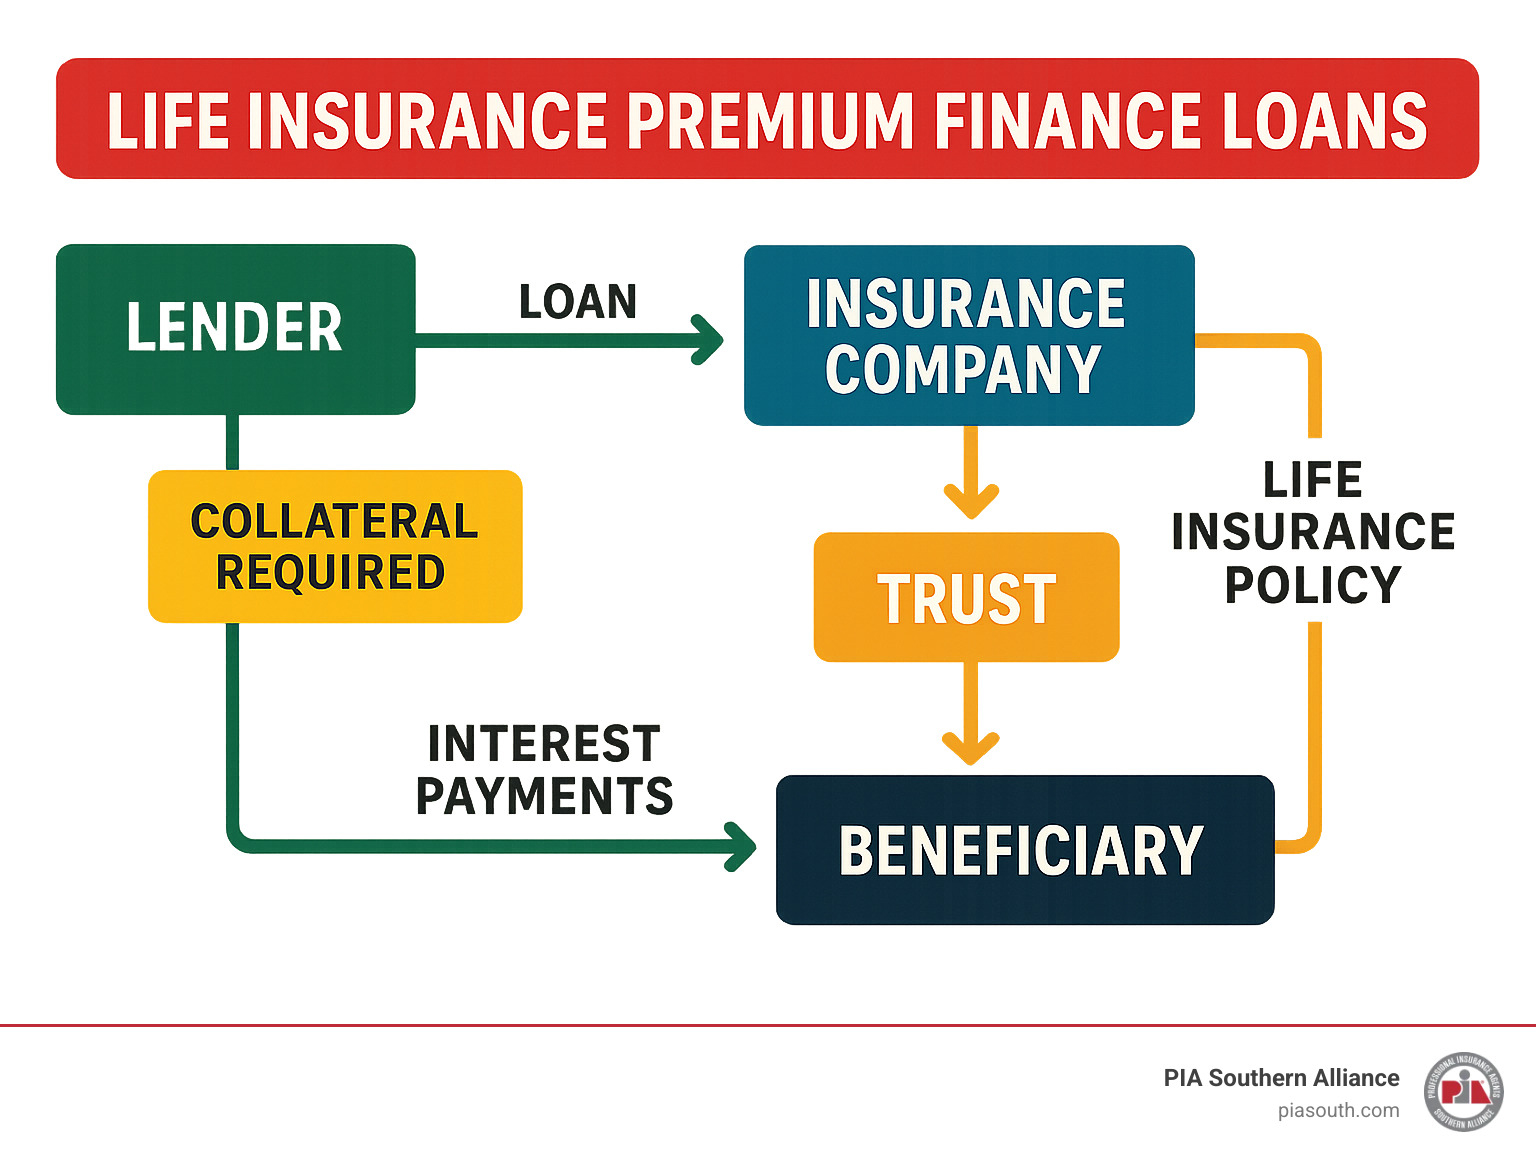
- Surrender Charges: Premium policies often have high surrender charges in the first 10 to 15 years. If you need liquidity, you must choose a company that offers "High Early Cash Value" riders, which are specifically designed for corporate-owned life insurance (COLI) or premium financing.
- The "Sunset" of the TCJA: With many provisions of the Tax Cuts and Jobs Act (TCJA) having expired or shifted by 2026, estate tax exemptions have lowered significantly. The right carrier must offer policies that can be easily owned by an Irrevocable Life Insurance Trust (ILIT) to ensure the death benefit remains outside the taxable estate.
Essential Policy Riders for High-Net-Worth Individuals
A "premium" policy should be more than a death benefit; it should be a multi-functional financial tool. Ensure your chosen carrier offers these specific riders:
- Long-Term Care (LTC) or Chronic Illness Rider: This allows you to accelerate a portion of the death benefit to pay for care if you become unable to perform activities of daily living. In 2026, "hybrid" policies that combine life and LTC are the standard for premium clients.
- Waiver of Premium: If you become disabled, the insurance company pays the premiums for you. For high-premium policies (e.g., $100,000+ per year), this is a critical safety net.
- Guaranteed Insurability Rider: Allows you to purchase additional coverage at specific intervals without undergoing a new medical exam, which is vital if your estate grows faster than anticipated.
- Substitution of Insured: Common in business settings (Buy-Sell agreements), this allows a company to move the coverage from one key executive to another without starting a new policy.
Frequently Asked Questions
What is a Comdex score and why does it matter for premium life insurance?
The Comdex score is a composite ranking from 1 to 100 that represents the average percentile of a company across all major rating agencies (A.M. Best, S&P, Moody's, and Fitch). For premium life insurance, a Comdex score of 90+ is the benchmark for safety. It ensures that the company is consistently recognized as a top-tier financial institution, reducing the risk that your policy will be affected by a single agency’s downgrade.
Can I buy a premium life insurance policy through my bank?
While some private banks offer life insurance, they usually act as brokers for the carriers mentioned above. For a truly "premium" experience, it is often better to work with an independent high-net-worth advisory firm that can compare multiple carriers. Banks may be limited to a "captive" list of insurers, whereas an independent advisor can access specialized underwriting and "jumbo" reinsurance markets that a local bank branch cannot.
How does the 2026 tax landscape affect my choice of insurance company?
By 2026, the federal estate tax exemption levels have likely decreased compared to the early 2020s. This makes the "financial capacity" of the insurance company more important, as more individuals require larger policies to cover estate tax liabilities. You need a company that is experienced in working with Irrevocable Life Insurance Trusts (ILITs) and has a legal department that can facilitate complex ownership structures without administrative delays.
Is "mutual" always better than "stock" for high-value policies?
Not necessarily. While mutual companies are excellent for long-term whole life and dividends, stock companies often lead the market in Indexed Universal Life (IUL) and Variable Universal Life (VUL) products. If your primary goal is aggressive cash value growth or low-cost term insurance for a specific business debt, a stock company might offer more competitive pricing and modern digital platforms.
What is "Jumbo" underwriting?
Jumbo underwriting refers to the process used when an individual applies for a total amount of insurance (across all companies) that exceeds a certain threshold, typically $35 million to $50 million. The "right" premium company must have established treaties with global reinsurers to handle these amounts efficiently. If a company lacks experience in jumbo underwriting, the medical and financial requirements can become unnecessarily intrusive and the approval process can take months.
Next Steps for Finding Your Ideal Carrier
To find the right premium life insurance company, begin by defining your primary objective: is it wealth transfer, estate liquidity, or tax-advantaged growth? Once your goal is clear, request a "market study" from an independent advisor that compares at least three carriers with a Comdex score of 90 or higher. Focus on "internal internal rate of return (IRR)" on the death benefit at your life expectancy, rather than just the lowest annual premium. Finally, ensure the carrier has a robust record of "in-force" management, meaning they treat existing policyholders as well as they treat new applicants.
Image Gallery
Select an image to open it in a new tab.




Simon Caldwell
Enterprise Technology and Systems Editor
